

Understanding the Administration of Estates and Trusts
The administration of estates and trusts is the process of managing and distributing a person’s assets after they die. This complex legal procedure ensures that debts are paid and remaining assets are properly transferred to beneficiaries.
Here’s what you need to know about estate and trust administration:
| Type | Definition | Court Supervision | Privacy | Timeline |
|---|---|---|---|---|
| Estate Administration | Process of settling a deceased person’s financial affairs through probate | Required | Public record | Typically 6-18 months |
| Trust Administration | Managing trust assets according to trust document terms | Generally not required | Private | Can be immediate to ongoing |
Estate administration (also called probate) involves:
- Validating the will
- Appointing an executor or administrator
- Inventorying assets
- Paying debts and taxes
- Distributing remaining assets to beneficiaries
Trust administration involves:
- Successor trustee taking control
- Identifying and managing trust assets
- Paying trust expenses and taxes
- Distributing assets according to trust terms
- Potentially ongoing management of assets
The process can be overwhelming, especially during a time of grief. Even seemingly simple estates can require several months to settle due to legal requirements and potential complications.
I’m Paul E. Deloughery, founder of Sudden Wealth Protection Law with over 25 years of experience helping Arizona families steer the administration of estates and trusts, including my own personal experience with inheritance challenges that drives my commitment to protecting client legacies.

Quick administration of estates and trusts definitions:
What Is Estate Administration?
Estate administration is the legal process of settling a deceased person’s financial affairs under court supervision. This process, commonly known as probate, happens when someone passes away with assets in their individual name.
In Arizona, the journey begins when an executor (named in the will) or administrator (appointed by the court when there’s no will) files a petition with the probate court. Once approved, the court issues Letters Testamentary or Letters of Administration – powerful legal documents that authorize the personal representative to handle the estate’s affairs.
I’ve always appreciated how one probate judge described it: “The executor stands in the shoes of the deceased, handling the business they can no longer handle themselves.” It’s a responsibility that combines honor with significant duty.
Key Duties of an Executor
Being an executor means wearing many hats. You’ll need to inventory and secure assets, creating a comprehensive list of everything the deceased owned at death. This includes homes, vehicles, bank accounts, investments, and personal belongings.
You’ll also need to obtain appraisals to determine fair market values, especially for real estate, businesses, or valuable collections. Professional appraisers are often worth their weight in gold here.
Another crucial task is notifying creditors. Arizona law requires giving creditors an opportunity to file claims against the estate, typically by publishing notices in local newspapers and directly contacting known creditors.
After reviewing claims, you’ll pay valid debts from estate assets according to priorities established by Arizona law. Then comes the paperwork – filing tax returns including the decedent’s final income tax return and any required estate tax filings.
Once debts and taxes are settled, you can distribute remaining assets to beneficiaries according to the will or Arizona intestacy laws. Finally, you’ll need to file a final accounting with the court and beneficiaries, documenting all financial activity.
Alice, one of our Phoenix clients, put it perfectly: “I never realized how many details were involved. From gathering death certificates to tracking down insurance policies to filing multiple tax returns—it was overwhelming. Having professional guidance made all the difference.”
Estate Assets and Debts Defined
An estate includes everything a person owned at death, minus what they owed. But not all assets go through probate (more on that later).
Probate assets typically include real property like homes and land titled solely in the deceased’s name, personal property such as vehicles and jewelry, financial accounts without beneficiary designations, business interests, and intellectual property rights.
On the flip side, estate debts may include mortgage loans, credit card balances, personal loans, medical bills, unpaid taxes, and utility bills. Arizona law establishes a specific order for paying these debts, with funeral expenses, administration costs, and certain taxes generally taking priority.
The good news for most families is that estate taxes affect relatively few Arizonans. For 2023, the federal estate tax exemption sits at $12.92 million per individual ($25.84 million for married couples). And unlike some states, Arizona does not impose a state estate or inheritance tax.
The administration of estates and trusts process can feel daunting, but with proper guidance, you can steer it with confidence. Each estate is unique, with its own challenges and timeline, but understanding these basics helps create a roadmap for the journey ahead.
What Is Trust Administration?
Trust administration is the process of managing trust assets according to the terms of the trust document. Unlike estate administration, trust administration generally happens outside of court supervision, giving you more privacy and often allowing for faster distribution of assets.
When someone with a trust passes away, the successor trustee (named in the trust document) steps into the role of managing the trust assets. This transition happens immediately, with no need for court approval.
Immediate Post-Death Trustee Tasks
When a trustmaker (also called a grantor or settlor) dies, the successor trustee faces several important responsibilities right away:
First, you’ll need to obtain death certificates – multiple certified copies, since most financial institutions will want an original. Then, review the trust document carefully to understand exactly what the trustmaker wanted regarding asset management and distribution.
Arizona law requires trustees to notify beneficiaries and provide them with certain information, including relevant portions of the trust. You’ll also need to obtain a tax identification number (EIN) from the IRS for the trust, as it can no longer use the deceased trustmaker’s Social Security number.
Working with financial institutions to retitle assets is another crucial step, showing your authority as successor trustee. You’ll need to inventory and value assets, creating a detailed list with date-of-death values.
Setting up trust accounting helps track income, expenses, and distributions, while paying debts and taxes ensures all obligations are met. Finally, you’ll either distribute or manage assets according to the trust terms.
“The certification of trust was invaluable,” shared Michael, a successor trustee in Scottsdale. “Instead of showing banks the entire trust document with all its private details, I could provide just this summary document to prove my authority.”
A certification of trust is essentially a shortened version that verifies the trust exists, identifies the trustees, and confirms their powers – all without revealing private details about beneficiaries or distributions.
Differences from Estate Administration
The administration of estates and trusts involves distinct processes. Trust administration stands apart from estate administration in several important ways:
Trust administration typically occurs without court oversight, while estate administration requires court approval for major actions. The privacy factor is significant – trust details remain confidential, unlike probate records which become public.
The timeline also differs considerably. Trust administration can begin immediately after death and often wraps up more quickly than probate. Trustees generally have greater flexibility than executors, whose actions are limited by court supervision.
Many trusts are designed for ongoing management and can continue for generations, while estates are settled and closed. Finally, trust administration is often less expensive than probate, avoiding court fees and potentially reducing attorney fees.
Many married couples set up trusts that split into subtrusts after the first spouse dies. For example, a typical revocable living trust might divide into a Survivor’s Trust (containing the surviving spouse’s assets) and a Bypass Trust (containing the deceased spouse’s assets up to the estate tax exemption amount). This structure requires careful accounting and asset allocation.
The role of trustee carries significant responsibility, but with proper guidance, you can fulfill these duties with confidence while honoring your loved one’s wishes.
Administration of Estates and Trusts: Probate vs. Non-Probate Assets
Understanding which assets go through probate and which don’t is perhaps the most bewildering aspect of administration of estates and trusts. This distinction isn’t just academic—it fundamentally changes how property transfers after someone passes away.
Probate vs. Non-Probate Assets
When someone passes away, their assets generally follow one of two paths. Probate assets must travel through the court-supervised probate process and include property titled solely in the deceased’s name, their portion of property owned as “tenants in common,” and personal belongings without designated beneficiaries.
On the other hand, non-probate assets take a direct route to their new owners, bypassing probate entirely. These include assets held in a trust, life insurance policies with named beneficiaries, retirement accounts with designated beneficiaries, financial accounts with payable-on-death designations, and property owned as “joint tenants with right of survivorship.”
I often hear clients express surprise at this distinction. As one recently told me, “I thought having a will meant avoiding probate. I was shocked to learn my husband’s accounts still had to go through court because we hadn’t added beneficiary designations.” This misconception is incredibly common.
Even with a perfectly drafted will, assets must go through probate unless they’re specifically structured as non-probate assets. This is where a pour-over will becomes valuable. It works alongside a trust by “catching” any assets not transferred to the trust during life and directing them to the trust after death. However—and this is critical to understand—these assets still must go through probate before reaching the trust.
Non-Probate Transfers and Arizona Law
Arizona law provides several mechanisms that enable non-probate transfers, keeping assets out of court proceedings:
Life insurance proceeds flow directly to named beneficiaries without probate under Arizona law. The process is straightforward—the insurance company simply requires a death certificate and claim form to release funds.
Retirement accounts like IRAs and 401(k)s transfer to named beneficiaries outside of probate. While this is primarily governed by federal law, Arizona courts fully recognize these transfers.
Arizona has accepted payable-on-death (POD) and transfer-on-death (TOD) designations through Arizona Revised Statutes §14-6101 through §14-6107. These designations allow financial accounts and even vehicles to transfer directly to beneficiaries without court involvement.
Property held in joint tenancy with right of survivorship automatically passes to surviving joint owners without probate under Arizona Revised Statutes §33-431. This simple ownership structure can save families significant time and expense.
These non-probate transfers are governed by Arizona’s version of the Uniform Probate Code, found in Title 14 of the Arizona Revised Statutes, which provides clear mechanisms for transferring assets outside of probate.
Funding an Asset Vault Trust (541 Trust)
At Sudden Wealth Protection Law, we’ve developed a specialized solution called the Asset Vault Trust, a type of 541 Trust. This irrevocable trust offers superior asset protection while maintaining flexibility through a special power of appointment—a combination that provides both security and adaptability.
The Asset Vault Trust shields your assets from creditors, lawsuits, and divorcing spouses while preserving family wealth across generations. The special power of appointment built into the trust maintains flexibility that most irrevocable trusts lack. This structure can also provide tax benefits in certain situations while keeping assets both private and out of probate.
When we help clients fund an Asset Vault Trust, we strategically transfer assets to the trust while ensuring they maintain appropriate control. This requires thoughtful planning and execution to maximize protection while meeting your specific family needs.
As one client shared after setting up their Asset Vault Trust, “I sleep better knowing my children’s inheritance is protected from whatever life might throw their way, but I still have the flexibility to adapt if circumstances change.”
For more details about this powerful estate planning tool, visit our Asset Vault Trust page where we explain the advantages in greater depth.
Step-by-Step Guide to Settling an Estate or Trust
The administration of estates and trusts follows distinct timelines and procedures, but both require careful attention to detail and statutory deadlines.
Estate Administration Checklist
Here’s a comprehensive checklist for Arizona estate administration:
Immediate Steps (First Week)
- Locate the will and other estate planning documents
- Make funeral arrangements
- Secure the deceased’s residence and valuable property
- Forward mail and notify Social Security of the death
- Order 10-15 certified death certificates
Initial Administration (First Month)
- Meet with an estate attorney to review the will and process
- File the will with the probate court in the county where the deceased lived
- Petition the court for appointment as personal representative
- Publish notice to creditors in a local newspaper (starts the 4-month creditor claim period in Arizona)
- Obtain an EIN for the estate from the IRS
- Open an estate bank account
- Begin inventorying assets and gathering statements
Middle Phase (2-6 Months)
- Complete inventory of all assets with date-of-death values
- File inventory with the court (if required)
- Review and pay valid creditor claims
- Manage assets during administration
- File the deceased’s final income tax return
- File estate income tax returns if the estate earns income
- Determine if estate tax return is required (for estates over exemption amount)
Final Phase (6-12+ Months)
- Pay all final bills and taxes
- Prepare final accounting for beneficiaries and the court
- Distribute remaining assets to beneficiaries
- Obtain receipts from beneficiaries
- File closing documents with the court
- Close the estate bank account
In Arizona, the personal representative must wait at least four months after publishing notice to creditors before distributing assets, to allow creditors time to file claims.
Trust Administration Checklist
For trust administration in Arizona, follow these steps:
Immediate Steps (First Week)
- Locate the trust document and amendments
- Secure trust property
- Order 5-10 certified death certificates
- Contact the estate planning attorney who drafted the trust
Initial Administration (First Month)
- Review the trust document to understand distribution instructions
- Obtain a tax ID number (EIN) for the trust
- Open a trust bank account or update account registrations
- Send required notifications to beneficiaries (within 60 days under Arizona law)
- Begin inventorying trust assets and gathering statements
- Determine if a pour-over will needs to be probated for any non-trust assets
Middle Phase (1-3 Months)
- Complete inventory of all trust assets with date-of-death values
- Pay debts and ongoing expenses from trust assets
- Manage investments according to trust terms and prudent investor standards
- Determine if the trust should be split into subtrusts
- Allocate assets between subtrusts if required
- File the deceased’s final income tax return
- File fiduciary income tax returns for the trust
Final Phase (3-6+ Months or Ongoing)
- Prepare trust accountings for beneficiaries
- Make distributions according to trust terms
- Obtain receipts and releases from beneficiaries receiving final distributions
- Continue managing any ongoing trusts for beneficiaries
- Provide regular accountings for ongoing trusts
A key difference in Arizona trust administration is that, unlike probate, there’s no mandatory waiting period for creditors before making distributions. However, prudent trustees often wait a reasonable time to ensure all obligations are known.
Coordinating Dual Roles in the Administration of Estates and Trusts
Often, the same person serves as both executor of the estate and trustee of the trust, requiring careful coordination between these roles.
When managing both estate and trust administration:
- Understand the relationship between documents: The pour-over will and trust work together, with the will directing probate assets to the trust.
- Maintain separate accounts: Keep estate and trust funds in separate accounts to avoid commingling.
- Coordinate tax filings: Ensure consistency across estate and trust tax returns.
- Track expenses appropriately: Allocate expenses to either the estate or trust as appropriate.
- Consider consolidated distributions: When possible, coordinate distributions to minimize paperwork and confusion for beneficiaries.
- Provide clear communication: Explain to beneficiaries which assets come from the estate versus the trust.
Sarah, who served as both executor and trustee for her father’s estate in Mesa, shared: “Having separate checklists for the estate and trust responsibilities helped me stay organized. I kept separate files and accounts but coordinated the overall process to make it more efficient.”
Fiduciary Duties, Liability, and Compensation
When you step into the role of an executor or trustee, you’re taking on a serious legal responsibility. Both roles are considered fiduciaries in the administration of estates and trusts – a fancy legal term that simply means you must put the interests of others (the beneficiaries) ahead of your own.
Think of being a fiduciary like being entrusted with someone else’s children. You wouldn’t make decisions based on what’s easiest for you – you’d make decisions based on what’s best for the kids.
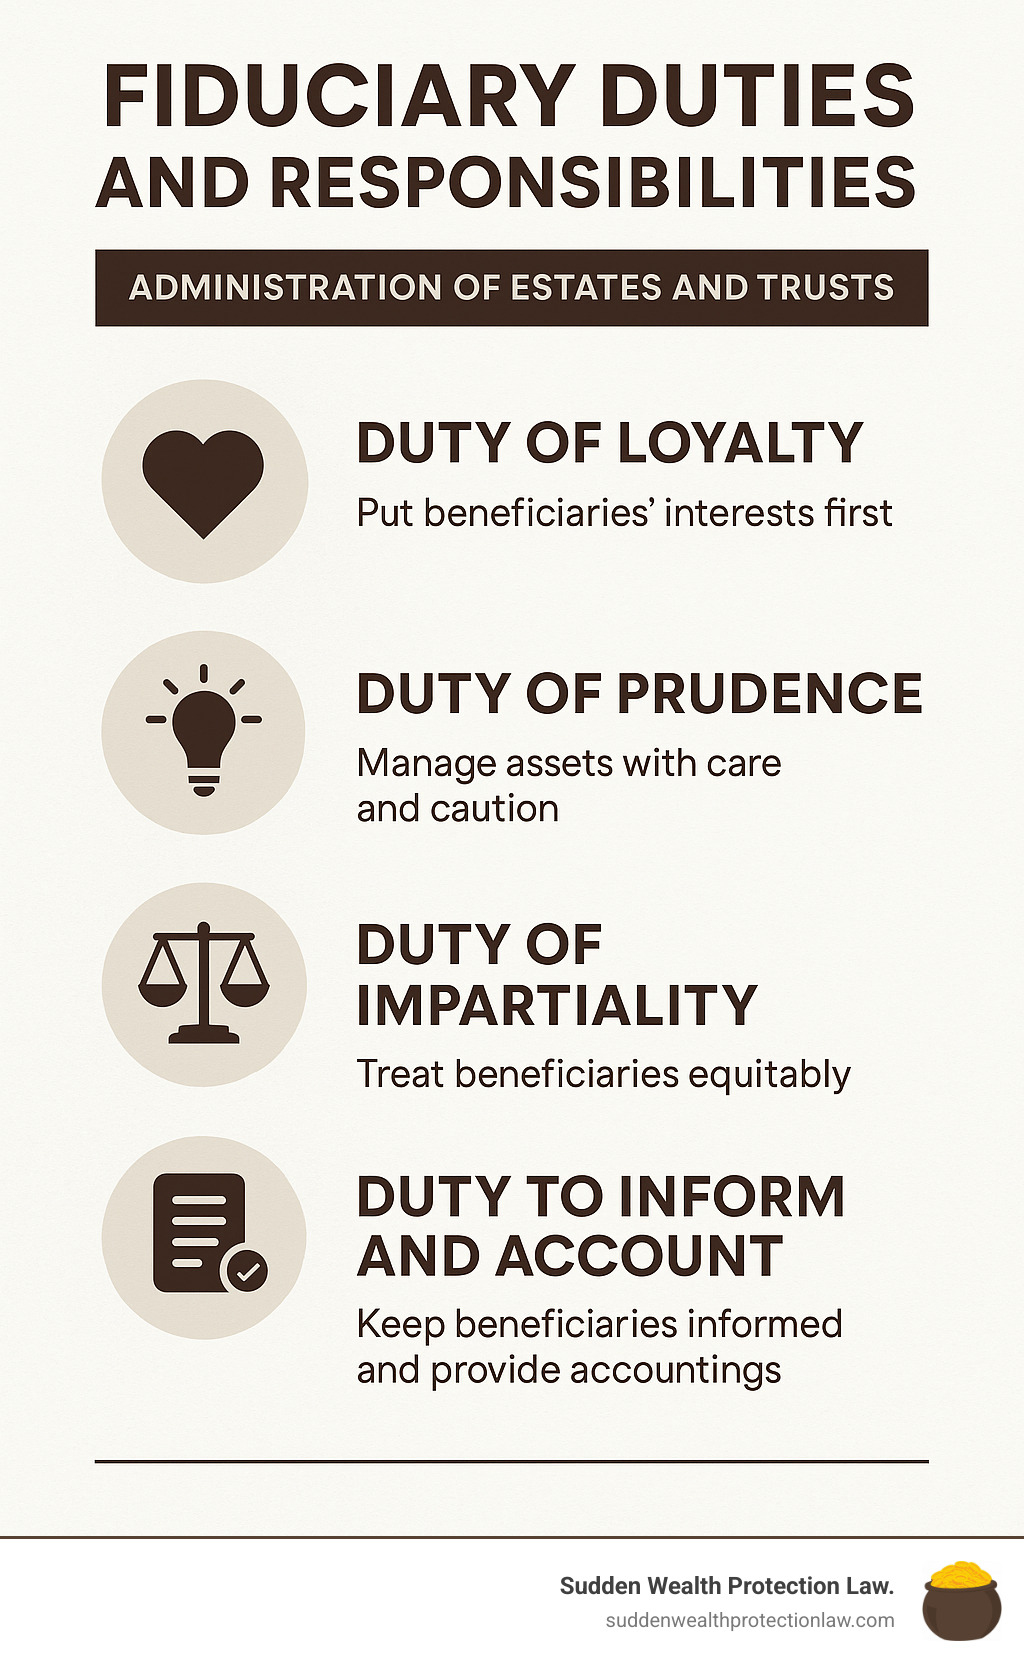
Your core responsibilities include the duty of loyalty – putting the beneficiaries first and avoiding any conflicts of interest. You also have a duty of prudence, which means using reasonable care in managing assets. Don’t worry – you’re not expected to be a financial genius, but you are expected to make thoughtful decisions.
The duty of impartiality requires treating all beneficiaries fairly. As one of my clients put it, “I can’t play favorites, even though my sister drives me crazy!” And finally, the duty to inform and account means keeping beneficiaries in the loop and providing clear financial records.
These aren’t just suggestions – they’re legal obligations that can come with personal liability if you don’t follow them. For more information about fiduciary duties in general, you can refer to this Wikipedia article on fiduciary.
Avoiding Common Fiduciary Pitfalls
I’ve seen many well-meaning executors and trustees stumble into problems. Here’s how to protect yourself:
Keep meticulous records of everything you do. Every penny spent, every decision made, every conversation with beneficiaries – document it all. As one trustee told me, “The notebook I kept saved me when a beneficiary questioned a distribution three years later.”
Never, ever mix estate or trust money with your personal funds – not even for a day. Keep separate accounts and clear boundaries.
When it comes to investments, diversification is key unless the trust specifically says otherwise. Arizona’s Uniform Prudent Investor Act requires it. One executor learned this lesson the hard way when he kept all the estate’s money in a single stock that plummeted in value.
Move the process along at a reasonable pace. Courts understand that administration of estates and trusts takes time, but unnecessary delays can get you in hot water.
Communicate regularly with beneficiaries – even when there’s not much to report. A simple email saying “Still waiting to hear back from the IRS” can prevent frustrated calls and suspicion.
And perhaps most importantly, avoid any hint of self-dealing. Don’t buy assets from the estate for yourself, hire yourself for services, or make decisions that benefit you at the expense of beneficiaries.
In Arizona, your personal assets could be at risk if you breach your duties. Smart fiduciaries protect themselves by getting fiduciary liability insurance, securing bonds when required, seeking professional advice for tricky situations, and getting consent or court approval for any potentially controversial moves.
How Executors and Trustees Are Paid
Good news – you don’t have to do all this work for free. Fiduciaries are entitled to reasonable compensation.
For executors (also called personal representatives in Arizona), compensation might be spelled out in the will. If not, you can follow statutory guidelines, charge an hourly rate, or agree on a flat fee. One executor in Scottsdale shared, “I tracked my hours and charged a reasonable rate based on the complexity of tasks. For routine bill payments, I charged less than for handling the sale of real estate.”
Trustees might find compensation terms in the trust document itself. Without specific guidance, you can charge reasonable fees based on industry standards, a percentage of trust assets, or hourly rates.
Unlike some states, Arizona doesn’t set specific fee schedules, instead requiring that fees be “reasonable.” Courts look at factors like the estate’s complexity, time required, expertise needed, and results achieved.
Professional fiduciaries like trust companies typically charge 1-2% of assets annually, with minimums for smaller trusts. Family members sometimes waive fees, but don’t feel obligated to work for free – the responsibilities and time commitment are substantial.
I often remind clients that being a fiduciary is like taking on a part-time job that requires significant responsibility. Fair compensation acknowledges the important service you’re providing.
For more details about fiduciary fees and how they’re calculated, visit our Estate Settlement and Administrative Trusts page.
Timeline, Costs, and When to Seek Help
Navigating the administration of estates and trusts is a journey that varies widely in both duration and expense. Like any journey, it helps to have realistic expectations about the road ahead.

For estate administration in Arizona, the clock typically runs:
- Simple estates without complications might wrap up in 6-9 months
- Average estates generally take 9-18 months to fully settle
- Complex estates can stretch well beyond 18 months
Trust administration generally moves more quickly:
- Straightforward distribution trusts often complete in 3-6 months
- Trusts requiring subtrust creation usually take 6-12 months
- Ongoing dynasty or multigenerational trusts continue for years or decades
“I thought I’d be done in a few months,” shares Thomas, who served as executor for his brother’s Phoenix estate. “It ended up taking over a year. The house needed repairs before selling, a creditor disputed a claim, and we had to file an estate tax return. The costs added up, but having professional guidance saved us from making expensive mistakes.”
Several factors can significantly extend these timelines. Family disagreements over the will or trust can add months or years. Unusual assets like businesses or collectibles require special handling and valuation. Tax complications, missing heirs, creditor disputes, and even court backlogs in busy jurisdictions can all slow the process considerably.
The financial side of administration includes several components. For probate in Arizona, expect to pay court filing fees, attorney fees, accountant fees, appraisal costs, executor compensation, asset management expenses, and tax preparation fees. Total costs typically range from 3% to 7% of the estate value, with legal fees representing the largest portion.
Trust administration costs are generally lower—typically 1% to 3% of trust assets—since you’re avoiding court involvement. However, complex trusts with ongoing management needs may incur higher long-term expenses.
Red-Flag Situations Requiring Professional Guidance
While some straightforward estates and trusts can be administered without extensive professional help, certain situations should send you straight to an expert’s office:
Contested wills or trusts demand immediate legal attention. When beneficiaries challenge document validity or distribution decisions, the stakes are too high to steer alone.
Insolvent estates (where debts exceed assets) require precise handling. Arizona law establishes specific priorities for creditor payment, and mistakes can result in personal liability.
Complex assets like family businesses, intellectual property, valuable collections, or cryptocurrency require specialized expertise to properly value and transfer.
Cross-border property creates jurisdictional complications. Real estate or assets in multiple states or countries may require additional probate proceedings or tax filings.
When distributions might affect beneficiaries with special needs who receive government benefits, careful planning is essential to avoid benefit loss.
The growing world of digital assets—from cryptocurrency to online businesses—presents unique challenges in access, valuation, and transfer.
If you encounter these red flags, consider consulting our Probate and Trust Administration Attorney in Phoenix to steer these complexities safely.
Planning Ahead to Streamline the Administration of Estates and Trusts
The best gift you can give your loved ones is a well-organized estate. Consider these proactive steps to simplify future administration:
Create and maintain a detailed asset inventory listing all accounts, properties, and valuables with their locations and approximate values. This simple document can save your executor or trustee countless hours of detective work.
Review your beneficiary designations regularly. These forms override your will for retirement accounts, life insurance, and certain other assets. Keeping them current and consistent with your overall plan is crucial.
Consider funding your trust during your lifetime. Assets properly transferred to your trust avoid probate entirely, saving time and money later.
Update your planning documents every 3-5 years or after major life events like marriage, divorce, births, or significant financial changes.
Organize important papers in a secure but accessible location, and make sure your fiduciaries know where to find them. A binder with estate planning documents, insurance policies, property deeds, and financial statements can be invaluable.
Have honest conversations with family members about your wishes and plans. While sometimes uncomfortable, these discussions prevent confusion and conflict later.
For significant assets, explore improved protection through specialized structures like an Asset Vault Trust. These irrevocable trusts offer superior asset protection while maintaining flexibility.
Lisa from Tempe implemented these strategies and later shared: “When my husband passed away unexpectedly, I was grateful for our organization. Having an updated trust, clear asset inventory, and proper beneficiary designations made a world of difference during an incredibly difficult time.”
Taking these steps now won’t just streamline future administration—it will give you and your loved ones invaluable peace of mind.
Frequently Asked Questions about Administration of Estates and Trusts
What Assets Go Through Probate in Arizona?
When someone passes away in Arizona, their loved ones often wonder which assets must travel through the probate process and which ones can bypass this court procedure.
Assets that typically require probate in Arizona include property solely in the deceased’s name without any beneficiary designations. This means your home, land, bank accounts without POD designations, and vehicles without beneficiary forms all head to probate court.
Personal belongings like furniture, jewelry, and collections also generally require probate, as do business interests without proper succession planning. These assets remain “stuck” until the court authorizes their transfer.
On the flip side, many assets can avoid probate completely. Trust-held property transfers according to trust terms without court involvement. Assets with designated beneficiaries—like life insurance policies and retirement accounts—pass directly to named individuals. Jointly owned property with right of survivorship automatically transfers to the surviving owner.
Arizona offers some unique probate-avoidance tools, including beneficiary deeds for real estate (permitted under A.R.S. § 33-405) and a special form for vehicles called “Beneficiary Designation for Vehicle Title Transfer Upon Death.”
Mark from Chandler shared his experience: “I was surprised to learn my father’s checking account needed probate even though he had a will. If we’d added a simple payable-on-death designation, we could have avoided months of court proceedings.”
How Long Does Trust Administration Take?
Many people assume trust administration happens quickly—after all, isn’t avoiding probate delays one of the main benefits of having a trust? The reality is more nuanced.
Trust administration timelines vary significantly based on complexity. Simple distribution trusts where assets pass directly to beneficiaries typically take 3-6 months to complete. This time allows for gathering assets, paying final expenses, filing necessary tax returns, and preparing final accountings.
Trusts with ongoing subtrusts—such as those protecting assets for young children or providing lifetime support for a spouse—involve an initial administration period of 3-6 months, followed by ongoing management that might last decades.
Several factors influence how long the process takes:
- Asset complexity: Real estate, business interests, and unusual investments take longer to handle than simple financial accounts
- Tax requirements: Trusts with substantial assets may require estate tax returns, which add time
- Beneficiary dynamics: Unfortunately, family disagreements can significantly extend the timeline
- Trust provisions: Some trusts include mandatory waiting periods or complex distribution formulas
Jennifer, a trust beneficiary in Scottsdale, told us: “When Mom died, I thought I’d receive my inheritance within weeks since she had a living trust. I didn’t realize the trustee needed time to identify all assets, pay final expenses, file tax returns, and prepare proper accountings. The six-month process was actually quite reasonable once I understood what was involved.”
Can an Executor or Trustee Be Personally Sued?
This question touches on one of the most serious aspects of administration of estates and trusts—personal liability. The answer is yes, executors and trustees can absolutely be sued personally for breaches of their fiduciary duties.
Serving as an executor or trustee means stepping into a legal role with significant responsibilities. When you accept this position, you’re agreeing to manage someone else’s assets with the highest degree of care, loyalty, and prudence.
Personal liability can arise from various situations, including self-dealing (putting your interests above beneficiaries), negligent asset management, ignoring the terms of the will or trust, making improper distributions, mishandling taxes, or improperly addressing creditor claims.
In Arizona, beneficiaries generally have two years from finding a breach (or when they reasonably should have finded it) to file a claim against a fiduciary. This timeline extends in cases involving fraud or concealment.
To protect yourself when serving as a fiduciary:
- Thoroughly understand your duties and the governing documents
- Consult with professionals (attorneys, accountants) when needed
- Document your decision-making process and keep excellent records
- Maintain regular, transparent communication with beneficiaries
- Consider fiduciary liability insurance for larger estates or trusts
- Obtain signed releases from beneficiaries before making distributions
David, who served as trustee for his parents’ trust, shared: “I nearly made a serious mistake by selling trust property to my son at a discount. Thankfully, our attorney warned me this could be considered self-dealing. Instead, we had the property professionally appraised and sold at fair market value, avoiding what could have been a costly lawsuit.”
You’re not obligated to accept the role of executor or trustee. If you’re uncomfortable with the responsibilities or potential liability, you can decline to serve, allowing an alternate or court-appointed fiduciary to step in.
Conclusion
Navigating the administration of estates and trusts is like steering a ship through sometimes challenging waters – it demands attention to detail, strong organization, and a clear understanding of your legal responsibilities. While the process might seem overwhelming at first, breaking it down into manageable steps makes the journey much more approachable.
What have we learned on this journey together? Let me highlight the essential takeaways:
First, estate administration through probate follows specific court-supervised procedures with public oversight, while trust administration generally happens privately, guided by the trust document itself. This difference in privacy and court involvement significantly impacts how quickly assets can be distributed to loved ones.
Second, understanding which assets must go through probate versus which ones transfer automatically outside probate is absolutely crucial for effective planning. This knowledge can save your family significant time, money, and stress during an already difficult period.
Third, serving as an executor or trustee comes with serious fiduciary responsibilities. These aren’t just suggestions – they’re legal obligations that, if not fulfilled properly, could result in personal liability. This is why careful consideration should be given before accepting these roles.
Fourth, proper planning before death makes all the difference. Through thoughtful tools like the Asset Vault Trust, appropriate beneficiary designations, and comprehensive documentation, you can dramatically simplify the administration process for your loved ones.
Finally, some situations truly call for professional guidance – especially when dealing with contested documents, tax complications, or unusual assets. There’s no shame in seeking help; in fact, it’s often the wisest course of action.
At Sudden Wealth Protection Law, we understand that every family’s story is unique. We provide personalized guidance through the administration process, helping executors and trustees fulfill their duties with confidence while protecting the interests of everyone involved. We’ve walked this path with countless Arizona families, and we bring that experience to each new situation we encounter.
Whether you’re currently serving as an executor or trustee and feeling overwhelmed, or you’re planning ahead to ease the burden on your loved ones, we’re here to help. Our experience with Arizona estate and trust administration allows us to steer the complexities efficiently while providing compassionate support during what’s often a difficult time.
For more information about our probate and trust administration services, visit our Probate and Trust Administration page.

