

Understanding the Advantages of an Irrevocable Trust
When it comes to protecting your family’s future, few legal tools offer the strength and security of an irrevocable trust. Yes, the word “irrevocable” might sound intimidating at first. After all, who wants to make permanent decisions about their assets? But here’s the thing – that permanence is exactly what gives these trusts their remarkable power.
I’ve seen how the advantages of an irrevocable trust arrangements can transform a family’s financial security. When properly structured, these legal vehicles create a fortress around your assets that courts, creditors, and even government agencies must respect.
What makes these trusts so valuable? Let me walk you through it.
First, they provide exceptional asset protection. Once assets are placed in the trust, they’re no longer yours on paper – making them virtually untouchable by creditors, lawsuit plaintiffs, or unexpected financial threats.
The tax benefits are equally compelling. By removing assets from your taxable estate, you can significantly reduce or even eliminate estate taxes, preserving more wealth for your loved ones.
For families concerned about long-term care costs, these trusts can be invaluable for Medicaid planning. They help you qualify for needed assistance while protecting assets you’ve worked a lifetime to build.
Perhaps most importantly, irrevocable trusts give you lasting control over how your assets are distributed. Even after you’re gone, your wishes for how and when beneficiaries receive funds remain legally binding.
And let’s not forget the privacy and probate avoidance these trusts provide. Your family’s financial matters stay private, outside the public record of probate court, saving time, money, and potential family conflict.
I’m Paul E. Deloughery, founder of Sudden Wealth Protection Law. For over 25 years, I’ve helped Arizona families implement the advantages of irrevocable trust strategies to protect their legacies. This mission is personal for me – after inheriting and subsequently losing $14 million due to poor planning, I’ve dedicated my career to ensuring others don’t face similar hardships.
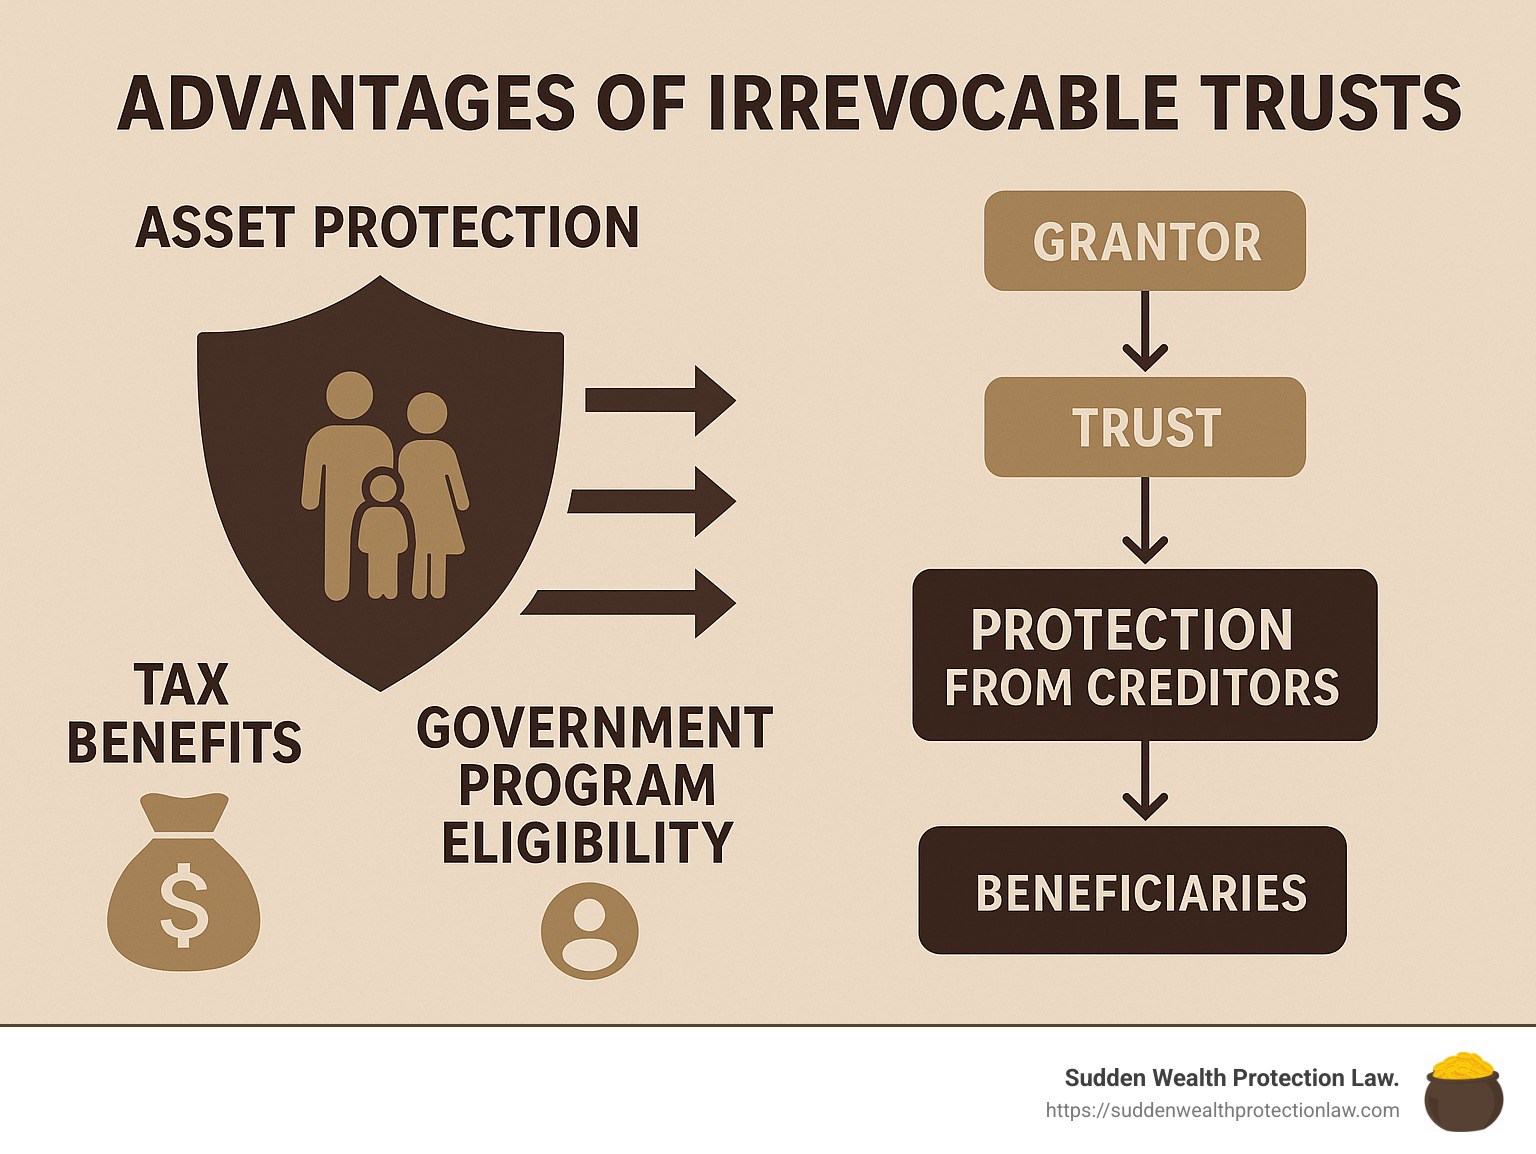
How an Irrevocable Trust Differs From a Revocable Trust
Let’s talk about what makes irrevocable trusts unique, especially compared to their more flexible cousins, revocable trusts. This distinction is crucial to understanding the advantages of irrevocable trust arrangements.
Think of a revocable trust as a financial vehicle where you remain in the driver’s seat. You can change lanes, adjust your speed, or even pull over and get out whenever you want. You maintain complete control to modify terms, remove assets, or dissolve the trust entirely. While this flexibility seems appealing, it comes with a significant downside: because you’re still behind the wheel, those assets remain legally yours—meaning they stay vulnerable to creditors, lawsuits, and estate taxes.
An irrevocable trust, by contrast, is more like putting your assets on a train with a predetermined destination. Once you’ve placed your assets on board, you’re essentially stepping off and letting the train continue its journey according to the route you’ve established. This permanent transfer of assets out of your name creates a true legal separation that courts and creditors must respect.
| Feature | Revocable Trust | Irrevocable Trust |
|---|---|---|
| Control by grantor | Complete | Limited or none |
| Asset protection | Minimal | Substantial |
| Estate tax benefits | None | Significant |
| Medicaid/benefits planning | Ineffective | Effective (with proper timing) |
| Modification | Easy | Difficult or impossible |
| Privacy | Yes | Yes |
| Probate avoidance | Yes | Yes |
I’ve heard many clients express concerns about giving up control, but as one estate planning attorney bluntly put it, “Revocable trusts simply aren’t durable enough to be worth it overall” when it comes to serious asset protection and tax planning. The advantages of irrevocable trust arrangements stem directly from this permanence—it’s not a bug, it’s a feature!
More info about revocable vs irrevocable trusts
Key Parties & Moving Parts
Every irrevocable trust involves several key players who make the whole arrangement work:
The grantor (sometimes called settlor or trustor) is the person who creates and funds the trust—that’s you. The trustee is the person or institution who manages the trust assets according to the trust document. The beneficiaries are those who ultimately receive benefits from the trust. Some trusts also include a trust protector, an optional role appointed to oversee the trustee and make certain changes when necessary.
Here’s an important point many people miss: the grantor cannot serve as trustee of their own irrevocable trust if they want to achieve the full tax and asset protection benefits. As estate planning attorney James Burns notes, “The grantor cannot serve as trustee or beneficiary, ensuring assets are fully out of personal control.”
An unfunded trust is merely an empty vessel. For the advantages of irrevocable trust arrangements to actually work, assets must be properly retitled in the name of the trust to receive protection.
Timing Matters: Living vs Testamentary
Timing can significantly impact how your irrevocable trust functions. These trusts come in two main varieties based on when they take effect:
Living irrevocable trusts (inter vivos) are created and funded during your lifetime. They offer immediate asset protection and tax benefits, but are subject to “look-back periods” for Medicaid planning—typically five years. This means timing matters tremendously if nursing home care might be in your future.
Testamentary irrevocable trusts only spring to life after your death through instructions in your will. While they provide no lifetime benefits to you, they avoid those pesky look-back period concerns for Medicaid.
Most asset protection strategies require a “seasoning period” before reaching full effectiveness. In most states, assets typically need to be held in an irrevocable trust for one to two years before they’re fully protected from creditors’ claims. Think of it as letting the concrete fully set before testing its strength.
Advantages of an Irrevocable Trust #1: Iron-Clad Asset Protection
When it comes to protecting what you’ve worked so hard to build, the advantages of irrevocable trust arrangements truly shine. Think of an irrevocable trust as a financial fortress – one that keeps your hard-earned assets safely beyond the reach of creditors, lawsuits, and unexpected judgments.
Financial advisor Daniel A. Timins explains it beautifully: “An irrevocable trust operates on a fundamental legal principle – you cannot be forced to surrender what you no longer own.” That’s the beauty of it. Once you properly transfer assets into an irrevocable trust, they legally belong to the trust itself, not to you personally.
This protection is particularly valuable if you’re:
- A doctor or surgeon facing potential malpractice claims
- A business owner worried about personal liability
- A real estate investor with multiple properties
- Anyone working in a profession where lawsuits are common
A well-crafted trust with proper spendthrift provisions creates a shield between your assets and potential creditors. In Florida, for example, state statute 736.0501 specifically requires these provisions for effective creditor protection.
Here’s a real-world example: Imagine you’ve set aside $100,000 in an irrevocable trust for your adult child. Years later, if they default on a $75,000 mortgage, the lender can’t touch those trust assets – they remain protected for your child’s future needs.
How the advantages of an irrevocable trust insulate you from creditors
The magic happens because of a simple legal reality – courts recognize that assets in an irrevocable trust are no longer yours. When creditors come knocking, they can only pursue what you actually own. The separation created by a properly established trust isn’t just a legal technicality – it’s a powerful boundary that courts generally respect.
That said, there are important limitations to be aware of. You can’t transfer assets specifically to avoid existing creditors – that’s called fraudulent conveyance, and courts can reverse such transfers. As one attorney puts it, “Transfers intended to defraud creditors can be challenged and set aside.” Timing matters tremendously.
For those seeking maximum protection, Domestic Asset Protection Trusts (DAPTs) in states with favorable laws offer improved safeguards. Just remember – these specialized irrevocable trusts must be established before any legal claims arise. An ounce of prevention truly is worth a pound of cure.
Optional Flexibility Tools
Now, I know what you might be thinking – “Irrevocable sounds so… permanent.” And you’re right! But modern trust design has evolved to include flexibility while maintaining protection:
A Trust Protector serves as an independent third party with limited powers to adapt your trust as circumstances change. Think of them as your trust’s guardian angel, able to make adjustments when necessary.
Decanting Provisions allow your trustee to essentially “pour” assets from your original trust into a new one with more favorable terms – like transferring wine from an old bottle to a better one.
A Special Power of Appointment gives someone (often a beneficiary) limited ability to redirect assets without triggering tax consequences. It’s like having a pressure release valve that maintains the integrity of the overall system.
At Sudden Wealth Protection Law, our Asset Vault Trust incorporates a special power of appointment that provides maximum flexibility while maintaining robust asset protection. This approach gives you the best of both worlds – the security of irrevocability with the adaptability modern families need.
More info about asset protection
Advantages of an Irrevocable Trust #2: Cutting Estate & Gift Taxes
Another significant advantage of irrevocable trust arrangements is their ability to reduce or eliminate estate taxes.

As of 2024, the federal estate tax exemption stands at a generous $13.61 million per individual. While this high threshold means most American families won’t face federal estate taxes right now, there’s a ticking clock that makes tax planning with irrevocable trusts increasingly relevant for many more families.
The current exemption is scheduled to drop dramatically—by roughly half—when the Tax Cuts and Jobs Act (TCJA) sunsets on December 31, 2025. Think of it as a closing window of opportunity. Additionally, several states impose their own estate taxes with much lower thresholds that might catch you by surprise.
“Irrevocable trusts remove assets from your taxable estate,” as estate planning attorney Travis R. Walker often tells clients. “For high-net-worth individuals and even those with moderate wealth, this can result in significant tax savings for future generations.”
Most families find success with one of these tax-focused trust strategies:
Irrevocable Life Insurance Trusts (ILITs) keep life insurance proceeds outside your taxable estate. This is particularly powerful since life insurance death benefits can be substantial, and an ILIT ensures those funds pass to your loved ones without a tax bite.
Grantor Retained Annuity Trusts (GRATs) allow you to transfer appreciation on assets with minimal gift tax impact. You receive income for a set period, after which any remaining assets pass to your beneficiaries—often with little to no gift tax.
Spousal Lifetime Access Trusts (SLATs) offer a clever approach—removing assets from your estate while indirectly maintaining access through your spouse. This provides both tax benefits and a safety net.
Charitable Remainder Trusts (CRTs) generate income while supporting causes you believe in. You receive tax benefits today while making a meaningful difference for organizations you care about.
Why the advantages of irrevocable trust matter before 2026
The approaching TCJA sunset creates a genuine sense of urgency for estate tax planning. As one of my clients recently said, “I never thought I’d need to worry about estate taxes, but with the exemption dropping soon, suddenly it’s on my radar.”
When the sunset occurs, exemption limits will decrease from approximately $12.92 million per individual to around $5.49 million (adjusted for inflation). This dramatic drop will expose many more family estates to federal estate taxes—potentially including yours.
This limited window gives you a chance to use the current higher exemption amounts through irrevocable trust strategies. By establishing these trusts now, you can effectively “lock in” today’s more generous exemption before it vanishes.
Beyond the basic exemption, married couples can take advantage of portability, effectively doubling their exemption amount. Valuation discounts through family limited partnerships or LLCs inside irrevocable trusts can create advantageous reductions in taxable value. And certain irrevocable trust structures can still allow for a step-up in basis at death, minimizing capital gains taxes when heirs eventually sell inherited assets.
Funding Strategies That Work
Not all assets are created equal when it comes to funding irrevocable trusts for tax planning. I’ve seen the best results with these approaches:
Life insurance works beautifully in an ILIT structure, completely removing the death benefit from your taxable estate. For families with substantial insurance coverage, this alone can save hundreds of thousands in potential estate taxes.
Appreciating assets that are likely to increase in value benefit most from being removed from your estate early. Think of real estate, business interests, or securities with strong growth potential. The future growth happens inside the trust, completely outside your taxable estate.
Minority interests in family businesses can be transferred with valuable valuation discounts. By fragmenting ownership, you can potentially transfer more value while using less of your lifetime exemption.
As we often tell clients at Sudden Wealth Protection Law, “Use irrevocable trusts to remove appreciable assets from your taxable estate while providing beneficiaries with a step-up in basis.” This balanced approach protects family wealth from unnecessary taxation while positioning the next generation for financial success.
With the 2026 exemption reduction approaching faster than many realize, now is the ideal time to explore how the advantages of irrevocable trust strategies might benefit your family’s tax situation for generations to come.
Advantages of an Irrevocable Trust #3: Qualifying for Medicaid & SSI
One of the most practical advantages of irrevocable trust arrangements is how they help families steer the complex world of government benefits. For many families facing the prospect of long-term care or supporting a loved one with special needs, these trusts become invaluable financial lifelines.
When it comes to Medicaid eligibility, the harsh reality is that individuals can typically have no more than $2,000 in countable assets (with slight variations by state). Without proper planning, this often forces families into the heartbreaking position of spending down a lifetime of savings before qualifying for needed care.
“Many families don’t realize they have options beyond simply depleting their assets,” explains Paul Deloughery. “A properly structured irrevocable trust creates a legal pathway to preserve family wealth while still qualifying for essential benefits.”
The same principles apply to Supplemental Security Income (SSI), which maintains similar strict asset limits that can be addressed through specialized irrevocable trusts.
Medicaid Look-Back and Penalty Periods
The critical challenge with Medicaid planning involves timing. The program imposes a five-year “look-back period” where any asset transfers made during this time can trigger penalties that delay eligibility.
This makes early planning absolutely essential. As one client recently shared, “We didn’t realize we needed to start planning five years before my mother would need care—I wish we’d understood the timeline sooner.”
Effective Medicaid planning strategies with irrevocable trusts typically include:
Home protection through carefully structured trusts that shield your primary residence while maintaining certain rights to live there
Spend-down avoidance by legally repositioning assets outside your countable resources
Income-only arrangements that allow access to investment income while protecting the principal
One specialized tool worth considering is the irrevocable funeral trust—a unique planning vehicle that sets aside funds specifically for funeral expenses while immediately removing those assets from Medicaid calculations, regardless of when it’s established. Learn more about the benefits of an irrevocable funeral trust.
Special Needs Planning Without Losing Aid
For families caring for members with disabilities, the advantages of irrevocable trust arrangements become even more significant. Special Needs Trusts (SNTs) serve as critical financial tools that improve quality of life without jeopardizing essential benefits.
These specialized irrevocable trusts come in two main varieties:
Third-party SNTs are established by parents, grandparents or other relatives using their own assets. These trusts can provide supplemental support without affecting benefit eligibility and can continue supporting the disabled person throughout their lifetime.
First-party SNTs are created using the disabled person’s own assets—often from settlements, inheritances or accumulated savings. These trusts allow the beneficiary to maintain eligibility while preserving assets for their care.
The Social Security Administration provides clear guidance on how these trusts work within benefit systems. As they explain in their Spotlight on Trusts, “Funds in a properly structured trust do not count as resources for SSI eligibility.”
What makes these trusts effective is their careful use of discretionary distribution standards. The trustee has authority to provide for supplemental needs not covered by government programs—things like additional therapies, education, recreation, and quality-of-life improvements—without disrupting benefit eligibility.
For many families we work with at Sudden Wealth Protection Law, these trusts create peace of mind knowing their loved ones will have both government support and additional resources managed by someone they trust. The careful balance these trusts create—maintaining eligibility while enhancing quality of life—makes them one of the most compassionate estate planning tools available.
Advantages of an Irrevocable Trust #4: Controlling When & How Heirs Receive Wealth
One of the most powerful advantages of irrevocable trust arrangements is the remarkable control they give you over your legacy. Unlike a simple will, these trusts allow you to guide how and when your loved ones receive their inheritance—even decades after you’re gone.
I’ve seen how this level of customization brings families tremendous peace of mind. As estate planning attorney James Burns puts it, “Irrevocable trusts ensure control over the distribution of assets to beneficiaries.” This control isn’t about being controlling—it’s about protecting those you love.
You might choose to establish age-based distributions, perhaps releasing funds in thirds at ages 25, 30, and 35. This approach gives beneficiaries time to mature financially before receiving their full inheritance. Or you might prefer milestone-based distributions that celebrate life achievements like college graduation, marriage, or purchasing a first home.
Some families incorporate incentive provisions that reflect their values, perhaps encouraging education, entrepreneurship, or charitable giving. For others, the primary goal is creating lifetime support that provides a safety net without encouraging dependency.
This thoughtful approach to inheritance becomes especially valuable when beneficiaries are young, financially inexperienced, or facing challenges like addiction or spending issues. It’s not about controlling from the grave—it’s about providing guidance and protection when it matters most.
Using Spendthrift & Discretionary Clauses
Two powerful provisions significantly improve your ability to protect beneficiaries both from external threats and sometimes from themselves:
Spendthrift clauses create a legal barrier that prevents beneficiaries from pledging or assigning their trust interests to creditors. This means that even if a beneficiary wanted to use their inheritance as collateral for a loan, they legally couldn’t—protecting those assets from potential loss.
Discretionary distribution standards give your chosen trustee flexibility in determining appropriate distributions. In Florida, these provisions allow trustees to distribute funds “in good faith under broad circumstances” as outlined in Florida statute 736.0501. This standard balances flexibility with protection.
I often share this real-world example with clients: Grandparents created a trust for their grandchildren requiring completion of college before receiving distributions. Years later, when one grandchild faced a gambling addiction, the trustee had the authority to withhold funds that would have fueled self-destructive behavior while still covering essential needs. The grandparents could never have anticipated this specific situation, but their thoughtful trust design protected their grandson during a vulnerable time.
Business Succession & Legacy Goals
For business owners, irrevocable trusts offer unique and powerful advantages for succession planning. Many of my clients have spent decades building successful businesses and understandably worry about what will happen when they’re no longer at the helm.
Continuity planning through an irrevocable trust ensures your business continues according to your vision, even when you’re no longer involved. You can establish specific guidelines for how the business should operate and who should make key decisions.
Management transition becomes smoother when you can separate ownership from management. This is particularly valuable when some heirs lack business experience or interest. The trust can own the business while professional managers handle day-to-day operations.
Equalization strategies help provide fair treatment when some heirs are active in the business and others aren’t. Without proper planning, this situation often creates family conflict and business disruption.
As I often explain to clients at Sudden Wealth Protection Law, “Transferring family business interests into an irrevocable trust ensures management continuity and avoids forced sale due to estate tax liabilities.” This approach has saved countless family businesses from becoming another statistic in the sobering reality that 70% of family businesses fail to survive to the second generation.
A particularly effective strategy involves dividing voting and non-voting interests strategically. This approach allows for professional management while preserving family ownership—giving you the best of both worlds for your business legacy.
For more comprehensive strategies on protecting your family’s wealth across generations, visit our family wealth protection resource page.
Advantages of an Irrevocable Trust #5: Privacy, Probate Avoidance & Peace of Mind
Another powerful advantage of irrevocable trust arrangements is the privacy they provide for your family and the complete avoidance of probate court.

You might not realize that probate isn’t just a simple formality – it’s actually a court process that comes with several serious drawbacks. When your estate goes through probate, your family’s private financial matters become public record, available for anyone to view. Imagine your nosy neighbor or estranged relatives having access to details about everything you owned and who received what!
Beyond this privacy invasion, probate typically takes anywhere from 6 to 18 months to complete, leaving your loved ones waiting during an already difficult time. The process isn’t free either – legal fees and court costs often consume between 3-7% of your estate’s total value. That can mean thousands or even tens of thousands of dollars that should have gone to your family instead going to attorneys and the court system.
Perhaps most concerning is that during probate, a judge has the final say over how your assets are distributed. Even with a will, court oversight can sometimes lead to outcomes you never intended.
“Trust assets avoid the public probate process, maintaining privacy,” explains attorney Paul Deloughery. “This keeps your family’s financial matters exactly where they belong – within the family.”
While both revocable and irrevocable trusts provide this privacy benefit, irrevocable trusts add those powerful asset protection and tax advantages we’ve already discussed. It’s like getting multiple benefits from a single planning tool.
Keeping Family Finances Out of Court
The privacy benefit goes beyond just avoiding public records. When your assets are held in an irrevocable trust, you’re also helping to minimize family disputes since the trust terms clearly spell out your wishes. Without this clarity, I’ve seen families torn apart fighting over assets and intentions.
Your beneficiaries also receive their inheritances much more quickly without court delays. Instead of waiting a year or more, distributions can often begin shortly after your passing, providing support when your loved ones may need it most.
The cost savings are substantial too. By avoiding probate, your estate saves significant legal and court fees – sometimes tens of thousands of dollars. As one client told me after we set up their trust, “I’m so relieved knowing my children won’t have to spend a small fortune just to receive what I’ve worked so hard to leave them.”
This privacy shield is especially valuable if you’re in the public eye or have a complex family situation where discretion matters. I’ve worked with blended families, business owners with sensitive competitive information, and high-profile individuals – all of whom greatly valued keeping their financial affairs private.
Coordinating With Other Documents
A truly effective estate plan doesn’t rely on an irrevocable trust alone. At Sudden Wealth Protection Law, we ensure your trust works in harmony with several other essential documents:
Your pour-over will acts as a safety net, capturing any assets that might not have been properly transferred into your trust during your lifetime. Think of it as a backup plan that ensures nothing falls through the cracks.
Powers of attorney designate someone you trust to manage financial matters if you become incapacitated. This prevents the need for a court-appointed guardian and keeps your affairs private even during your lifetime.
Healthcare directives provide guidance for medical decisions when you cannot speak for yourself. In addition to asset protection, these documents complete your comprehensive plan and give both you and your family tremendous peace of mind.
Together, these carefully crafted documents create a comprehensive shield protecting both your assets and your legacy. Many clients tell me the greatest benefit is simply knowing they’ve done everything possible to protect their loved ones and honor their wishes.
As one client recently shared, “I sleep better at night knowing my family won’t have to deal with courts, lawyers, and public scrutiny during an already difficult time. That peace of mind is priceless.”
Frequently Asked Questions about the Advantages of Irrevocable Trust
What assets can—and cannot—be placed in an irrevocable trust?
When clients first visit our office, they often wonder what they can actually put in their irrevocable trust. The good news is that most assets work beautifully in these protective arrangements.
You can generally transfer real estate, investment accounts, business interests, cash and securities, and valuable personal property into your irrevocable trust. These assets benefit from the full protection the trust provides.
However, not everything belongs in an irrevocable trust. Retirement accounts like IRAs and 401(k)s typically should remain outside your trust and pass directly through beneficiary designations. Placing these in a trust can trigger immediate tax consequences—something none of us want!
Everyday vehicles often stay outside trusts to minimize liability exposure. And certain business interests may have transfer restrictions in their operating agreements. As one of our business clients finded, “I had to get partner approval before transferring my LLC interest to my trust—something I hadn’t anticipated.”
Before transferring any business ownership, take a careful look at your company’s governing documents to avoid unintended consequences.
Who should consider setting one up?
Not everyone needs an irrevocable trust, but for the right person, they’re invaluable. In my 25+ years of practice, I’ve found these arrangements particularly beneficial for:
High-net-worth individuals whose estates approach or exceed the federal estate tax exemption. With the tax exemption scheduled to drop in 2026, this applies to more families than you might think.
Professionals with litigation exposure like doctors, lawyers, and real estate developers benefit tremendously from the asset protection these trusts provide. One physician client told me, “I sleep better knowing my family’s financial future isn’t tied to a potential malpractice claim.”
Business owners seeking both asset protection and a clear succession plan find these trusts invaluable. They create a roadmap for your business long after you’re gone.
Families with special needs members can ensure lifetime support without jeopardizing government benefits. The peace of mind this brings is immeasurable.
Individuals planning for long-term care who want to qualify for Medicaid while preserving assets for their loved ones often find these trusts to be the perfect solution, especially when established early.
As I often tell clients, “If you have something worth protecting—whether from creditors, taxes, or even your beneficiaries’ potential poor decisions—an irrevocable trust deserves serious consideration.”
What are the main disadvantages to keep in mind?
I believe in complete transparency with my clients. While the advantages of irrevocable trust arrangements are substantial, they come with important trade-offs you should understand before proceeding.
The most significant consideration is the loss of direct control. Assets transferred are no longer yours to manage directly—that’s the very feature that provides protection, but it requires accepting a fundamental change in your relationship to those assets.
These trusts involve complexity and cost both in setup and ongoing administration. They require experienced legal counsel to establish correctly and often need professional trustees or advisors for proper management.
True to their name, irrevocability means changes are difficult or impossible without specific provisions built in from the start. This is why we incorporate flexibility tools like special powers of appointment in our Asset Vault Trust.
Finally, be aware of potential tax implications. Irrevocable trusts often face higher income tax rates on retained earnings, which requires thoughtful planning about distributions and investments.
One client put it perfectly: “Setting up my irrevocable trust was like installing a high-security vault. It’s not something I access daily, but I’m incredibly grateful to have it when I need that level of protection.”
The key is balancing these limitations against the substantial benefits with professional guidance custom to your specific situation.

Conclusion
The advantages of irrevocable trust arrangements truly shine when they’re thoughtfully designed to match your family’s unique circumstances. While the word “irrevocable” might initially give you pause, this permanence is precisely what gives these trusts their protective power.
I’ve seen how the right irrevocable trust strategy brings families tremendous peace of mind. At Sudden Wealth Protection Law, we specialize in Arizona estate planning with a particular focus on creating asset protection strategies that balance security with the flexibility modern families need.
Our signature Asset Vault Trust incorporates special powers of appointment that provide maximum asset protection while maintaining adaptability as your family’s situation evolves. This unique approach gives you the best of both worlds – rock-solid protection with thoughtful flexibility built right in.
Through my 25+ years of experience, I’ve helped countless families and business owners protect what they’ve worked so hard to build. Having personally lost a $14 million inheritance due to poor planning, I understand on a deeply personal level why proper protection matters.
The right irrevocable trust doesn’t just shield assets – it communicates your values and wishes to future generations. It creates a lasting legacy that extends far beyond the financial resources you leave behind.
Every family’s situation is unique, which is why cookie-cutter solutions rarely work well. Your trust strategy should reflect your specific goals, assets, and concerns. I invite you to schedule a consultation where we can discuss how these powerful tools might benefit your family’s future.
Remember: The greatest gift you can leave your loved ones isn’t just your financial assets, but the thoughtful planning that protects those assets and communicates your values for generations to come.
More info about revocable vs irrevocable trusts

