

Understanding Arizona Asset Protection Trusts: What You Need to Know
When it comes to safeguarding your hard-earned assets, Arizona asset protection trusts offer a powerful shield against potential creditors and unexpected lawsuits. But here’s the interesting part – Arizona doesn’t actually have specific legislation authorizing Domestic Asset Protection Trusts (DAPTs). Don’t worry though! This doesn’t mean you’re out of options.
Think of asset protection in Arizona as a menu of choices, each with its own flavor of security:
| Option | Description | Level of Protection |
|---|---|---|
| Hybrid Asset Protection Trust | Trust where grantor isn’t a beneficiary but can be added later | Strong |
| Traditional Estate Planning Trust | Revocable living trust for probate avoidance | Minimal protection |
| Statutory Exemptions | $400,000 homestead, retirement accounts, life insurance | Moderate |
| Out-of-State DAPT | Trust established in one of 17 DAPT-friendly states | Strong but complex |
I’ve seen it countless times – hardworking Arizonans feeling overwhelmed by the prospect of protecting their wealth from potential threats. You’ve built something valuable, and the thought of losing it to a lawsuit or creditor claim can keep you up at night. I get it.
The good news? Even without specific DAPT legislation in our state, you can create remarkably effective protection strategies using what we call “hybrid trust structures.” These legal tools combine the best elements of irrevocable trusts with thoughtful beneficiary designations.
Here’s how a hybrid Arizona asset protection trust works in practice: you set up an irrevocable trust that initially doesn’t name you as a beneficiary. Instead, the trust benefits people you care about – typically family members. The clever part is that a trusted individual (like a trust protector) can be given authority to add you as a beneficiary later if circumstances warrant it.
This approach creates a legal separation between you and your assets while maintaining a pathway to benefit from them indirectly if needed. It’s like having your cake and eating it too – just not right away!
I’m Paul E. Deloughery, founder of Sudden Wealth Protection Law, and I’ve guided hundreds of Arizona families through this exact process. Over my 25+ years working with Arizona asset protection trusts, I’ve finded that thoughtful planning makes all the difference between preserving wealth and watching it disappear.
The hybrid trust approach offers substantial protection while working within Arizona’s legal framework. While it requires more careful structuring than a standard DAPT might in other states, the peace of mind it provides is well worth the effort.

Asset Protection Trust Basics
Let’s talk about protecting your hard-earned wealth. Think of an asset protection trust as a financial fortress – it keeps your assets safe while giving you peace of mind about your family’s future.
What Is an Asset Protection Trust?
An Asset Protection Trust (APT) is like a financial safe house. It’s an irrevocable trust (meaning once it’s set up, it’s difficult to change) specifically designed to shield your assets from future creditors, lawsuits, and judgments.
Unlike the more common revocable living trusts that mainly help you avoid probate, Arizona asset protection trusts create a legal wall between you and your assets that can withstand serious legal challenges.
As Arizona attorney Thomas J. Bouman puts it: “Asset protection planning is the process of using legal strategies to shield personal and business assets from frivolous lawsuits and predatory creditors.” That’s exactly what these trusts aim to do.
The secret weapon in any effective APT is its spendthrift provision – legal language that prevents creditors from forcing distributions and stops beneficiaries from using their trust interest as collateral. This feature is what gives these trusts their protective power.
How Does It Work?
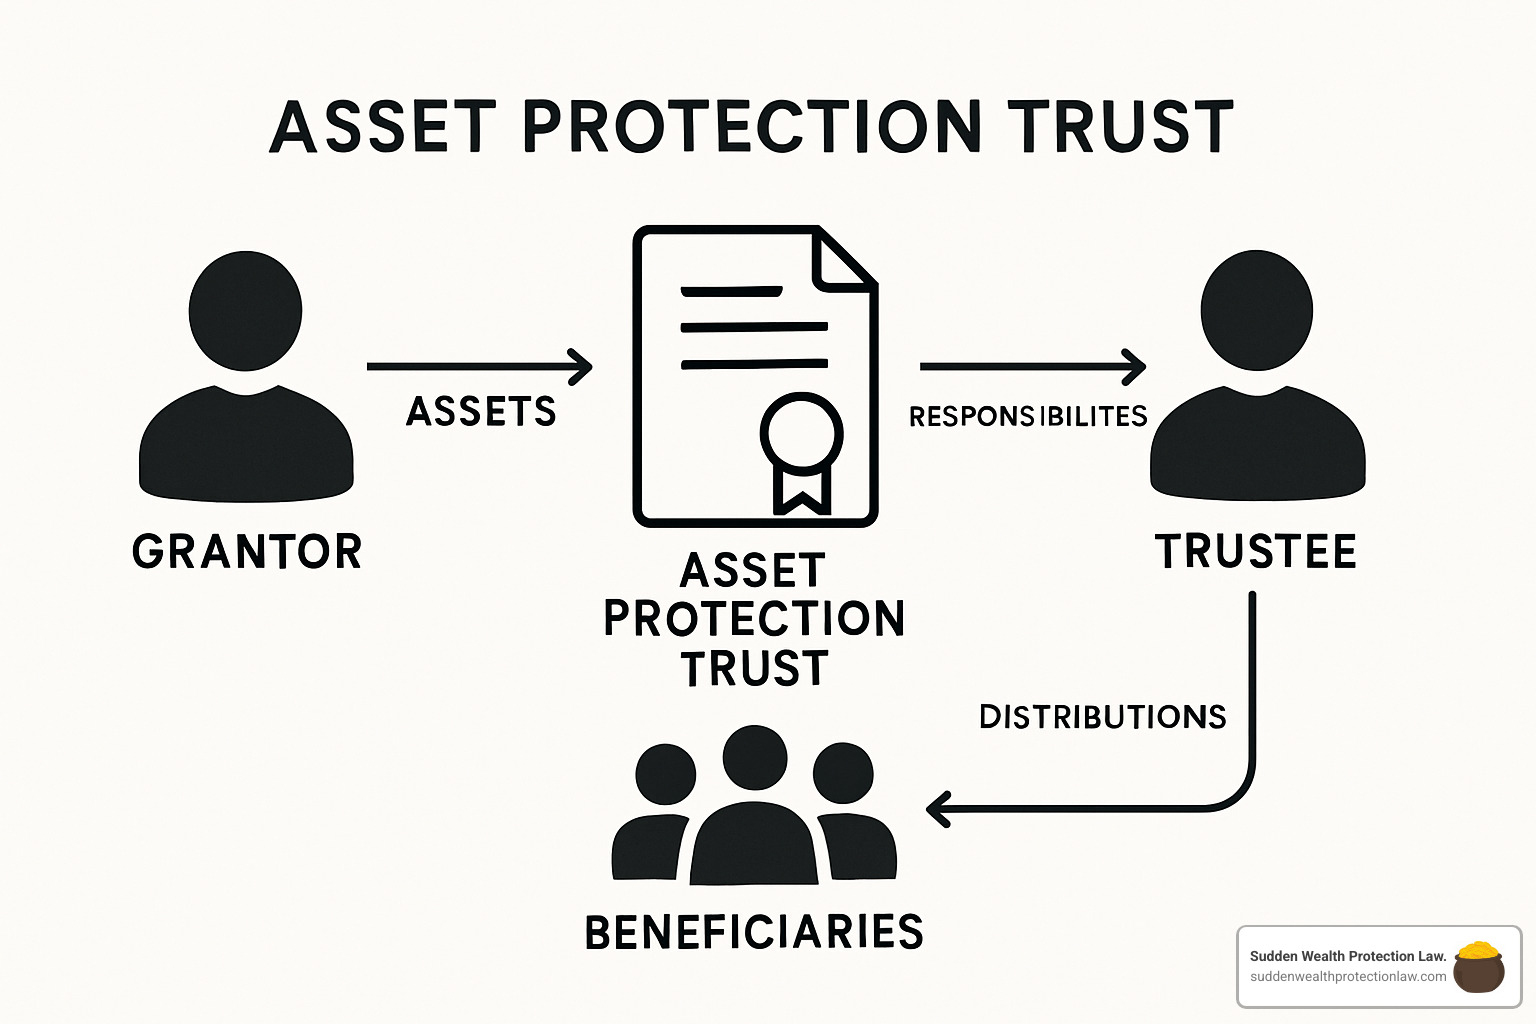
Asset protection trusts work through a three-party relationship:
- Grantor/Trustor: That’s you – the person creating the trust and transferring assets into it
- Trustee: An independent person or institution managing the trust assets
- Beneficiaries: The people who receive benefits from the trust
Here’s the catch – and it’s an important one. For an APT to work, you need to give up significant control. As one of my clients once said after I explained this concept, “So I’m trading control for protection?” Exactly right.
Think of it this way: “If I were on the front lines in a battle, with gunfire all around me, I’d rather be inside a tank (protection) than hiding under a camouflaged blanket (privacy).” Simply hiding assets provides far less protection than properly restructuring their ownership.
For maximum protection, you typically must:
– Choose someone else as trustee (not yourself)
– Give up direct access to trust assets
– Make the trust irrevocable (can’t easily change your mind)
– Remain financially solvent after transferring assets
Domestic vs Offshore APTs
When it comes to asset protection trusts, you have two main options: domestic and offshore.
Domestic Asset Protection Trusts (DAPTs) are established under U.S. state laws. Currently, 17 states have specific statutes allowing these self-settled asset protection trusts – including Nevada, Wyoming, Alaska, and South Dakota. Unfortunately, Arizona isn’t on this list (yet).
The track record for these trusts is impressive. Steve Oshins, a nationally recognized asset protection attorney, points out: “After 23 years, there still isn’t even one non-bankruptcy, non-fraudulent transfer case where a regular DAPT did not work. Not even one.” That’s why DAPTs have become increasingly popular despite being relatively new in American law.
Offshore Asset Protection Trusts are set up in foreign countries with favorable trust laws, such as the Cook Islands, Nevis, or Belize. These often provide stronger protection because they’re beyond the reach of U.S. courts. However, they’re more complex, more expensive, and come with additional reporting requirements.
As a general guideline, you should have at least $1 million in assets to justify setting up an APT, especially an offshore one, given the costs involved in creating and maintaining these structures.
Self-Settled vs Third-Party Trusts
There’s another important distinction to understand:
Self-settled trusts allow you to be both the person creating the trust AND a beneficiary. This arrangement only works in states with specific DAPT statutes. In states without DAPT legislation (like Arizona), self-settled trusts offer little protection.
Third-party trusts are created for someone other than yourself – like your spouse, children, or other loved ones. These trusts have long been recognized as providing solid asset protection in all states, including Arizona.
This is where the hybrid approach used in Arizona asset protection trusts comes in handy. We leverage the strength of third-party trusts while incorporating provisions that might allow you to become a beneficiary under certain circumstances later on.
I’ve seen these hybrid trusts provide tremendous peace of mind for my clients, especially business owners and professionals who face higher liability risks. They sleep better knowing their family’s financial future is protected, even if the unexpected happens.
Arizona Landscape: Domestic vs Hybrid
Arizona’s approach to asset protection isn’t as straightforward as in some other states. If you’re an Arizona resident looking to protect your wealth, you’ll need to understand this unique landscape to make smart choices.
Why Arizona Lacks a Statutory DAPT
Unlike 17 other states, Arizona hasn’t jumped on the Domestic Asset Protection Trust bandwagon. This isn’t just an oversight – it reflects Arizona’s traditional balancing act between protecting individuals and preserving creditors’ rights.
There was actually a glimmer of hope back in May 2020. The executive council for the Probate and Trust Section of the Arizona State Bar approved a proposal that would have created Arizona asset protection trusts through qualified spendthrift trusts. The proposed statute would have added A.R.S. §14-10821, stating: “A creditor may not satisfy a claim or liability of the trustor in either law or equity out of the trustor’s transfer to such trust or the trustor’s beneficial interest in such trust.”
But as of now, that proposal remains just that – a proposal. The legislature hasn’t enacted it into law, leaving Arizona residents to seek alternative protection strategies.
How a Hybrid DAPT Fills the Gap
This is where creativity comes into play. The hybrid DAPT approach offers Arizona residents a powerful workaround that many of my clients have successfully implemented.
Think of it as having your cake and eating it too – well, sort of. As one of my colleagues aptly put it, “A hybrid trust merges self-settled and third-party trust features for both control and strong creditor protection.”
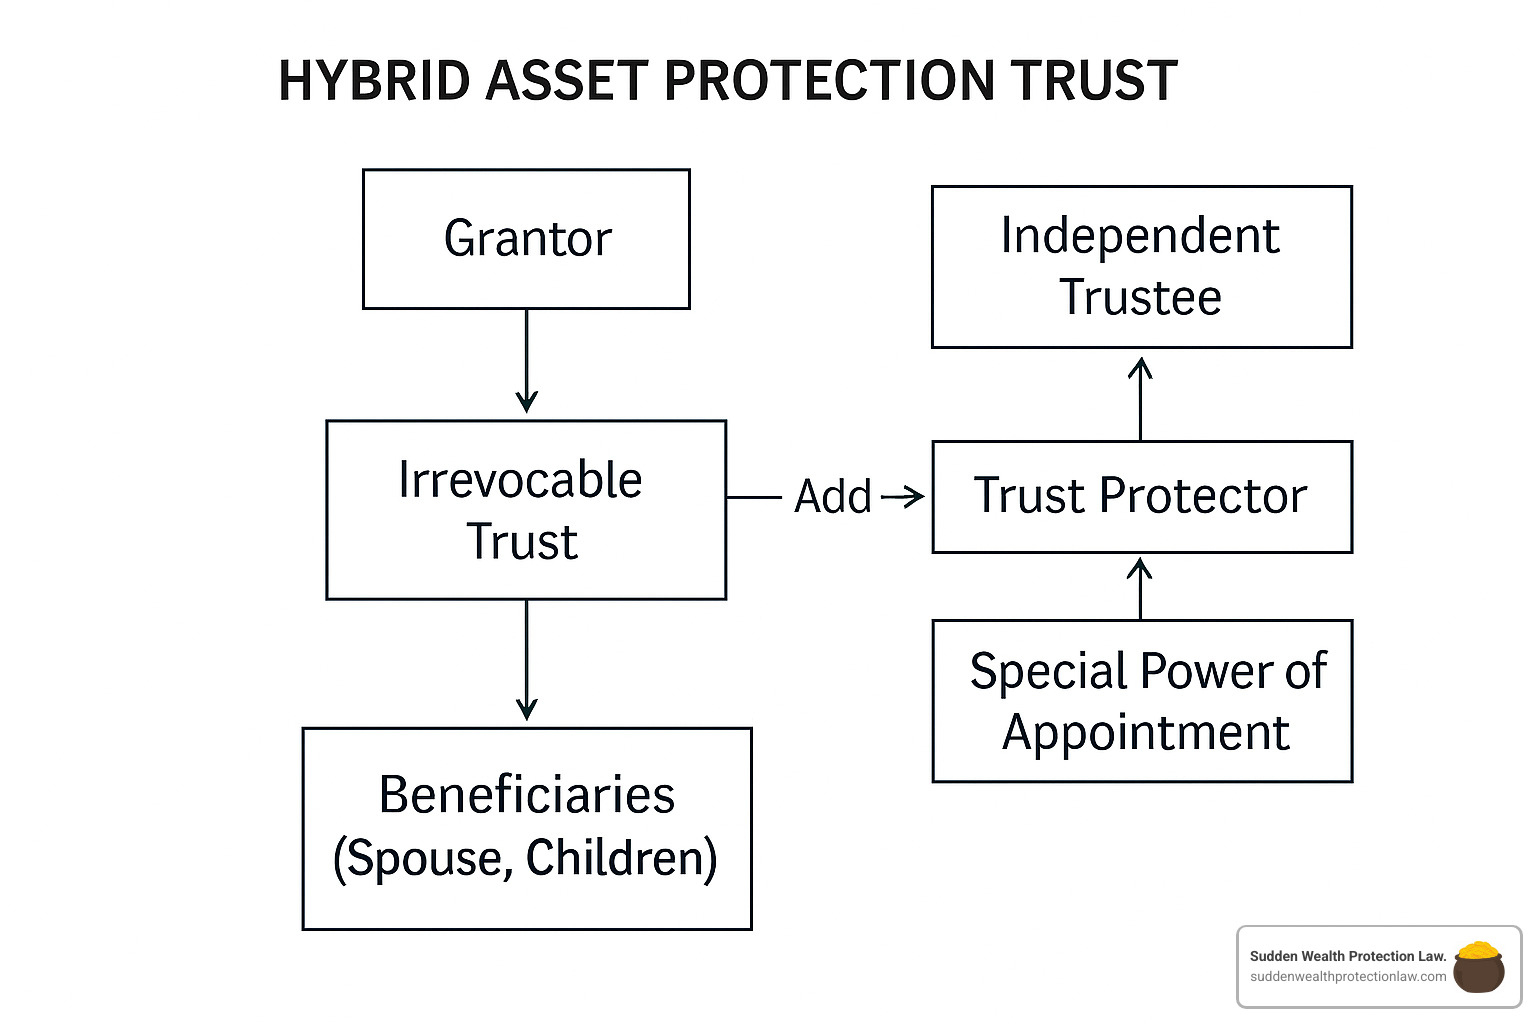
Here’s the basic framework:
- You establish an irrevocable trust, but instead of naming yourself as a beneficiary, you name only your loved ones (typically your spouse and children).
- You appoint someone you trust, but who’s independent, to serve as trustee.
- You include a special provision allowing a trust protector or someone with a special power of appointment to potentially add you as a beneficiary down the road if circumstances warrant.
- You transfer assets while remaining financially solvent (this part is crucial).
This structure – sometimes called a “Family Gifting Trust” or “Spousal Lifetime Access Trust” (SLAT) – gives you indirect access to trust assets through your family while maintaining robust creditor protection.
In fact, renowned asset protection attorney Steve Oshins ranks the hybrid DAPT approach as an “A+” strategy – even better than regular DAPTs, which he gives a “B+.” Why? Because hybrid trusts sidestep the legal uncertainties that can arise when someone tries to use another state’s DAPT laws.
Statutory Exemptions Still Available
Even without dedicated DAPT legislation, Arizona law provides several valuable asset protection tools that shouldn’t be overlooked.
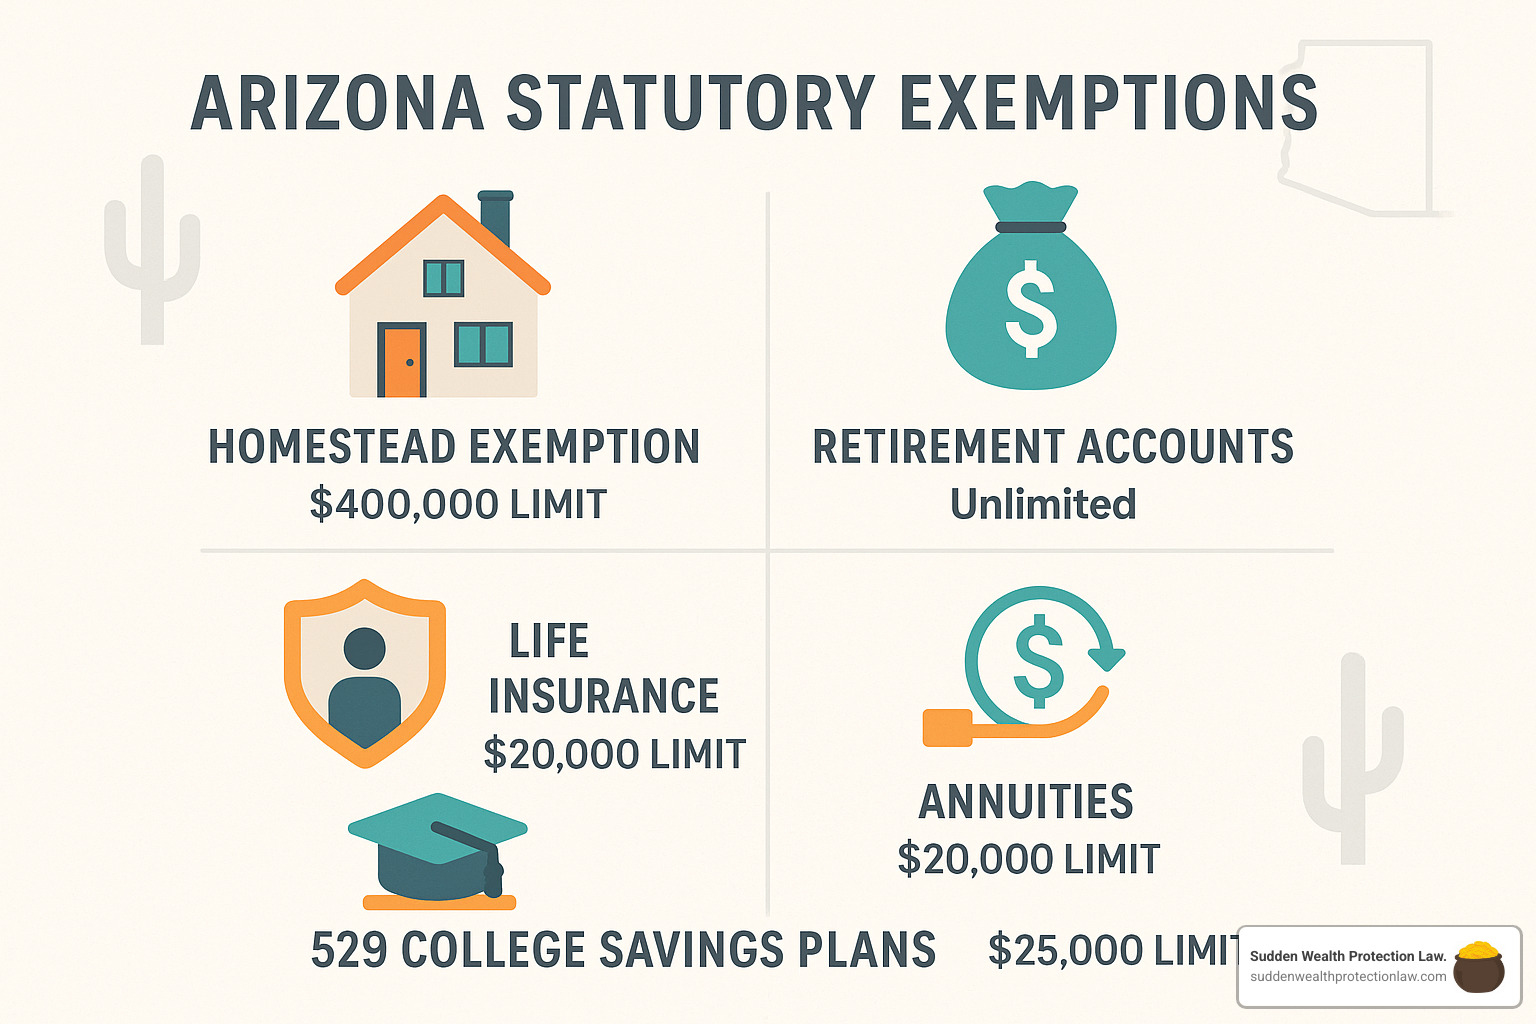
Your home is likely your most protected asset, thanks to Arizona’s generous homestead exemption that shields up to $400,000 of equity in your primary residence (as of 2024, with annual inflation adjustments). This substantial protection means your family home has built-in safeguards against most creditors.
Your retirement nest egg also enjoys special protection. Assets in qualified retirement accounts like 401(k)s and IRAs are generally shielded from creditors, provided they’ve been in the account for at least two years. Similarly, the investment components of life insurance policies and annuities enjoy protection under Arizona law.
If you’re saving for your children’s education, there’s good news there too. Funds in 529 college savings plans are typically protected after a two-year holding period.
As I often tell my clients, “These statutory exemptions form the foundation of any solid Arizona asset protection plan.” Understanding and maximizing these exemptions should be your first step before exploring more advanced strategies like hybrid trusts.
While Arizona may not have specific DAPT legislation, combining these statutory exemptions with a well-designed hybrid trust can provide comprehensive protection for your hard-earned assets. The key is working with an attorney who understands both the limitations and opportunities within Arizona’s unique legal framework.
Latest research on DAPT states
arizona asset protection trusts: Creation, Funding, Benefits & Tax
Setting up an effective asset protection strategy in Arizona isn’t just about creating legal documents—it’s about building a fortress around your family’s financial future. Let’s walk through how to create, fund, and maintain these powerful wealth protection tools.
Requirements for Setting Up a Hybrid Trust
Creating an Arizona asset protection trust using the hybrid approach requires several essential elements to ensure it stands up to legal challenges.
First, you’ll need a qualified independent trustee—someone who isn’t you. This could be a trusted family member, close friend, or professional trustee. The key is that this person must have genuine decision-making power over trust distributions. As I often tell my clients, “Your trustee should be someone who can politely say ‘no’ to you when necessary.”
Your trust document must include strong spendthrift language—legal provisions that prevent beneficiaries from voluntarily or involuntarily transferring their interests in the trust. Think of this as the legal equivalent of super-glue that keeps your assets firmly attached to the trust.
The trust must be irrevocable. Once you create it, you can’t simply change your mind and take everything back. This permanence is precisely what gives the trust its protective power. As one of my clients once joked, “It’s like getting married to financial security—you’re making a commitment!”
Each time you transfer assets into your hybrid trust, Arizona law requires you to sign a solvency affidavit. This document confirms you’re not transferring assets to avoid known creditors or leave yourself financially underwater. This affidavit becomes crucial evidence if someone later claims you made fraudulent transfers.
Finally, consider including trust protector provisions. A trust protector can change trustees, modify administrative provisions, and potentially add you as a beneficiary later. This adds valuable flexibility to your otherwise “set in stone” arrangement.
For more detailed information about trust administration, check out our Trust Administration for Dummies guide.
Who Should Consider arizona asset protection trusts?
Not everyone needs the sophisticated protection of a hybrid trust, but certain individuals should seriously consider this strategy.
If your non-retirement assets exceed $1 million, an Arizona asset protection trust likely makes good financial sense. The cost of setting up and maintaining the trust becomes proportionally smaller as your asset base grows.
Business owners and entrepreneurs face unique risks that make asset protection planning essential. The line between business and personal liability can blur quickly without proper protection. One business owner client told me, “I sleep better knowing my family home is safe, even if my business faces challenges.”
Medical professionals, attorneys, and others in high-liability fields should view asset protection as a natural extension of their professional liability insurance. The trust works as a second line of defense when insurance coverage isn’t enough.
Real estate investors with properties beyond their primary residence can significantly benefit from trust protection. Investment properties often carry liability risks that can be effectively contained within a properly structured trust.
Anyone anticipating potential lawsuits, inheritance disputes, or other legal challenges should be proactive. The best time to build your financial fortress is before there are any signs of trouble on the horizon.
To learn more about our specialized services, visit our Asset Protection Attorney page.
Assets You Can Place in arizona asset protection trusts
Your Arizona asset protection trust can hold a wide variety of assets, giving you flexibility in your protection strategy.
Real estate investments like rental properties, vacation homes, and undeveloped land work particularly well in these trusts. Your primary residence is often better protected by Arizona’s generous homestead exemption, but investment properties benefit tremendously from trust ownership.
Business interests including LLC memberships, corporate shares, and partnership interests can be transferred to your trust. This creates an additional layer of separation between your personal and business assets.
Financial accounts such as brokerage accounts, investment portfolios, and cash reserves can be retitled in the name of your trust. Your trustee will then manage these investments according to the trust’s terms.
Intellectual property—patents, trademarks, copyrights, and royalty rights—can be valuable trust assets, especially for creative professionals and inventors.
Even cryptocurrency and digital assets like Bitcoin can be held in your trust, though this requires specialized knowledge about secure digital asset transfers and storage.
Valuable personal property including art collections, jewelry, antiques, and collectibles can also find protection within your trust. Just remember that these items require proper documentation and valuation.
Funding & Ongoing Administration Best Practices
Creating your trust document is just the beginning—proper funding and administration are what give your Arizona asset protection trust its power.
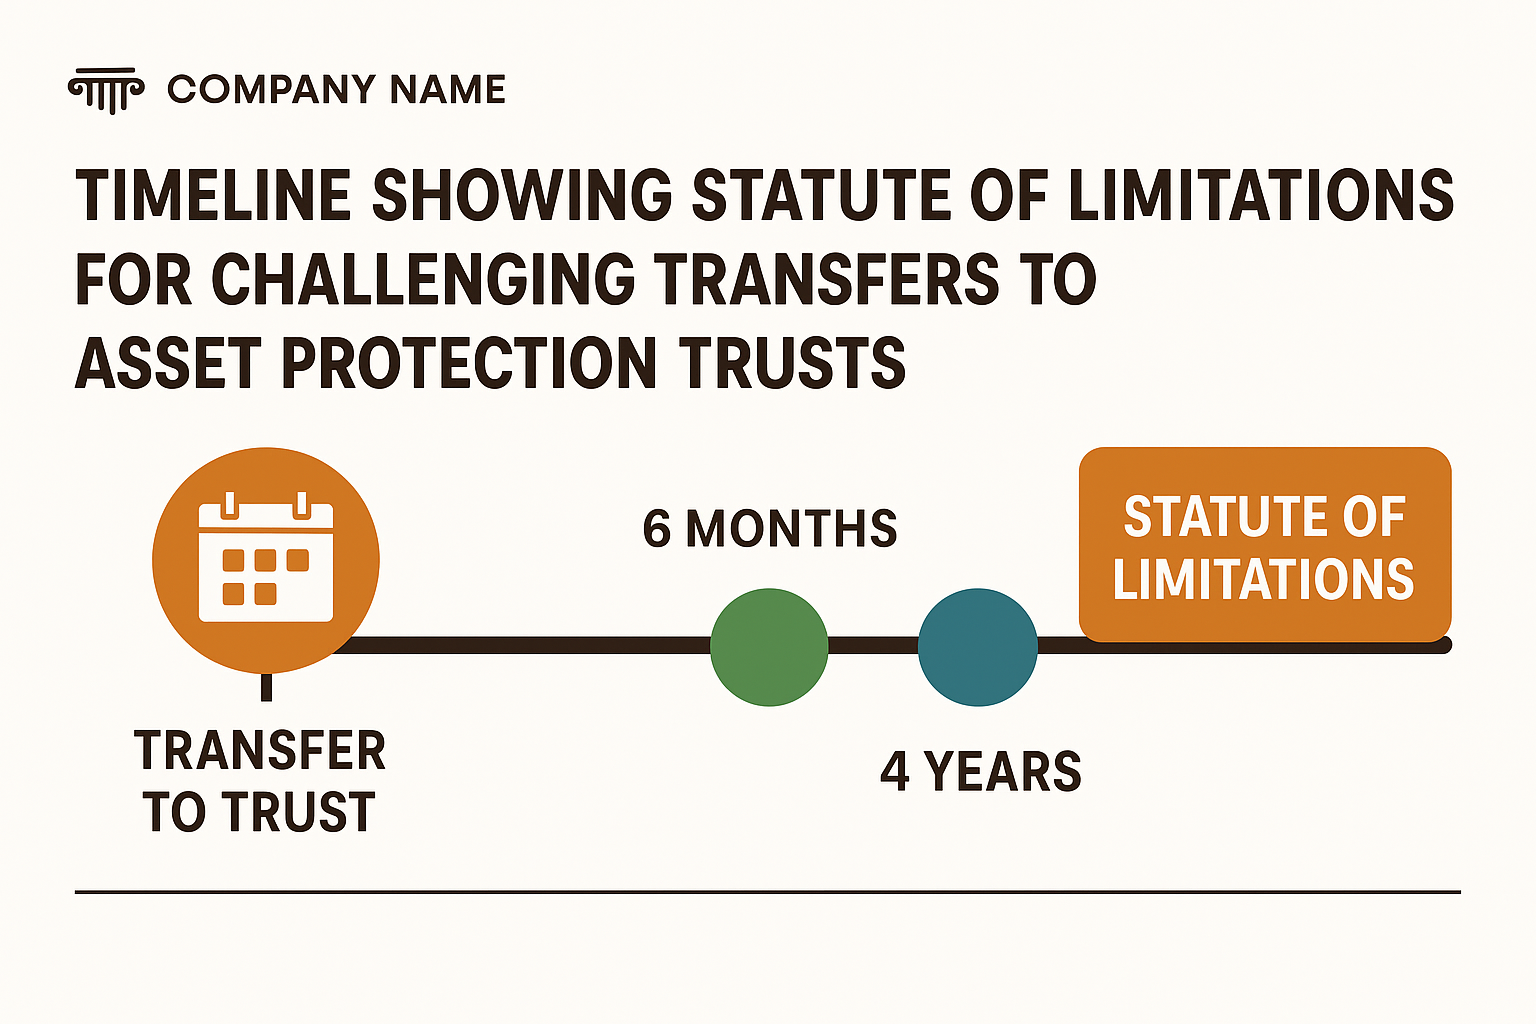
Timing matters tremendously when transferring assets. The ideal time to fund your trust is when skies are clear—no pending lawsuits, no major debts, and no foreseeable creditor problems. Arizona generally allows creditors to look back 4 years for potentially fraudulent transfers, though this period can be reduced to 6 months if you provide formal notice to known creditors.
Keep meticulous records of all transfers to your trust, including signed solvency affidavits for each significant move. These documents become your best defense if anyone later questions your intentions.
Trust formalities aren’t just legal technicalities—they’re the foundation of your protection. Your trustee should administer the trust according to its written terms, maintaining separate accounts and clear records for all trust assets.
Regular documented meetings between you (as grantor) and your trustee help demonstrate that the trust is being properly managed as a legitimate, independent entity rather than your alter ego.
Avoid commingling personal and trust assets at all costs. This separation is crucial for maintaining the trust’s integrity. As one judge famously noted in a case where a trust was invalidated, “If you treat your trust like your personal piggy bank, the court will too.”
For more insights on maintaining irrevocable trusts, see our article on the Advantages of Irrevocable Trust.
Tax Implications & Planning Options
Understanding the tax dimensions of your Arizona asset protection trust is essential for maximizing its benefits.
From an income tax perspective, irrevocable trusts are typically separate taxpayers with compressed tax brackets. However, many hybrid trusts are intentionally structured as “grantor trusts” for income tax purposes. This means you continue paying taxes on trust income even though the assets are protected from creditors. This arrangement can be advantageous—it allows trust assets to grow tax-free and effectively permits tax-free gifts to the trust.
For estate planning, a properly structured hybrid trust can remove assets from your taxable estate, potentially saving significant estate taxes for larger estates. With the federal estate tax exemption at $12.92 million per person (as of 2023), this primarily benefits high-net-worth individuals.
One important consideration involves basis step-up. Assets that remain outside your taxable estate won’t receive a step-up in basis at death, potentially leading to higher capital gains taxes when beneficiaries sell appreciated assets. Some Arizona asset protection trusts include provisions to optimize for either estate tax exclusion or basis step-up, depending on your priorities.
When initially funding your trust, be aware of gift tax implications. These transfers are typically considered completed gifts for tax purposes. You can use your lifetime gift tax exemption or annual exclusion amounts to avoid gift taxes.
As I often tell clients, “You can optimize for income tax advantages by retaining estate inclusion for step-up in basis, or you can optimize for estate tax savings by excluding assets from your taxable estate but forgoing the step-up.” The right choice depends on your overall estate size and tax priorities.
For an expert perspective on asset protection trusts, check out this scientific research on irrevocable trusts from Investopedia.
At Sudden Wealth Protection Law, we specialize in creating customized Arizona asset protection trusts that balance protection, access, and tax efficiency. We understand that each family’s situation is unique, and we craft solutions that protect what matters most to you.
Limitations, Risks & FAQs
While Arizona asset protection trusts offer significant benefits, they also come with limitations and risks that must be understood and managed.
Key Limitations Under Arizona & Federal Law
- Fraudulent Transfer Laws: Arizona’s Uniform Fraudulent Transfer Act (UFTA) allows creditors to void transfers made with intent to hinder, delay, or defraud creditors. As one attorney warned, “A transfer of assets to an Arizona hybrid asset protection trust may not render the trustor insolvent; the trustor must remain solvent after the transfer.”
- Exceptions for Certain Claims: Assets in Arizona asset protection trusts are generally not protected from claims related to:
- Child support or alimony
- Pre-existing creditors (within the statute of limitations)
- Federal tax liens
- Criminal restitution orders
- Bankruptcy Considerations: Federal bankruptcy law includes a 10-year lookback period for transfers to self-settled trusts. This means that assets transferred to a trust within 10 years of filing bankruptcy may be pulled back into the bankruptcy estate.
- Full Faith and Credit Concerns: There’s ongoing legal debate about whether one state must honor another state’s trust laws under the Full Faith and Credit Clause of the U.S. Constitution. This creates some uncertainty when using out-of-state DAPT statutes.
Common Mistakes to Avoid
- Last-Minute Transfers: Attempting to transfer assets after a claim has arisen or is foreseeable will likely be deemed a fraudulent transfer. As one expert noted, “An individual who transfers assets into a DAPT shortly before declaring bankruptcy may have the transfer undone under UFTA.”
- Naming Yourself as Trustee: Serving as your own trustee significantly weakens asset protection. Always use an independent trustee to maintain the separation between you and the trust assets.
- Poor Trustee Selection: Choosing an untrustworthy or inexperienced trustee can lead to mismanagement or breach of fiduciary duty. Select someone who understands their responsibilities and will act in beneficiaries’ best interests.
- Inadequate Documentation: Failing to maintain proper records, including solvency affidavits, can undermine the trust’s effectiveness in court challenges.
- Ignoring Statutory Exemptions: Not taking advantage of Arizona’s statutory exemptions (homestead, retirement accounts, etc.) before implementing more complex strategies.
Frequently Asked Questions
What if I move out of Arizona?
If you move out of Arizona after establishing a hybrid asset protection trust, the trust remains valid as long as it complies with Arizona law. However, your new state of residence might have different rules regarding creditor access to trusts.
A well-drafted trust should include a trust protector provision allowing the trust’s governing law to be changed if beneficial. This provides flexibility if you relocate to a state with more favorable asset protection laws.
As one attorney advised, “It’s always wise to choose a trustee you trust to add you as a beneficiary if Arizona changes its laws or if you move to a state with more favorable trust laws.”
Can creditors pierce a hybrid trust?
Creditors may attempt to challenge a hybrid trust on several grounds:
- Fraudulent Transfer: If you transferred assets with intent to hinder, delay, or defraud a creditor, or became insolvent due to the transfer.
- Alter Ego Theory: If you maintain too much control over the trust or fail to respect trust formalities, a court might determine the trust is merely your “alter ego.”
- Sham Trust: If the trust lacks economic substance or legitimate purpose beyond asset protection.
However, a properly structured and administered hybrid trust with an independent trustee, funded while you were solvent and without known creditor threats, should withstand most challenges.
How long before my assets are safe?
The statute of limitations for a creditor to challenge a transfer to an Arizona hybrid asset protection trust is generally 4 years from the transfer date, but can be as short as 6 months if actual notice is given to known creditors.
For maximum protection, assets should remain in the trust beyond these time periods. As one expert noted, “The statute of limitations for a creditor to challenge a transfer to an Arizona hybrid asset protection trust is generally 4 years, but can be as short as 6 months if actual notice is given.”
For federal bankruptcy purposes, there’s a 10-year lookback period for transfers to self-settled trusts, which may apply to hybrid trusts depending on their structure.
Conclusion
Arizona asset protection trusts offer powerful protection for your hard-earned assets despite the state’s lack of specific DAPT legislation. Through careful planning and implementation of hybrid trust structures, Arizona residents can achieve significant asset protection while maintaining indirect access to their wealth.
The journey through asset protection planning can feel overwhelming at first, but as we’ve seen, there are clear pathways to securing your financial future even in Arizona’s unique legal landscape. The hybrid trust approaches we’ve discussed provide effective shields against potential creditors while still allowing your family to benefit from your hard work.
Timing is everything in asset protection. The best strategies are implemented when skies are clear, not when storm clouds are gathering on the horizon. As I often tell my clients, it’s like installing a home security system—you don’t wait until after a break-in to think about protection.
Arizona asset protection trusts work best as part of a comprehensive approach that includes maximizing statutory exemptions like the substantial $400,000 homestead protection and the strong shields around retirement accounts. These built-in protections form your first line of defense and should be fully used before implementing more sophisticated strategies.
What makes asset protection truly effective is customization. Your family’s situation, goals, and assets are unique—your protection strategy should be too. A business owner with significant real estate holdings needs a different approach than a medical professional concerned about malpractice claims.
At Sudden Wealth Protection Law, we’ve helped hundreds of Arizona families create personalized asset protection plans. Our Asset Vault Trust incorporates special powers of appointment that provide both the flexibility modern families need and the robust protection your assets deserve. This unique approach gives you peace of mind knowing your wealth is secure from potential creditors and lawsuits.
We understand that protecting your assets isn’t just about legal structures—it’s about safeguarding your family’s future and creating a lasting legacy. When clients come to our Phoenix office, they often share not just concerns about potential threats to their wealth, but hopes for how that wealth will support their loved ones for generations to come.
Our compassionate, expert guidance is custom to your unique needs, ensuring favorable outcomes for you and your loved ones. We believe in empowering families not just to protect their wealth, but to use it purposefully to create the impact they desire.
To learn more about how we can help protect your assets and empower your family to be responsible stewards of your wealth, visit our Asset Protection services page or contact our Phoenix office today.
Don’t wait until threats are on the horizon to secure your financial future. The peace of mind that comes from knowing your assets are protected is invaluable—and it’s within your reach today.

