

Why Arizona Families Need Estate Planning That Actually Works
An Arizona revocable living trust is a legal document that lets you transfer ownership of your assets to a trust during your lifetime, avoiding the public probate process when you die. Here’s what every Arizona resident should know:
Key Facts About Arizona Revocable Living Trusts:
• Probate Threshold: Required for estates over $100,000 in real estate or $75,000 in personal property
• Privacy Protection: Trust documents remain private, unlike wills that become public record
• Cost: Setup ranges from $1,500-$8,000 depending on complexity
• Timeline: Avoids Arizona’s minimum 4-month probate process
• Flexibility: Can be changed or revoked anytime while you’re mentally competent
• Tax Status: No impact on your personal taxes during your lifetime
Look, I’ve watched too many Arizona families get blindsided by probate. One day they’re grieving a lost parent, the next they’re sitting in a courthouse waiting room for months while lawyers rack up fees and family secrets get aired in public records.
The brutal truth? Most estate planning disasters are completely preventable. But only if you understand what you’re dealing with before crisis hits.
I’m Paul E. Deloughery, and I’ve spent over 25 years helping Arizona families protect their wealth through proper trust planning—including my own painful $14 million inheritance loss that taught me exactly what goes wrong when families skip the fundamentals. Throughout my practice, I’ve seen how a properly structured Arizona revocable living trust can save families from months of court delays, thousands in legal fees, and the heartbreak of public family disputes.

Simple guide to Arizona revocable living trust terms:
Why Every Arizonan With Assets Should Care
Here’s the stress test that separates smart planning from wishful thinking: If you own a home with more than $100,000 in equity or have personal property worth over $75,000, your family will face Arizona probate court when you die. No exceptions.
I’ve seen families find this the hard way. They assumed their “small” estate would slip through without court involvement, only to learn that their $150,000 Scottsdale condo or their combined bank accounts, vehicles, and retirement savings pushed them over Arizona’s thresholds.
The small estate myths are dangerous. Yes, Arizona allows a streamlined process for estates under $50,000 in personal property, but that’s rare territory in today’s economy. Even modest Arizona households often exceed these limits once you count everything: bank accounts, investment accounts, vehicles, personal belongings, and life insurance payouts.
What Is an Arizona Revocable Living Trust?
Here’s the straight truth about what you’re getting into: An Arizona revocable living trust is essentially a legal contract where you wear three hats at once. You’re the settlor (the person creating and funding the trust), the trustee (the person managing the assets), and the beneficiary (the person enjoying the benefits). Think of it as setting up a company where you’re the CEO, the board of directors, and the sole shareholder all rolled into one.
The Arizona Trust Code (ARS §§14-10101 through 14-11102) governs how these trusts work in our state. But don’t let the legal code numbers scare you—the concept is straightforward. You’re creating a legal container that holds your assets while you’re alive, and when you die or become incapacitated, someone you’ve chosen takes over seamlessly.
The beauty of the revocable part? You maintain complete control. Want to sell your house? Go ahead. Need to change beneficiaries after a family falling-out? No problem. Want to cancel the whole thing and go back to simple ownership? Your choice. The IRS treats it as a “grantor trust,” which means all the income and deductions flow straight through to your personal tax return. No extra paperwork, no separate tax filings.
Here’s how an Arizona revocable living trust stacks up against your other options:
| Feature | Revocable Trust | Will Only | No Planning |
|---|---|---|---|
| Probate Required | No | Yes | Yes |
| Privacy | Private | Public Record | Public Record |
| Timeline | Immediate | 4+ months | 6-18 months |
| Incapacity Planning | Built-in | Requires separate POA | Court conservatorship |
| Cost to Create | $1,500-$8,000 | $500-$2,000 | $0 |
| Cost at Death | Minimal | $4,000-$8,000+ | $6,000-$15,000+ |
The numbers tell the story. Yes, you’ll pay more upfront for a trust, but your family saves thousands later when it actually matters.
More info about Trust vs Will vs Probate
Core Players Inside the Trust Contract
Let’s talk about the trustee role, because this is where families either succeed brilliantly or crash spectacularly. Under Arizona law, being a trustee isn’t just a title—it’s accepting what lawyers call a fiduciary duty. That’s the highest standard of care our legal system recognizes.
What does fiduciary duty actually mean? Your trustee must act solely in the beneficiaries’ best interests, avoid any conflicts of interest, and manage assets with the skill of a prudent investor. No playing favorites among your kids. No “borrowing” trust money for personal emergencies. No making risky investments with your family’s inheritance.
When you become incapacitated, the Arizona Trust Code provides clear protocols for transition. If your trust document specifies how to determine incapacity—usually through medical certification or court determination—your successor trustee can step in immediately. No waiting for court-appointed conservatorship. No family members fighting over who’s in charge.
I’ve watched families choose successor trustees based on hurt feelings rather than competence. Your oldest child might deserve recognition, but if they can’t balance their own checkbook, they shouldn’t be managing your life’s work. Choose someone who combines financial competence with unshakeable integrity.
How an Arizona Revocable Living Trust Avoids Probate
Arizona follows the Uniform Probate Code, which sounds efficient until you’re actually stuck in it. Even our state’s “simplified” probate process takes at least four months and requires court filings, creditor notices, and judicial oversight. Every financial detail of your family’s life becomes public record, accessible to anyone curious enough to look.
A properly funded Arizona revocable living trust sidesteps this courthouse drama entirely. Since the trust—not you personally—owns the assets, there’s literally nothing for probate court to handle. Your successor trustee can access bank accounts, sell real estate, and distribute inheritances immediately after your death.
This strategy also solves what I call the ancillary probate nightmare. If you own property in multiple states—maybe a vacation home in California or rental property in Colorado—each state typically requires separate probate proceedings. A trust holding all your real estate avoids this multi-state legal circus entirely.
Arizona also allows transfer-on-death deeds for real estate, but these create their own complications. A trust provides much cleaner ownership transfer and better protection if you become incapacitated.
Key Benefits and Drawbacks
Let’s cut through the marketing fluff and examine what an Arizona revocable living trust actually delivers—and where it falls short.
The Real Benefits:
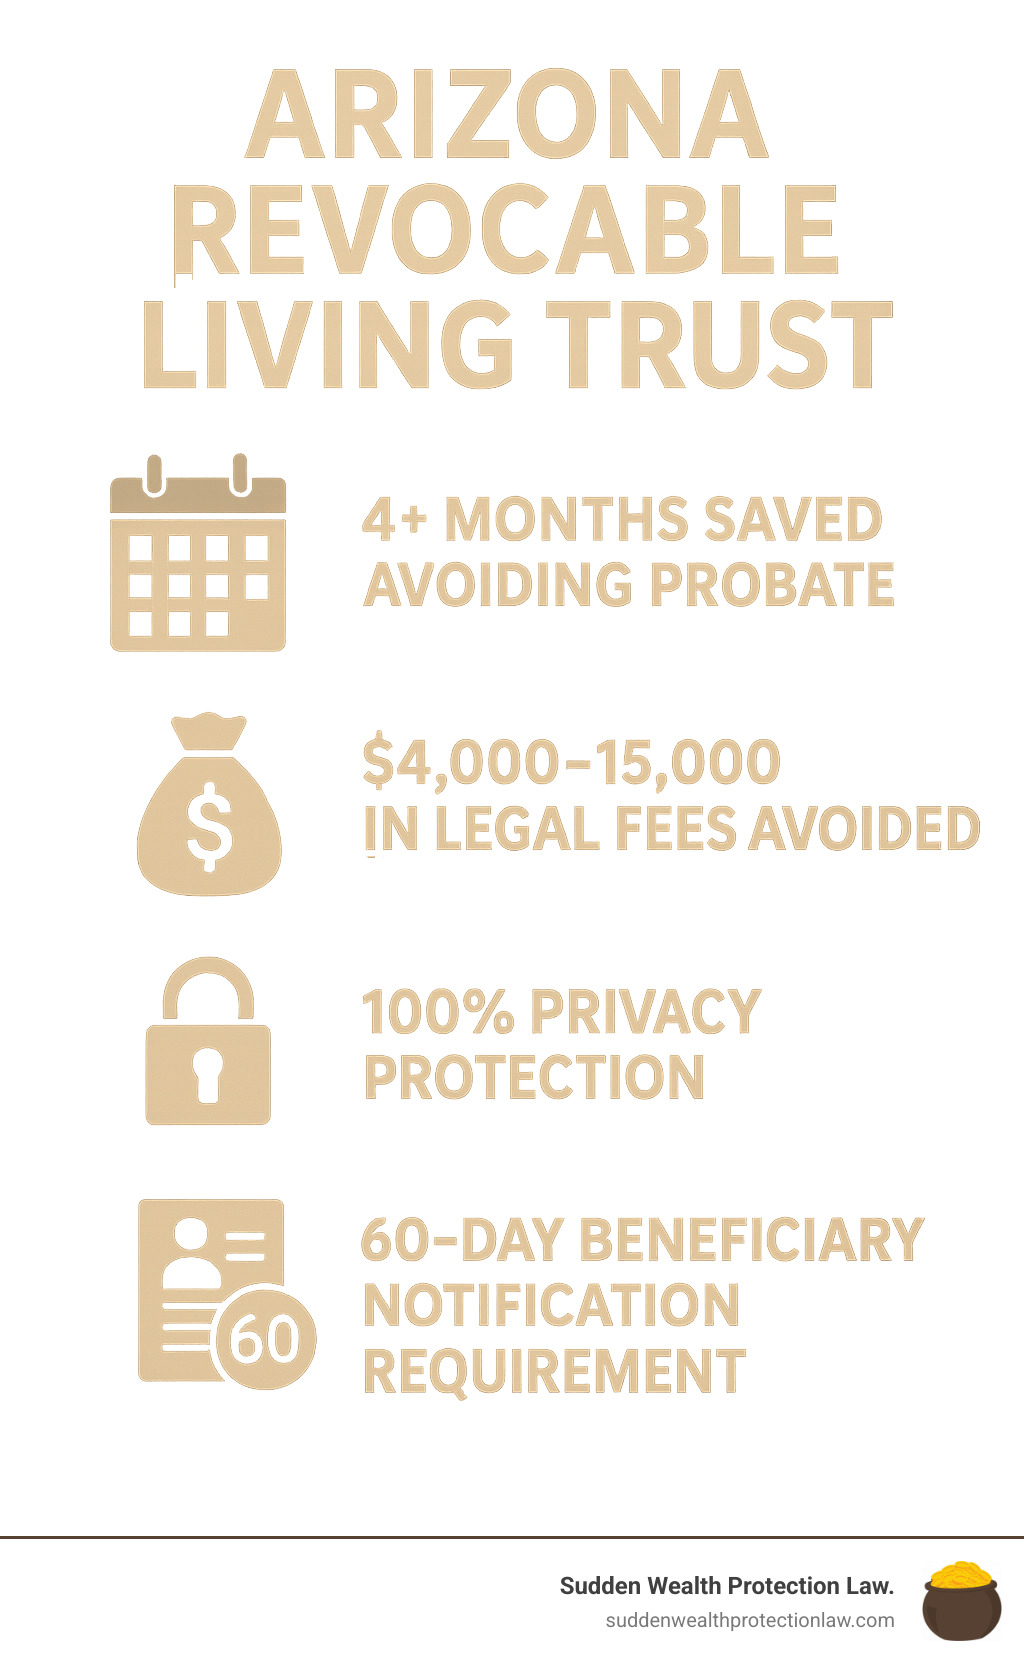
Probate avoidance means your family skips the courthouse entirely. No waiting for court dates, no public filing requirements, no judicial supervision of asset distribution. In Arizona, this typically saves 4-18 months and $4,000-$15,000 in legal fees and court costs.
Privacy protection keeps your family’s business private. While probated wills become public record—including asset lists, beneficiary names, and family disputes—trust documents remain confidential. Only trustees and beneficiaries see the details.
Incapacity planning provides seamless transition if you become unable to manage your affairs. Your successor trustee can pay bills, manage investments, and handle financial decisions without court involvement. Compare this to conservatorship proceedings, which can cost $4,000-$6,000 just to get started.
Faster distributions let your family access inheritance money immediately instead of waiting months for probate completion. This matters when families need funds for mortgages, medical bills, or children’s education.
The Honest Drawbacks:
Upfront costs run $1,500-$8,000 for trust creation, compared to $500-$2,000 for a simple will. Complex estates with multiple properties or business interests push toward the higher end.
No creditor protection during your lifetime. Since you control the trust completely, creditors can reach trust assets just as easily as personally-owned assets. If you need protection from your own potential lawsuits or creditor claims, you’d need an irrevocable Asset Vault Trust instead.
Ongoing maintenance requires attention. You must retitle assets into the trust name and update beneficiary designations. Forget to fund the trust properly, and you’ve created an expensive paperweight.
Arizona has no state estate tax, but federal estate tax applies to estates exceeding $13.61 million per person in 2024. For most Arizona families, estate tax planning isn’t the primary concern—probate avoidance and privacy protection drive the decision.

More info about Revocable Trust vs Irrevocable Trust
How an Arizona Revocable Living Trust Protects You While Alive
The incapacity protection alone justifies trust planning for many families. When you can’t manage your own affairs—whether from stroke, dementia, or serious accident—your successor trustee steps in immediately with full authority to handle financial matters.
Without a trust, your family faces conservatorship court. This means filing petitions, attending hearings, posting bonds, and submitting annual reports to a judge. The court-appointed conservator might not be who you’d choose, and the process costs thousands before it even begins.
Your trust works in harmony with healthcare powers of attorney and living wills. While those documents handle medical decisions, your successor trustee manages the financial side—paying for care, accessing insurance benefits, and maintaining your household.
When a Simple Will (or Small-Estate Affidavit) Might Suffice
Not every Arizona resident needs a trust. If your total estate falls under $50,000 in personal property (excluding real estate), Arizona’s small-estate affidavit process might work. Your family can collect assets with a simple sworn statement instead of formal probate.
But here’s the catch: this threshold applies only to personal property. Own any real estate, and you’re back in probate court regardless of value. Even a $75,000 mobile home or vacant lot triggers full probate proceedings.
The DIY trap catches many families. Online will-makers and form documents seem cost-effective until you find they don’t address Arizona-specific requirements, funding procedures, or incapacity planning. I’ve seen too many families learn this lesson the expensive way.
Creating and Funding Your Arizona Revocable Living Trust
Creating an Arizona revocable living trust feels like building a house—you need both a solid foundation and the actual structure. The foundation is your trust document; the structure is funding it with your assets. Mess up either part, and the whole thing collapses when your family needs it most.
I’ve watched families spend thousands on beautifully crafted trust documents, only to leave them sitting in a file cabinet while their assets remained in personal names. When Dad died, guess what? Everything went through probate anyway because nobody ever bothered to actually transfer ownership to the trust.
The drafting process starts with understanding Arizona Trust Code requirements. Your trust document needs proper execution—that means your signature gets notarized, not just witnessed like some states allow. The document must clearly identify who’s serving as trustee initially and who takes over when you can’t serve anymore.
Think of your trust as covering three distinct chapters of your life story. Chapter One handles everything while you’re healthy and making your own decisions. Chapter Two kicks in if you become incapacitated and can’t manage affairs yourself. Chapter Three governs what happens after you die. Each chapter needs different rules and different trustee powers.
You’ll also need what’s called a pour-over will—think of it as your safety net. This backup document catches any assets you forgot to transfer into the trust and pours them in after you die. Those forgotten assets still go through probate first, but at least they end up where you intended.
The funding phase is where most people stumble. Funding means changing legal ownership from “John Smith” to “John Smith, Trustee of the John Smith Revocable Trust dated March 15, 2024.” It sounds simple, but every asset type has different requirements.
Real estate transfers require new deeds recorded with county offices. Bank accounts need retitling or beneficiary designation changes. Investment accounts might transfer directly into the trust name or simply name the trust as beneficiary. Each financial institution has its own paperwork and procedures.
Here’s something that confuses people: your trust doesn’t need its own tax identification number while you’re alive and competent. You keep using your Social Security number for all tax reporting. The trust only gets its own tax ID after you die or become incapacitated.
More info about How to Create a Living Trust in Arizona
Funding Checklist: What Goes In, What Stays Out
The funding decision isn’t always obvious. Some assets work better inside the trust, others function better with beneficiary designations, and a few create more problems than they solve.
Your home and any rental properties absolutely must go into the trust. Real estate is what triggers Arizona’s probate requirements, and it’s also what creates the biggest headaches for families. I’ve seen simple real estate transfers take six months in probate court when they could have been handled in six days with a properly funded trust.
Bank accounts and investment accounts should generally transfer into the trust name. This gives your successor trustee immediate access to pay bills and manage investments if you become incapacitated. Some families prefer keeping one small checking account in personal names for daily expenses, which works fine as long as it stays under Arizona’s small estate thresholds.
Business interests get tricky. If you own part of a partnership or LLC, check the operating agreement first. Some partnerships require member consent before you can transfer your interest to a trust. Professional practices might have licensing restrictions that complicate trust ownership.
Retirement accounts like IRAs and 401(k)s should stay in your personal name but name the trust as beneficiary. Direct ownership by the trust eliminates the “stretch” provisions that let beneficiaries take distributions over their lifetimes. Better to maintain the tax advantages and use beneficiary designations.
Life insurance policies work similarly—keep them in your personal name but designate the trust as beneficiary. This gives your trustee control over how insurance proceeds get distributed without creating unnecessary tax complications.
Vehicles present an interesting choice in Arizona. You can transfer them into the trust, or you can use Arizona’s transfer-on-death vehicle registration. For most families, the transfer-on-death option is simpler and accomplishes the same goal.
Common Funding Mistakes That Trigger Probate
The most expensive mistake I see? Forgotten accounts that slip through the cracks. You transfer your main checking account but forget about that old savings account at the credit union, the money market fund from your previous job, or the CD that auto-renewed last year. Each unfunded account becomes a probate asset that defeats your entire plan.
Unrecorded deeds create their own special nightmare. Some families prepare the paperwork to transfer real estate into the trust but never actually record the deeds with the county recorder’s office. An unrecorded deed provides zero legal protection. When you die, the property still shows in your personal name, which means probate court.
I’ve seen this happen with families who thought they were saving the $30 recording fee. That “savings” cost their heirs $8,000 in probate attorney fees and eight months of court delays.
Out-of-state property gets overlooked constantly. That vacation cabin in Colorado or rental property in Texas needs separate deed transfers following those states’ requirements. Miss one property, and your family faces multiple probate proceedings in multiple states—exactly what the trust was supposed to prevent.
The funding deadlines matter too. Some families create the trust but procrastinate on funding, thinking they’ll “get around to it eventually.” Estate planning procrastination has a way of becoming permanent when health crises hit unexpectedly.
Managing, Amending, and Terminating the Trust
Life changes, and your Arizona revocable living trust needs to change with it. Whether you’re welcoming new grandchildren, dealing with a divorce, or simply rethinking your distribution plans, Arizona Revised Statute §14-10602 gives you several ways to modify or completely revoke your trust.
The beauty of a revocable trust lies in its flexibility. Unlike irrevocable trusts that lock you into permanent arrangements, you can adjust your Arizona revocable living trust whenever circumstances change—as long as you’re mentally competent.
Arizona law recognizes multiple amendment methods. You can follow the specific procedures outlined in your original trust document, execute a formal written amendment with the same notarization requirements as the original, or even reference trust changes in a will or codicil (though this creates unnecessary probate complications). The courts will also accept any signed writing that shows “clear and convincing” intent to modify the trust, giving you flexibility when life doesn’t follow perfect legal procedures.
Community property considerations add complexity for married couples. If you used community property to fund your trust, Arizona law treats each spouse as having contributed their half. This means each spouse can potentially revoke their portion of community property contributions, but significant amendments affecting both spouses typically require joint action to avoid legal complications.
Trustee notice requirements become crucial when you decide to revoke your trust entirely. Your trustees must deliver trust property promptly according to your directions. If you become incapacitated, only someone with specific authority under your power of attorney can exercise your revocation rights on your behalf. Court-appointed conservators need judicial approval before modifying or revoking your trust.
Latest research on Arizona Trust Code
More info about Trustee Versus Trustor
Changing Your Arizona Revocable Living Trust
Arizona courts apply a “substantial compliance” standard when evaluating trust amendments. This means you don’t need perfect adherence to every procedural detail outlined in your trust document. The courts look for clear evidence of your intent to change the trust, even if you didn’t follow the exact amendment steps.
But here’s where families get into trouble: sloppy amendments create expensive problems. I’ve seen handwritten notes in margins, unclear language that contradicts earlier provisions, and conflicting instructions that leave beneficiaries fighting in court—exactly the outcome you wanted to avoid by creating a trust in the first place.
For significant changes, consider a complete restatement rather than layering multiple amendments on top of each other. A restated trust incorporates all your changes into a clean, new document while maintaining the original trust’s legal existence and funding. This approach eliminates confusion and reduces the chance of conflicting provisions.
Clear and convincing intent becomes the legal standard when your amendment methods don’t perfectly match your trust’s requirements. Arizona courts will honor changes that clearly express your wishes, but ambiguous language or questionable circumstances can trigger expensive litigation among your beneficiaries.
Trustee’s Playbook After the Settlor Dies
When you die, your revocable trust transforms into an irrevocable arrangement automatically. Your successor trustee suddenly faces serious legal responsibilities under Arizona law, and mistakes during this transition can create lasting problems for your beneficiaries.
The 90-day inventory rule doesn’t technically apply to trusts like it does in probate court, but smart trustees complete comprehensive asset inventories within this timeframe anyway. This establishes baseline values for tax purposes and creates a clear record for beneficiaries who want to understand what they’re inheriting.
Your trust needs its own tax identification number once you’re gone, and depending on the types of assets and distribution timing, it may require separate income tax returns. This isn’t optional—the IRS expects compliance, and penalties for missed filings can eat into your beneficiaries’ inheritance.
Beneficiary notice requirements under Arizona law give your successor trustee 60 days to notify all beneficiaries of their appointment and provide contact information. Annual accounting reports keep everyone informed about trust activity, reducing suspicion and potential disputes. Transparency prevents most family conflicts before they start.
The creditor protection window works differently for trusts than for probated estates. Unlike probate’s formal creditor notice period that cuts off claims after a specific deadline, trusts don’t automatically eliminate creditor claims. However, Arizona’s general statute of limitations still applies to most claims, eventually providing protection for trust assets.
Your successor trustee’s delivery of property obligations begin immediately upon your death. They must follow your written distribution instructions while managing ongoing trust expenses like property taxes, insurance, and maintenance costs. Balancing these competing demands requires both financial skill and clear communication with beneficiaries who may be eager to receive their inheritance.
Frequently Asked Questions about Arizona Revocable Living Trusts
The questions I hear most often about Arizona revocable living trusts usually come from families who’ve been burned by bad information online or scared by horror stories from neighbors. Let me set the record straight on the issues that actually matter.
Does a trust become public record in Arizona?
Here’s one of the biggest advantages of trust planning: your family’s financial details stay private forever. While wills become public record the moment they hit probate court—meaning anyone can walk into the courthouse and read about your assets, beneficiaries, and family dynamics—trust documents remain completely confidential.
Only trustees and beneficiaries have legal rights to see the full trust terms. That nosy neighbor, your ex-spouse, or potential scammers targeting your family? They get nothing.
For practical matters like real estate transactions or bank account management, Arizona allows you to use a certificate of trust instead of the full document. This one-page summary proves the trust exists and confirms trustee authority without revealing beneficiary names, distribution amounts, or your family’s private instructions.
I’ve seen families appreciate this privacy protection years later when they realize how much personal information becomes public through probate court. Everything from asset values to family disputes gets documented in court files that anyone can access.
Do I still need a will if I have a trust?
Absolutely yes, and here’s why: even the most carefully planned Arizona revocable living trust needs a pour-over will as backup protection. Think of it as your safety net for anything that slips through the cracks.
Life happens. You might forget to retitle that new bank account, inherit assets unexpectedly, or acquire property right before you die. The pour-over will catches these “orphaned” assets and directs them into your trust after probate. Without this backup, those assets get distributed according to Arizona’s intestacy laws—probably not what you intended.
The pour-over will also handles something trusts cannot: appointing guardians for minor children. If you have kids under 18, you need a will to name who should raise them if both parents die. This decision is too important to leave to court proceedings.
Your pour-over will should be relatively simple since ideally it won’t control significant assets. Its main job is cleanup duty and ensuring nothing important gets overlooked in your planning.
What happens if I lose the original trust document?
Don’t panic—this isn’t the disaster many people fear. Arizona law recognizes that copies can be legally valid if you can prove the original document’s contents and proper execution. Your attorney should maintain copies, and smart planning means keeping copies in multiple secure locations.
Your successor trustee can usually operate with certified copies, especially if they have supporting documentation like funding records and correspondence that references the trust terms. Banks, title companies, and other institutions typically accept proper copies for routine transactions.
However, if problems arise or someone challenges the trust’s validity, trustees might need to petition the court to establish the trust’s terms based on available evidence. This creates exactly the court involvement you wanted to avoid with trust planning.
The lesson? Treat your trust document like any other valuable asset. Keep the original in a fireproof safe or safety deposit box, give copies to your successor trustee, and make sure your family knows where to find everything when needed.
Conclusion and Next Steps
Here’s the bottom line: an Arizona revocable living trust won’t solve every family problem, but it prevents the most predictable and expensive ones. When your family is grieving, the last thing they need is months of courthouse visits, public records exposing their private business, and legal bills that eat into their inheritance.
I’ve watched this scenario play out hundreds of times. The families who planned ahead—who took the time to create and properly fund their trust—handle transitions smoothly. Their loved ones access money immediately, settle affairs privately, and focus on healing instead of legal procedures.
The families who didn’t plan? They learn about Arizona’s probate requirements the hard way, usually while sitting in a lawyer’s office six months after the funeral, wondering why everything takes so long and costs so much.
The peace-of-mind factor extends beyond dollars and timelines. Knowing your successor trustee can step in seamlessly if you become incapacitated means you’ll never burden your family with conservatorship court. Knowing your assets will transfer privately means your family’s financial details won’t become public entertainment.
But here’s where good intentions meet harsh reality: a single overlooked detail can solve years of careful planning. That forgotten savings account, that unrecorded deed, that business interest you meant to transfer but never did—each creates a probate asset that drags your family back to court anyway.
At Sudden Wealth Protection Law, we’ve seen every funding mistake and every family dynamic that complicates trust planning. Our approach focuses on getting both the legal structure and the practical details right from the start. We don’t just draft documents—we make sure your trust actually works when your family needs it most.
Your Arizona estate planning needs are unique to your family, your assets, and your concerns. Whether you own multiple properties, run a family business, or simply want to spare your children from probate hassles, the right trust strategy makes all the difference.
Ready to give your family the gift of avoiding probate court drama? Let’s discuss how an Arizona revocable living trust fits into a comprehensive plan that protects both your assets and your family’s peace of mind.
More info about Estate Planning services
Schedule your consultation today and find how proper trust planning can save your family months of delays, thousands in fees, and the stress of public court proceedings when they’re already dealing with loss.

