

Why Asset Protection Concepts and Strategies for Protecting Your Wealth Matter More Than Ever
Asset protection concepts and strategies for protecting your wealth aren’t just for billionaires hiding money in Swiss banks. They’re for anyone who’s worked their tail off to build something worth taking—and trust me, there are plenty of folks out there eager to take it.
Core Asset Protection Strategies:
- Legal Entities: LLCs, corporations, and family limited partnerships to separate liabilities
- Trust Structures: Irrevocable trusts, Asset Vault Trusts, and offshore options for creditor protection
- Insurance Layers: Liability and umbrella coverage as your first line of defense
- Property Titling: Strategic ownership structures like tenants by entirety
- Statutory Exemptions: Homestead, retirement accounts, and state-specific protections
- Timing: Implementing protection before threats arise (fraudulent transfer laws make post-lawsuit planning risky)
Here’s the brutal truth: millions of lawsuits get filed every year in the U.S., and Arizona isn’t immune. One slip-and-fall at your rental property, one angry business partner, or one messy divorce can wipe out decades of hard work faster than you can say “garnishment order.”
The good news? There are legal ways to make your assets harder to reach than a bottle of top-shelf whiskey at a church picnic. But like any good defense strategy, it takes planning, proper execution, and knowing which tools work best for your situation.
I’m Paul E. Deloughery, and I’ve spent over 25 years helping Arizona families protect what they’ve built—often after watching others lose everything because they waited too long to act. My expertise in asset protection concepts and strategies for protecting your wealth comes from both professional experience and personal pain: I inherited $14 million in 2009 and lost most of it, which taught me exactly what not to do when sudden wealth hits.
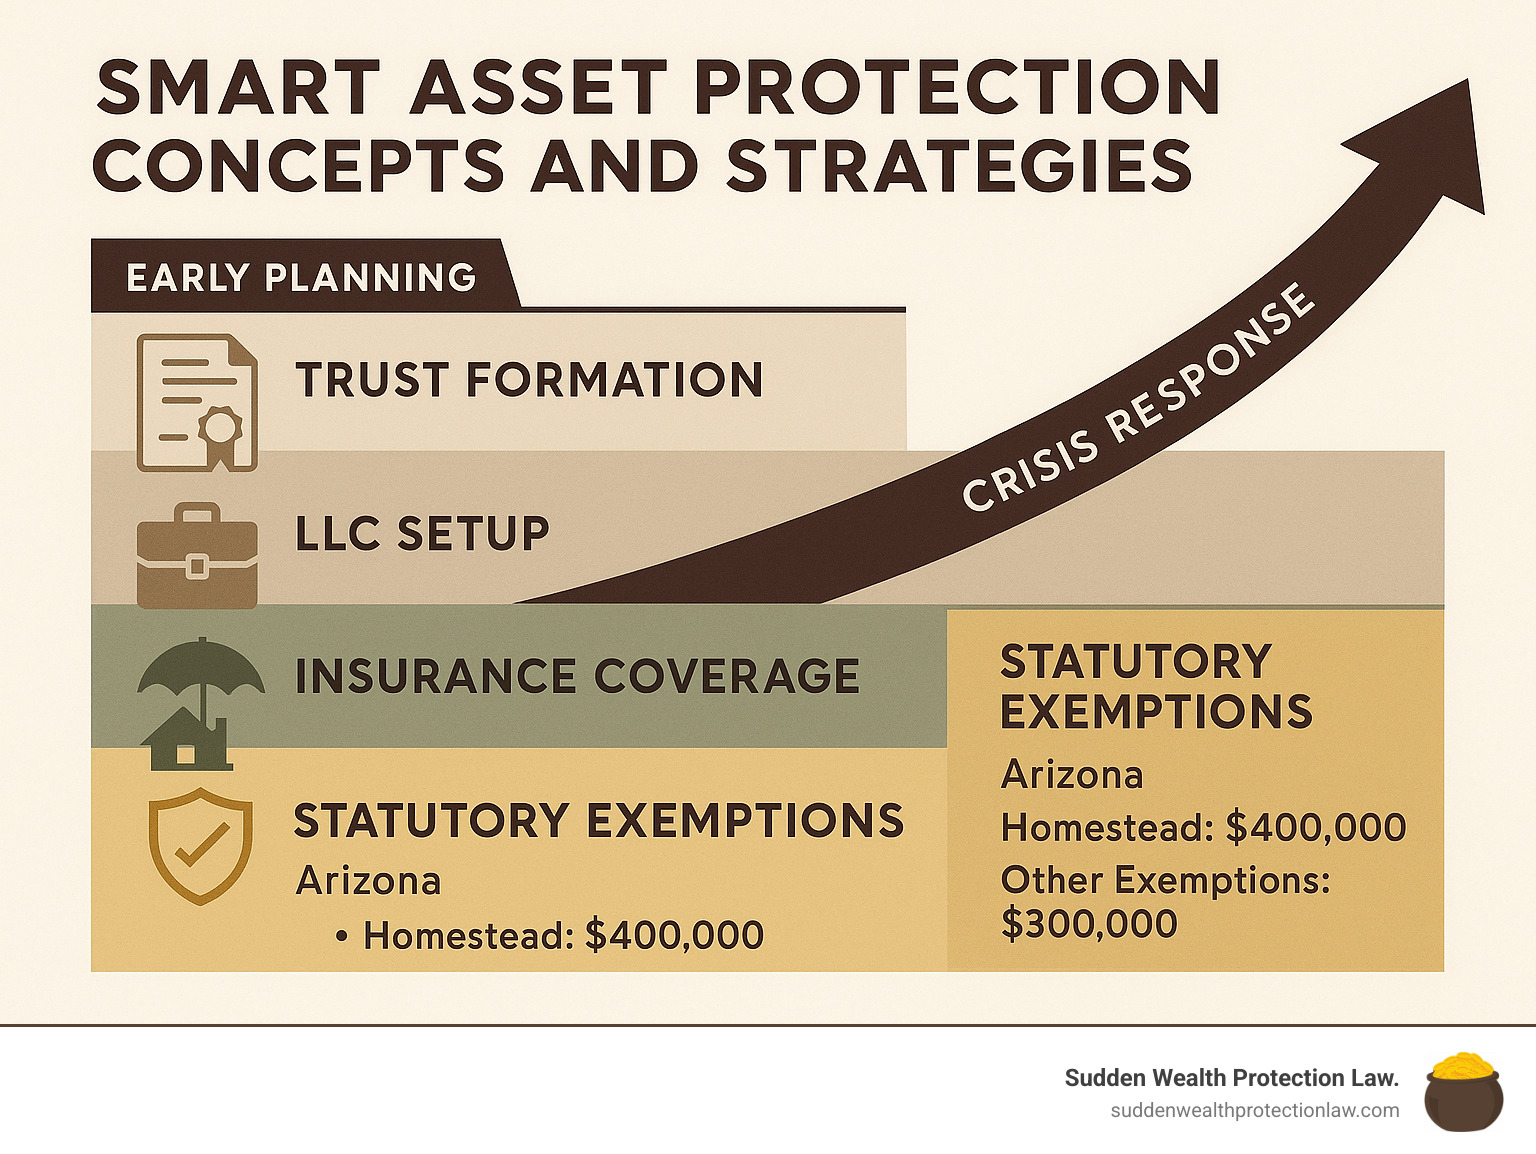
Simple asset protection concepts and strategies for protecting your wealth word guide:
- divorce asset protection strategies
- tax strategies and asset protection
- how does a person protect against monetary destruction
Asset Protection Concepts and Strategies for Protecting Your Wealth
Picture this: you’ve spent thirty years building your nest egg, only to watch it disappear faster than free beer at a tailgate party because someone slipped on your sidewalk. That’s not paranoia talking—that’s reality in today’s lawsuit-happy world.
Asset protection concepts and strategies for protecting your wealth are your legal armor against creditors, plaintiffs, and anyone else looking to separate you from your hard-earned money. Think of it like building a fortress around your assets—not to hide them from Uncle Sam (that’s illegal), but to make them legally untouchable when trouble comes knocking.
The beauty of proper asset protection lies in creditor psychology. Most attorneys and their clients want easy money. When they find your assets are locked up tighter than Fort Knox, they’ll usually move on to softer targets. It’s the legal equivalent of having a mean-looking dog in your yard—burglars tend to skip houses where the risk outweighs the reward.
Here’s what scares the hell out of me: too many good people think they’re bulletproof because they carry insurance or because “I’m careful and don’t do anything wrong.” That’s like saying you don’t need a seatbelt because you’re a safe driver. Accidents happen, and in our litigious society, even Mother Teresa would’ve needed asset protection.
The clock is always ticking when it comes to protection planning. Courts can void asset transfers under Arizona’s fraudulent transfer laws if you wait until creditors are circling. The best time to build your financial fortress is when skies are clear, not when the storm’s already hitting.
Why It’s More Dangerous to Look Rich Than to Be Rich
Here’s a truth that’ll make your head spin: flaunting your wealth is like wearing a “Sue Me” sign around your neck. The flashier you look, the bigger the target you become for every slip-and-fall artist and opportunistic attorney in town.
Smart money stays quiet. That means keeping your mouth shut about investment returns at dinner parties, avoiding social media posts about your new Tesla, and definitely not bragging about your real estate portfolio to the neighbor whose kid just got hurt on your property.
Privacy isn’t just good manners—it’s smart asset protection concepts and strategies for protecting your wealth. Using a land trust to hold your vacation home or setting up proper entity structures makes your assets less obvious and less attractive to potential plaintiffs. When they can’t easily see what you own, they’re less likely to come after it.
The goal isn’t to hide assets illegally—that’s a one-way ticket to federal prison. It’s about making your wealth less visible and harder to reach through legitimate legal structures.
The High-Risk Profiles Who Need Asset Protection Concepts and Strategies for Protecting Your Wealth
Some folks walk around with bigger targets painted on their backs than others. If you fit any of these profiles, asset protection concepts and strategies for protecting your wealth aren’t a luxury—they’re as essential as oxygen.
Medical professionals face the biggest bulls-eyes. Doctors, dentists, and healthcare providers deal with multimillion-dollar malpractice exposure daily. Even with malpractice insurance, gaps in coverage or excluded claims can wipe out personal assets faster than you can say “medical negligence.”
Real estate investors are sitting ducks. Every rental property is a potential lawsuit factory. Slip-and-falls, lead paint claims, discrimination allegations, habitability issues—the ways tenants can sue landlords would fill a phone book. One bad tenant with a good lawyer can cost you everything.
Business owners live in a legal minefield. Employee lawsuits, customer claims, vendor disputes, partnership blowups—owning a business means wearing a target every day. Personal guarantees on business loans make it even worse, turning business debts into personal nightmares.
Inheritance recipients suddenly find themselves in the crosshairs when significant wealth enters the picture. Family disputes get nastier, divorce risks increase, and creditor claims multiply. Sudden wealth brings sudden exposure that most people aren’t prepared for.
High-net-worth individuals become irresistible to contingency-fee attorneys. The bigger your net worth, the more attractive you become to plaintiffs looking for deep pockets. It’s simple math: bigger assets equal bigger potential paydays for lawyers willing to roll the dice on questionable claims.
Legal Tools That Take the Hit Instead of You
When creditors come knocking, you want something standing between them and your hard-earned wealth. The best asset protection concepts and strategies for protecting your wealth work like a good bodyguard—they take the punch so you don’t have to.
Think of it this way: if someone wants to sue you for your house, but you don’t technically own the house (because it’s owned by a trust or LLC), they’re suddenly chasing shadows. These legal entities become the target instead of you personally.
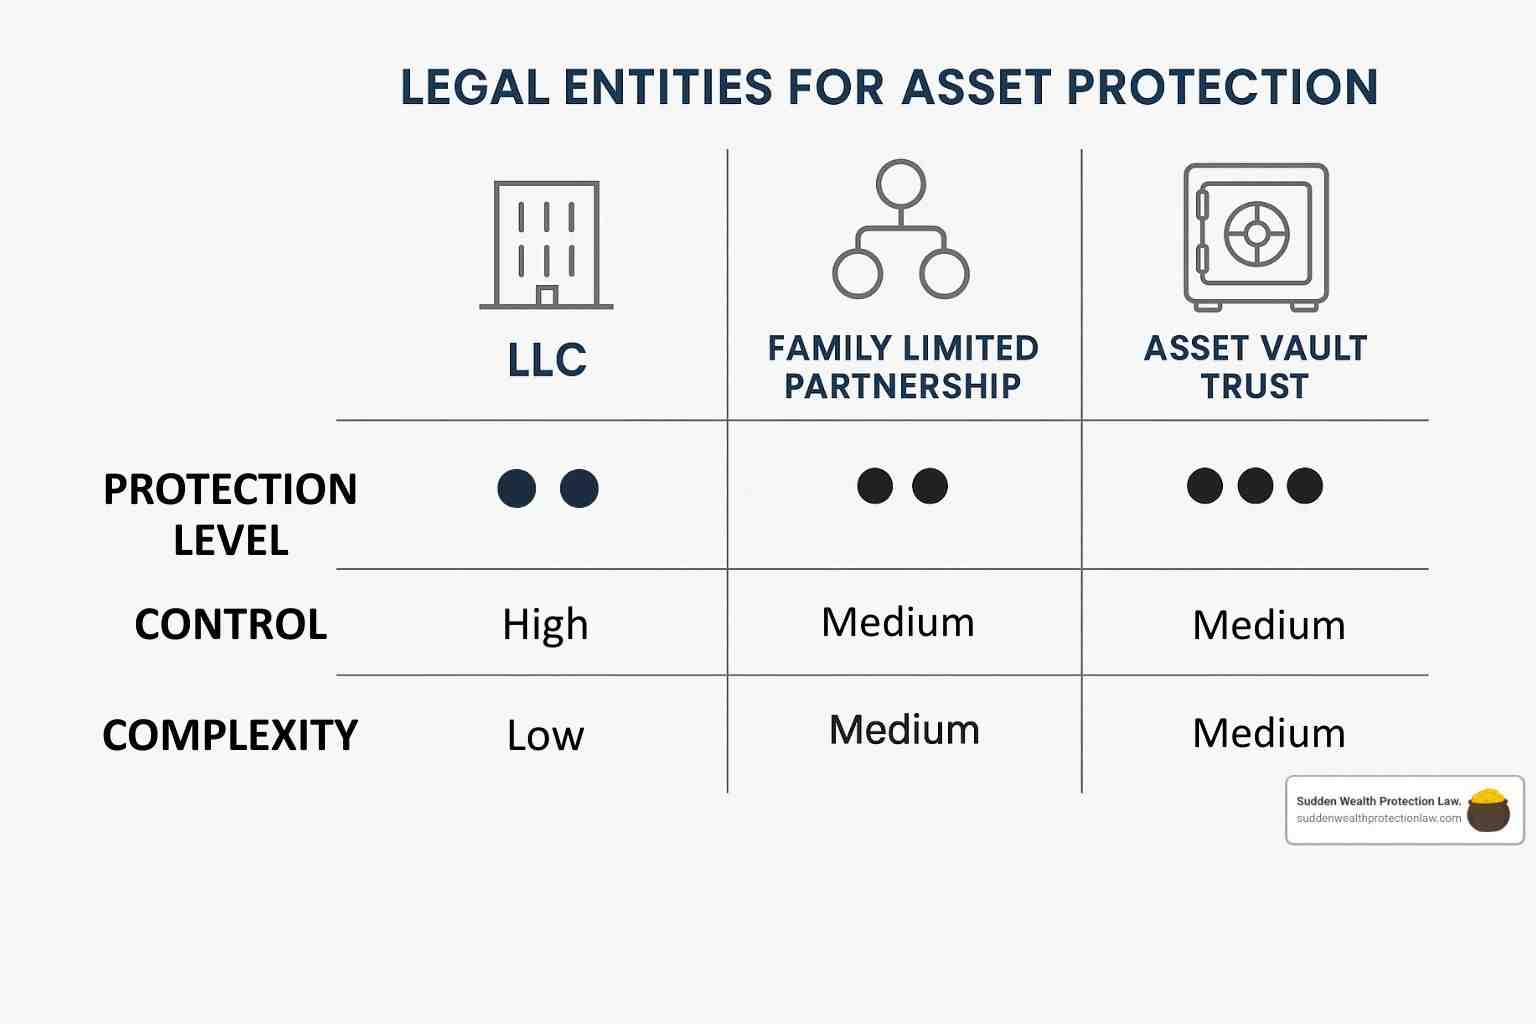
| Protection Tool | Asset Protection Level | Control Retained | Complexity | Best For |
|---|---|---|---|---|
| LLC | Good | High | Low | Business assets, real estate |
| Family Limited Partnership | Good | Medium | Medium | Family wealth transfer |
| Asset Vault Trust | Excellent | Medium | Medium | Liquid assets, investments |
| Offshore Trust | Excellent | Low | High | High-value assets that you can move out of the country |
The magic happens through segregation—keeping different assets in different protective buckets. Your rental properties might sit in LLCs, your investment accounts in trusts, and your business assets in corporations. When trouble hits one area, it can’t spread to the others.
Spendthrift clauses in trusts add another layer of protection by preventing beneficiaries from pledging future distributions as collateral. Charging orders in LLCs create a similar barrier—creditors can’t force distributions or take control of the entity.
Asset Vault Trusts & 541 Trusts: Asset Protection Concepts and Strategies for Protecting Your Wealth
Here’s where things get interesting. Our Asset Vault Trust is what some attorneys call a 541 Trust, and it’s designed to give you the best of both worlds: bulletproof asset protection and surprising flexibility.
Once you transfer assets into this irrevocable trust, they’re legally owned by the trust—not you. Creditors can’t reach assets you don’t own, period. But unlike those old-school irrevocable trusts that lock everything up tighter than a bank vault, the Asset Vault Trust includes a special power of appointment that gives you significant control over how things work.
Under Arizona Revised Statutes §14-10103, these trusts can provide both creditor protection and estate planning benefits. The special power of appointment allows the trust to be modified under certain circumstances, which means you’re not completely locked out of decisions about your own wealth.
But here’s the catch—and it’s a big one—funding the trust properly is crucial. You can’t just sign papers and call it done. Assets must be legally transferred to the trust through proper retitling, deeds, and account transfers. Miss this step, and your protection evaporates faster than water in the Arizona desert.
More info about Asset Vault Trust benefits
Domestic vs. Offshore Trusts—Picking Your Battlefield
Choosing between domestic and offshore trusts is like choosing between a reliable pickup truck and a Ferrari—both will get you where you’re going, but the ride is very different.
Domestic asset protection trusts in states like Nevada, Delaware, and South Dakota offer solid protection without the headaches. They’re governed by U.S. law, use U.S. trustees, and don’t trigger the same IRS reporting requirements that make offshore trusts feel like tax preparation on steroids.
Offshore trusts in jurisdictions like the Cook Islands or Nevis can provide even stronger protection. These places often don’t recognize U.S. court judgments and have shorter statutes of limitations for creditor claims. It’s like moving your assets to a different legal planet.
But offshore trusts come with higher costs, more complexity, and increased IRS scrutiny. For most Arizona families, a well-structured domestic trust provides excellent protection without feeling like you need a team of international lawyers just to check your account balance.
LLC Armor: When a Charging Order Is Your Best Friend
Limited liability companies are the workhorses of asset protection, and in Arizona, they come with a beautiful feature called the charging order protection. Under Arizona Revised Statutes §29-655, creditors of an LLC member typically can only obtain a charging order—not direct ownership of LLC assets.
Here’s how this works in practice: if someone sues you and wins, they can’t force the LLC to hand over money to satisfy the judgment. They can only wait for distributions you choose to make. It’s like giving someone an IOU that you control the payment schedule for.
Better yet, in many cases, the creditor becomes liable for taxes on LLC income even if no distributions are made. Imagine having to pay taxes on money you never received—it’s a powerful deterrent that makes creditors think twice about pursuing LLC assets.
Single-member LLCs are riskier because courts sometimes ignore the entity protection when there’s only one owner. Multi-member LLCs or LLCs with independent managers provide stronger protection by creating clear separation between you and the entity.
Corporate formalities aren’t just paperwork—they’re your lifeline. Keep separate bank accounts, maintain proper records, and never commingle personal and LLC funds. Sloppy administration can destroy your protection faster than a house of cards in a windstorm. For more information about LLC tax classifications and requirements, see the IRS guidance on LLC taxation.
Family Limited Partnerships: Keeping Wealth in the Bloodline
Family Limited Partnerships are brilliant for families who want to transfer wealth while maintaining control and protection. Think of it as keeping the family fortune in the family, with built-in protection against outsiders trying to muscle in.
Parents typically serve as general partners with management control, while children are limited partners with no management rights. This structure creates what I call a divorce firewall—if a child gets divorced, the ex-spouse can’t become a partner or force distributions. They might get a charging order, but they can’t disrupt family control or grab assets directly.
FLPs also provide valuation discounts for estate and gift tax purposes. A 30% interest in an FLP might only be worth 20% for tax purposes due to lack of control and marketability. It’s perfectly legal and can save substantial estate taxes.
The key is using FLPs for kid-safe training—teaching the next generation how to handle wealth responsibly while the family maintains protective control. It’s like giving your kids the keys to the car, but keeping the title in your name.
Insurance, Titling & First-Line Defenses
Think of insurance as your first line of defense in the asset protection concepts and strategies for protecting your wealth battlefield. But here’s what insurance companies won’t tell you: their policies are written by lawyers whose job is to find reasons not to pay claims. Relying solely on insurance is like going to war with a umbrella when you need a bulletproof vest.

I’ve seen too many families find their insurance gaps at the worst possible moment—right after a major lawsuit hits. That’s why smart asset protection combines proper insurance coverage with strategic property titling and statutory exemptions that work even when insurance companies are looking for ways to deny your claim.
The good news? Arizona provides some excellent statutory protections that most people completely overlook. Combined with proper insurance and titling strategies, these can form a solid foundation for your overall protection plan.
How Much Umbrella Coverage Is “Enough”?
Here’s the uncomfortable truth: there’s no magic number that guarantees you’re safe. The old rule of thumb was umbrella coverage equal to your net worth, but that’s like bringing a knife to a gunfight in today’s litigation environment.
High-risk professionals need to think bigger. A doctor with a $2 million net worth might need $5-10 million in umbrella coverage. Why? Because malpractice exposure doesn’t care about your net worth—it cares about how much damage a jury thinks you caused.
Gap analysis is where most people mess up. Your homeowner’s policy might exclude business activities. Your auto policy might have lower limits than you think. Your professional liability coverage might not cover that side consulting gig. These gaps can torpedo your protection faster than you can say “personal assets at risk.”
Arizona doesn’t have medical malpractice damage caps like some states, which means healthcare professionals face unlimited exposure on certain claims. A car accident or premises liability claim isn’t subject to any caps either—juries can award whatever they think is “fair.”
Proper Titling Beats Prayers in Court
How you hold title to your property can mean the difference between keeping your assets and watching them disappear into a creditor’s pocket. Most people give about as much thought to property titling as they do to reading insurance policy fine print—and that’s exactly the wrong approach.
Arizona’s community property laws create both opportunities and traps. Unlike states that allow “tenants by the entirety” protection for married couples, Arizona’s community property system means that generally, either spouse’s creditors can reach community assets. But here’s the key: properly documented separate property gets protection that many couples never take advantage of.
Joint tenancy with right of survivorship sounds safe but offers zero creditor protection. Either owner’s creditors can reach the entire property, which means you’re essentially doubling your exposure. It’s like leaving your front door open uped because you have a good deadbolt on the back door.
Beneficiary deeds can provide some protection by keeping property out of probate while maintaining individual ownership. They’re not bulletproof, but they’re better than standard joint ownership for creditor protection purposes.
The devil is in the documentation. I’ve seen separate property lose its protected status because couples couldn’t prove the property’s separate nature. Keep those paper trails clean, and make sure your titling strategy aligns with your overall asset protection plan.
Statutory Exemptions Most Folks Forget
Arizona law provides automatic protection for certain assets that most people either don’t know about or don’t maximize. These are like “free” asset protection concepts and strategies for protecting your wealth—you just need to know they exist and how to use them properly.
ERISA-qualified retirement plans like 401(k)s are creditor-proof, even in bankruptcy. IRAs get federal protection up to $1,362,800 (as of 2022), which means maxing out retirement contributions can be more effective than complex trust structures for many families.
Arizona goes further than federal law in protecting life insurance cash values and annuities from creditors. This makes certain life insurance strategies particularly attractive for Arizona residents looking for creditor protection with tax benefits.
The homestead exemption provides significant protection for your primary residence, but it’s not unlimited. Arizona’s homestead protection covers up to $400,000 in equity (indexed for inflation), but only if you file the proper paperwork and meet the residence requirements.
Business owners often overlook these protections when they’re focused on complex entity structures. Sometimes the smartest move is maximizing contributions to protected retirement accounts before setting up trusts and LLCs. It’s not as exciting as offshore planning, but it’s effective and it’s already built into the law.
The key is integrating these statutory protections into your overall strategy rather than treating them as afterthoughts. They work best when they’re part of a coordinated plan that includes proper insurance, strategic titling, and appropriate legal entities.
Timing, Transfers & Arizona-Specific Tripwires
Here’s the hard truth about timing in asset protection concepts and strategies for protecting your wealth: the best time to build your fortress is when the weather’s calm, not when the storm’s already at your door. Once someone’s threatening to sue you—or worse, already has—your options shrink faster than a wool sweater in hot water.

I’ve seen too many good people lose everything because they waited until the last minute. The Fraudulent Transfer Doctrine is like a legal time bomb that can blow up your entire asset protection plan if you don’t handle transfers properly. In Arizona, we follow the Uniform Voidable Transactions Act, which gives courts plenty of ammunition to reverse transfers they don’t like.
Think of it this way: if you move your assets around after trouble starts brewing, you look guilty—even if you’re not. Courts hate that, and they’ll punish you for it.
When Transferring Assets Backfires
The law calls them “badges of fraud,” but I call them red flags that make judges see red. These warning signs can turn your perfectly legal asset protection plan into a legal nightmare that costs you everything you were trying to protect.
Transfers to family members or close friends are automatic red flags. I get it—you trust your spouse or kids more than some distant trust company. But courts see these transfers as attempts to hide assets while keeping them in the family circle.
Inadequate consideration is another killer. If you “sell” your $500,000 house to your brother for $50,000, don’t expect any judge to buy that story. Every transfer needs legitimate business or estate planning reasons beyond just keeping creditors away.
Timing matters more than anything else. Transfers made when you’re already insolvent or facing imminent lawsuits are almost impossible to defend. Even transfers made when litigation is “reasonably foreseeable” can get you in trouble.
The secrecy factor bites people too. If you’re sneaking around, hiding transfers, or trying to maintain secret control over assets you’ve supposedly given away, you’re asking for trouble. Courts can smell deception from a mile away.
Documentation is your lifeline here. Every transfer needs a paper trail showing legitimate reasons beyond creditor protection. Keep detailed records of why you made transfers, what consideration was paid, and how the decision fits into your overall financial plan.
Arizona Homestead—Good but Not Bulletproof
Arizona’s homestead exemption under A.R.S. §33-1101 protects up to $400,000 of equity in your primary residence (that amount gets adjusted for inflation). It’s better protection than many states offer, but it’s not the financial fortress some people think it is.
The exemption covers up to 2.5 acres for urban properties and up to 160 acres for rural properties. But don’t get excited—this protection doesn’t help against mortgage foreclosures, property tax liens, or mechanics’ liens. It only protects against general creditors.
The $400,000 limit sounds good until you realize that many Arizona homes are worth more than that. If your house is worth $800,000 and you have a $200,000 mortgage, you’ve got $600,000 in equity. The homestead only protects $400,000 of that—creditors can force a sale to get at the remaining $200,000.
Integrating Estate & Asset Protection Before the Storm Hits
The smartest asset protection concepts and strategies for protecting your wealth work double duty—they protect your assets today and preserve wealth for your kids tomorrow. But you can’t just slap together an asset protection plan and call it estate planning. These strategies need to work together like a well-oiled machine.
Beneficiary-controlled trusts are beautiful tools that protect your children’s inheritance from their creditors, divorces, and bad decisions. When you set up protection for the next generation before problems arise, courts see legitimate estate planning, not creditor avoidance.
The federal estate tax exemption affects everything we do. With portability between spouses, married couples can effectively shield over $24 million from estate taxes. But these exemptions can disappear if Congress changes the law, so timing your transfers matters.
Step-up in basis creates interesting conflicts between asset protection and tax planning. Assets that get stepped-up basis at death eliminate capital gains taxes, but they have to stay in your taxable estate to get that benefit. Sometimes the best asset protection move costs you tax benefits—it’s all about balancing risks.
The key is implementing these strategies when your life is calm and predictable. Once you’re facing divorce, lawsuits, or business troubles, your options become limited and expensive. More info about Arizona Trust Asset Protection
Early planning gives you flexibility, better protection, and legal defensibility. Wait until the storm hits, and you’re likely to lose everything you’re trying to protect.
Building Your Personal Asset-Protection Blueprint
Effective asset protection concepts and strategies for protecting your wealth require a layered approach—like building a castle with multiple walls, moats, and guard towers. No single tool provides complete protection, but combining multiple strategies creates a defense system that makes attackers think twice about coming after your assets.

Think of it like home security: you don’t rely on just a deadbolt or just an alarm system. You use multiple layers—good locks, motion sensors, cameras, proper lighting, and maybe a dog with an attitude problem. Each layer makes it harder for the bad guys to get what they want, and eventually they move on to easier targets.
The beauty of layered protection is that even if one defense fails, others remain standing. Your LLC might face a charging order, but your Asset Vault Trust stays untouchable. Your umbrella policy might hit its limits, but your homestead exemption kicks in. It’s redundancy in the best possible way.
Cost-benefit analysis matters more than ego. A $25,000 asset protection plan doesn’t make sense for someone with $100,000 in total assets—that’s like buying a $2,500 security system for a $10,000 car. But for high-net-worth individuals or high-risk professionals, the cost of protection is pocket change compared to potential losses.
The maintenance aspect is crucial but often overlooked. Asset protection isn’t like a tattoo—once and done. Laws change, your situation evolves, and your protection needs regular tune-ups. I’ve seen bulletproof plans become Swiss cheese because nobody maintained them properly.
Secrecy protocols aren’t about hiding assets illegally—they’re about not painting targets on your back. The less people know about your wealth and protection strategies, the better. Loose lips don’t just sink ships; they sink asset protection plans too.
Seven-Step Checklist to Lock It Down
Building your personal fortress starts with knowing what you’re protecting and who might come after it. Here’s the roadmap I use with every client:
Step One: Complete Asset Inventory means listing everything you own—and I mean everything. Real estate, investment accounts, business interests, valuable personal property, intellectual property, and even that classic car gathering dust in the garage. You can’t protect what you don’t know you have.
Step Two: Risk Assessment involves identifying your specific exposure sources. Are you a doctor with malpractice risk hanging over your head? A business owner with employee liability keeping you up at night? A real estate investor with premises liability on every property? Different risks require different solutions.
Step Three: Choose Appropriate Entities based on your assets and risk profile. A single-property investor might need just an LLC, while a medical practice owner might need multiple LLCs plus an Asset Vault Trust. One size definitely doesn’t fit all.
Step Four: Properly Fund Your Structures because unfunded trusts and empty LLCs provide about as much protection as a screen door on a submarine. Assets must be legally transferred through proper deeds, account transfers, and retitling procedures. The paperwork matters more than you think.
Step Five: Update Property Titling to reflect your new protection strategy. That family vacation home might need to go into a land trust, while your investment portfolio might transfer to your Asset Vault Trust. Getting the titling right prevents gaps in protection.
Step Six: Obtain Adequate Insurance Coverage as your first line of defense. Review and update liability coverage, including umbrella policies that match your risk profile. Insurance is cheaper than lawsuits, even when you win.
Step Seven: Annual Review and Maintenance keeps your protection current and effective. Laws change, your wealth grows, and your risk profile evolves. What worked five years ago might leave you exposed today.
Picking the Right Allies Without Getting Fleeced
Asset protection requires a team approach, and choosing the wrong team members can be more dangerous than having no plan at all. You need attorneys who understand both asset protection and estate planning, not just someone who read a book about offshore trusts last weekend.
Experience matters more than credentials. I’d rather work with an attorney who’s handled dozens of asset protection cases than someone with impressive initials after their name but no real-world experience. Ask specific questions about their asset protection experience, not just general estate planning work.
Attorney-CPA coordination prevents costly mistakes and missed opportunities. Tax and legal implications overlap constantly in asset protection planning. Your attorney and CPA need to work together, not against each other or in ignorance of what the other is doing.
Fee transparency should be non-negotiable. Avoid attorneys who won’t give clear fee estimates or who push expensive offshore structures without explaining simpler alternatives. If they can’t explain their fees clearly, how can you trust them with your protection strategy?
The fiduciary standard matters when working with financial advisors. You want someone legally obligated to put your interests first, not someone who makes more money selling you expensive products you don’t need.
At Sudden Wealth Protection Law, we’ve built our practice around compassionate, expert guidance custom to each client’s unique needs. We don’t believe in cookie-cutter solutions or one-size-fits-all approaches. Your protection strategy should fit your situation like a custom suit, not like something off the clearance rack.
More info about Asset Protection Attorney services
Frequently Asked Questions about Asset Protection
Is it already too late if I’m being sued?
Here’s the hard truth: once you’re staring down the barrel of a lawsuit, your asset protection concepts and strategies for protecting your wealth options shrink faster than a cheap suit in hot water. But “severely limited” doesn’t mean “completely hopeless.”
The moment litigation papers get filed, every asset transfer you make will be examined under a microscope by opposing counsel looking for fraudulent intent. Courts don’t take kindly to people moving money around after the fact—it looks exactly like what it usually is: panic-driven asset hiding.
That said, you’re not completely out of luck. You can still maximize available exemptions like homestead protections and retirement account shields. You can review your insurance coverage for gaps and potentially add umbrella policies (though some carriers won’t write new policies for people facing active litigation). You can also start planning for post-judgment collection efforts—understanding what creditors can and can’t do after they win.
The key is working with an attorney who knows the difference between legitimate protective measures and moves that will land you in contempt of court. Some strategies remain available even during pending litigation, but the window is slamming shut with each passing day.
Do revocable living trusts protect me from creditors?
This is probably the most common misconception I encounter, and it’s a dangerous one. Revocable living trusts provide absolutely zero creditor protection—none, zip, nada. If you can wake up tomorrow morning and decide to revoke the trust and take all the money back, guess what? Your creditors can force you to do exactly that through a court order.
Think of it this way: if you’re still the boss of the money, you’re still responsible for the debts. A revocable trust is like putting your wallet in your other pocket and claiming it’s not yours anymore. No judge is going to buy that argument.
Revocable trusts are fantastic for estate planning purposes—they help you avoid probate, plan for incapacity, and keep your family’s business private after you’re gone. But for asset protection concepts and strategies for protecting your wealth? They’re about as useful as a screen door on a submarine.
If you want real creditor protection, you need irrevocable structures where you actually give up control. That’s when the magic happens, but it’s also when things get more complicated and permanent.
What’s the downside of moving everything offshore?
Offshore trusts can be incredibly powerful tools, but they’re not the silver bullet that some people imagine. Before you start dreaming about tropical islands and secret bank accounts, let’s talk about the real costs and complications.
The financial hit alone can be staggering. Setup costs often run $50,000 to $100,000 or more, with annual maintenance fees that can reach $25,000. You’re also looking at complex IRS reporting requirements that can trigger audits and penalties if you mess them up.
Control becomes a real issue. To get maximum protection, you typically need an independent offshore trustee, which means you’re asking strangers in a foreign country to manage your life savings. Want to access your money quickly for an emergency? Good luck with that—offshore trustees move at their own pace, not yours.
Tax complications multiply like rabbits. You might face currency exchange risks, foreign tax obligations, and IRS reporting requirements that would make a tax attorney’s head spin. The compliance costs alone can eat up investment returns.
For most Arizona families, domestic asset protection strategies provide excellent protection without the offshore headaches. Save the Cook Islands trust for truly high-risk, high-net-worth situations where you’re facing eight-figure lawsuit exposure. For everyone else, a well-structured Asset Vault Trust or LLC strategy will serve you better and let you sleep at night.
The bottom line: offshore planning is powerful medicine, but like any strong medication, the side effects can be worse than the disease you’re trying to cure.
Conclusion
Look, asset protection concepts and strategies for protecting your wealth aren’t some paranoid fantasy cooked up by conspiracy theorists. They’re smart planning for anyone who’s built something worth taking—and in today’s world, that’s pretty much anyone with a pulse and a paycheck.
Here’s what I’ve learned after 25+ years in this business and losing most of my own inheritance: the wolves are always circling. The difference between keeping your wealth and watching it disappear isn’t luck—it’s preparation.
The magic happens in layered defenses implemented before trouble shows up at your door. Your liability insurance becomes the first wall. Properly structured LLCs and Asset Vault Trusts create the second and third barriers. Strategic property titling and statutory exemptions add even more protection. By the time a creditor works through all these layers, they’re usually looking for easier prey.
At Sudden Wealth Protection Law, we’ve made it our mission to help Arizona families avoid the mistakes I made with my own sudden wealth. Our Asset Vault Trust isn’t just another irrevocable trust—it’s a sophisticated tool that gives you maximum creditor protection while keeping the flexibility you need to actually live your life.
The special power of appointment built into these trusts means you’re not locked into decisions forever. Life changes, and your asset protection should be able to change with it. That’s what separates our approach from the rigid, one-size-fits-all structures other firms push.
Don’t make the mistake I made—waiting until it’s too late. The fraudulent transfer laws in Arizona don’t care about your good intentions. They care about timing. The best asset protection plan in the world won’t help if you implement it after the lawsuit gets filed.
The second-best time to protect your wealth is right now. Every day you wait is another day your assets sit exposed like a house with the front door wide open.
Ready to build a fortress around what you’ve worked so hard to create? More info about Asset Protection services or give us a call to discuss your specific situation. Because peace of mind isn’t just a luxury—it’s a necessity when you’ve got something worth protecting.

