

The Power of an Irrevocable Life Insurance Trust
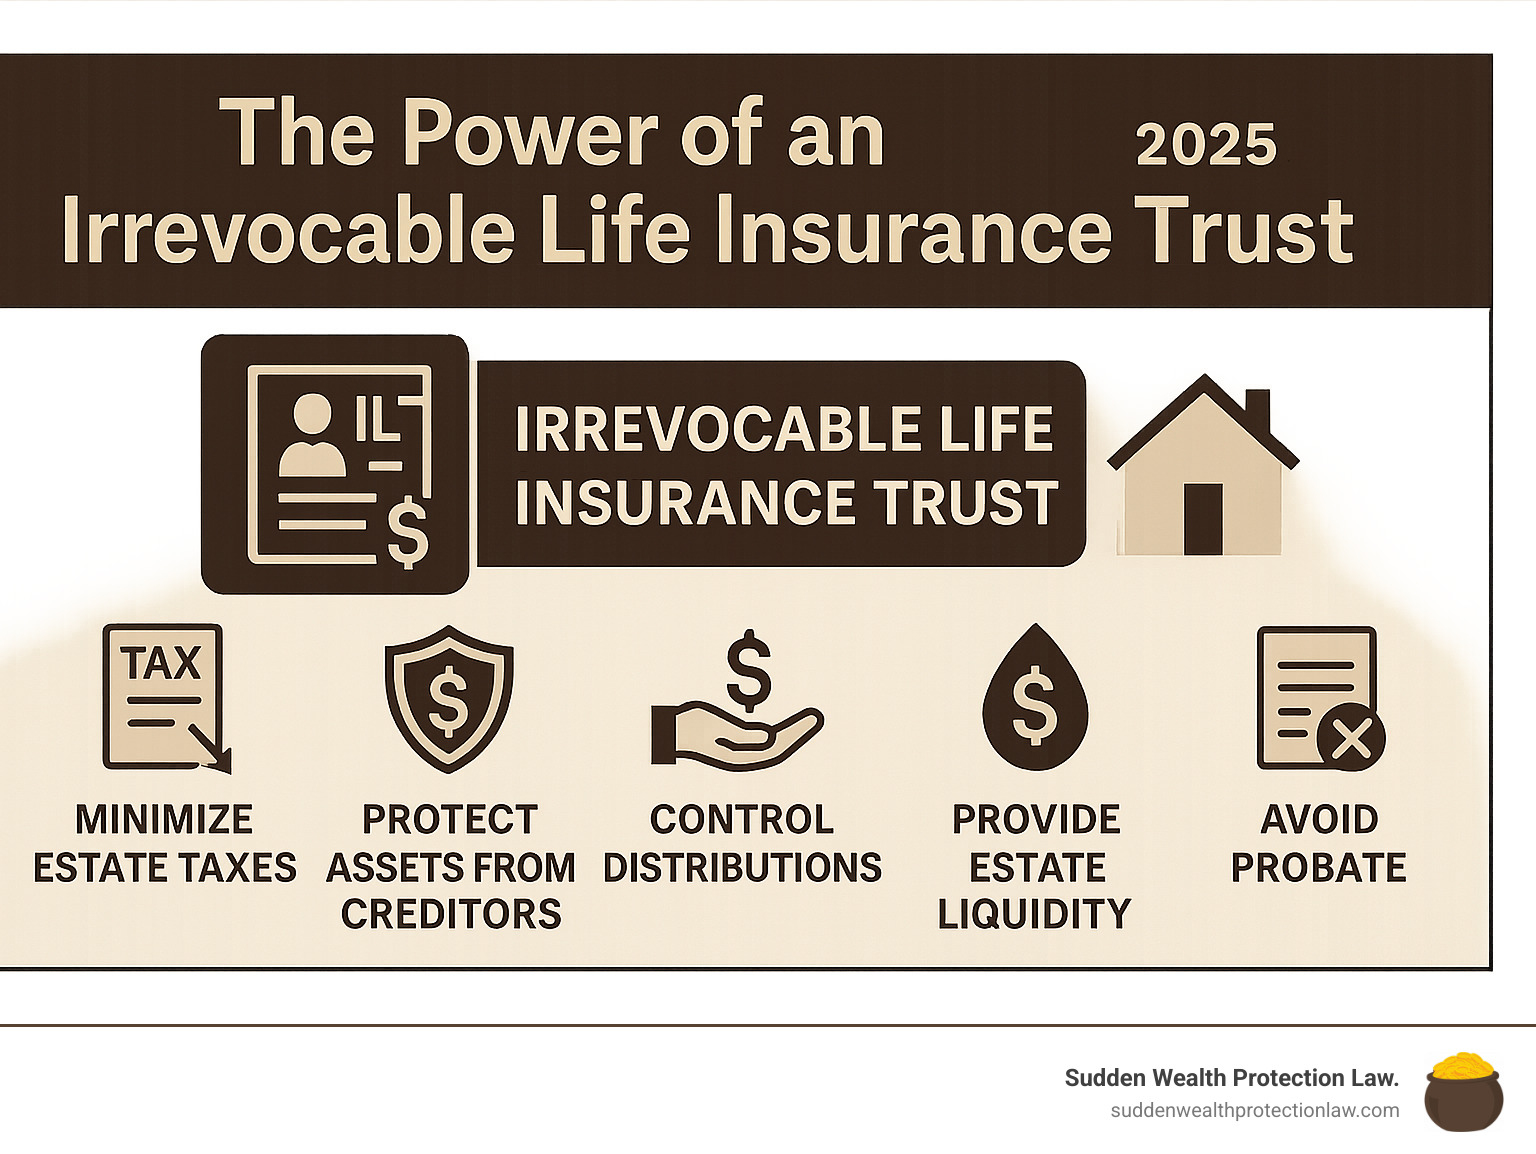
The benefits of an irrevocable life insurance trust (ILIT) are significant for estate planning. If you’re looking for a quick overview, here’s what an ILIT can do:
- Minimize Estate Taxes: Keeps life insurance proceeds out of your taxable estate, potentially saving hundreds of thousands in federal and state estate taxes.
- Protect Assets from Creditors: Shields life insurance death benefits from lawsuits, divorces, and creditors for both you and your beneficiaries.
- Control Distributions: Allows you to dictate when and how beneficiaries receive funds, preventing reckless spending.
- Provide Estate Liquidity: Creates a tax-free cash source to pay estate taxes or expenses without forcing the sale of other assets like a family business.
- Avoid Probate: Ensures a faster, private distribution of funds to your heirs, bypassing the public and often lengthy probate process.
- Protect Government Benefits: Structures inheritances for special needs beneficiaries so they don’t lose eligibility for vital government assistance.
Estate planning can feel like navigating a maze, especially when you start looking at tools like an ILIT. These trusts are powerful, but they come with their own set of rules.
Paul E. Deloughery, founder and managing attorney at Sudden Wealth Protection Law, has spent over 25 years helping families secure their financial future. His expertise includes guiding clients through the benefits of an irrevocable life insurance trust, ensuring their wealth transfers smoothly across generations.
Benefits of an irrevocable life insurance trust terms at a glance:
- advantages of irrevocable trust
- benefits irrevocable funeral trust
- irrevocable trust for medicaid planning
What Is an Irrevocable Life Insurance Trust and How Does It Work?
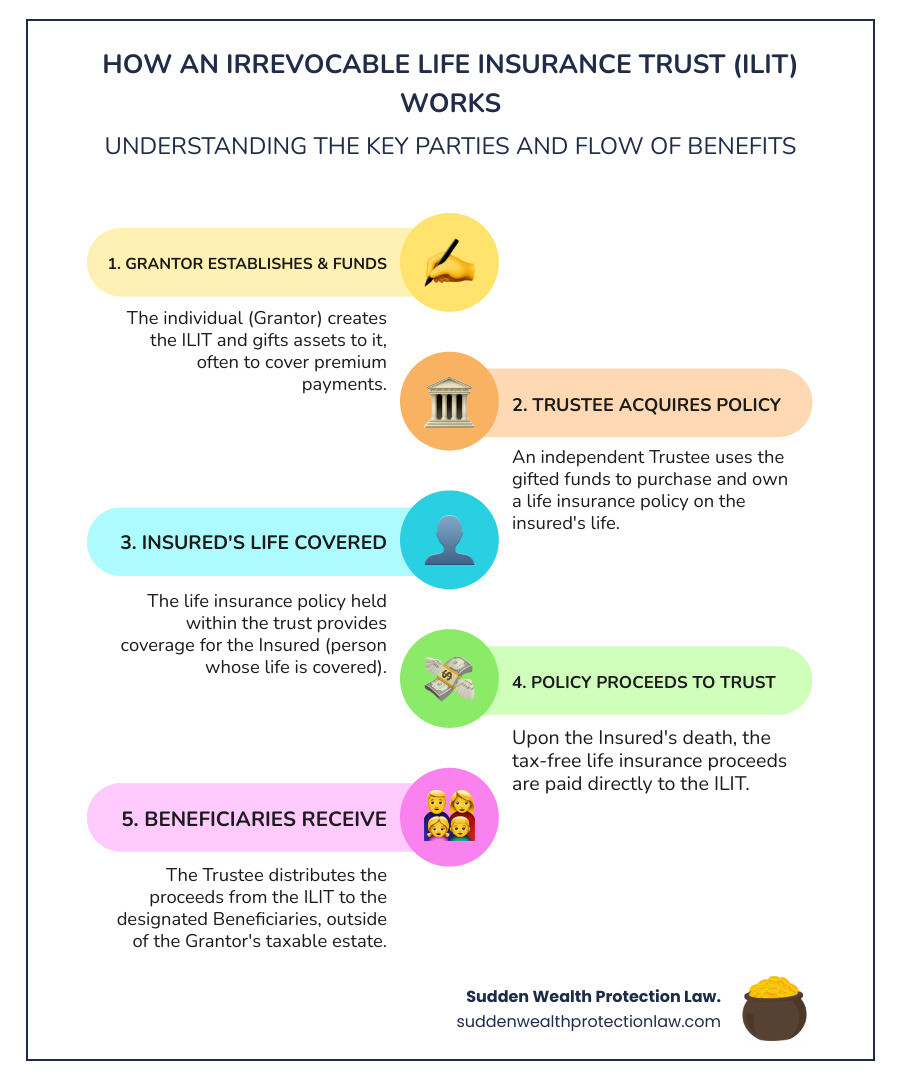
Think of an ILIT as a legal fortress that holds your life insurance policy. Instead of owning your policy directly, you create this special trust to own it for you. The “irrevocable” part means exactly what it sounds like—once you set it up, you can’t change your mind and take it back.
Here’s how the benefits of an irrevocable life insurance trust play out in real life: You create the trust, make annual gifts to fund the premium payments, and when you pass away, the death benefit flows to the trust. Your chosen trustee then distributes the money to your beneficiaries exactly as you’ve instructed.
The real magic happens with the IRS. Since you no longer own the policy, they don’t count it as part of your taxable estate. Let’s say you have a $1,000,000 life insurance policy. If you own it personally, your estate could face between $370,000 and $550,000 in federal estate taxes on that benefit. But if an ILIT owns that same policy? Zero estate taxes.
Now, here’s something crucial to understand: the three-year rule. If you transfer an existing policy to an ILIT and die within three years, the IRS still includes the death benefit in your estate. That’s why many families choose to have the trust purchase a brand-new policy instead—no waiting period, no worries.
Crummey powers might sound like a made-up term, but they’re essential to making your ILIT work. These give your beneficiaries the right to withdraw any annual gifts you make to the trust, but only for 30 days. They almost never actually take the money out, but having this right allows your gifts to qualify for the annual gift tax exclusion.
Key Players in Your ILIT
As the grantor, you’re the architect of this trust structure. You create it, fund it with annual gifts, but then you step back completely.
The trustee becomes the manager of your ILIT universe. They handle premium payments, send required notices to beneficiaries, file tax returns, and eventually distribute the death benefit.
Your beneficiaries are the ultimate winners in this arrangement. They receive those temporary Crummey withdrawal rights each year, but they typically leave the money alone to preserve the tax advantages.
More info about estate planning services
Primary Benefits of an Irrevocable Life Insurance Trust
The benefits of an irrevocable life insurance trust go way beyond just saving on taxes. Think of an ILIT as your family’s financial fortress—protecting your wealth from multiple threats while giving you control over how your legacy unfolds.
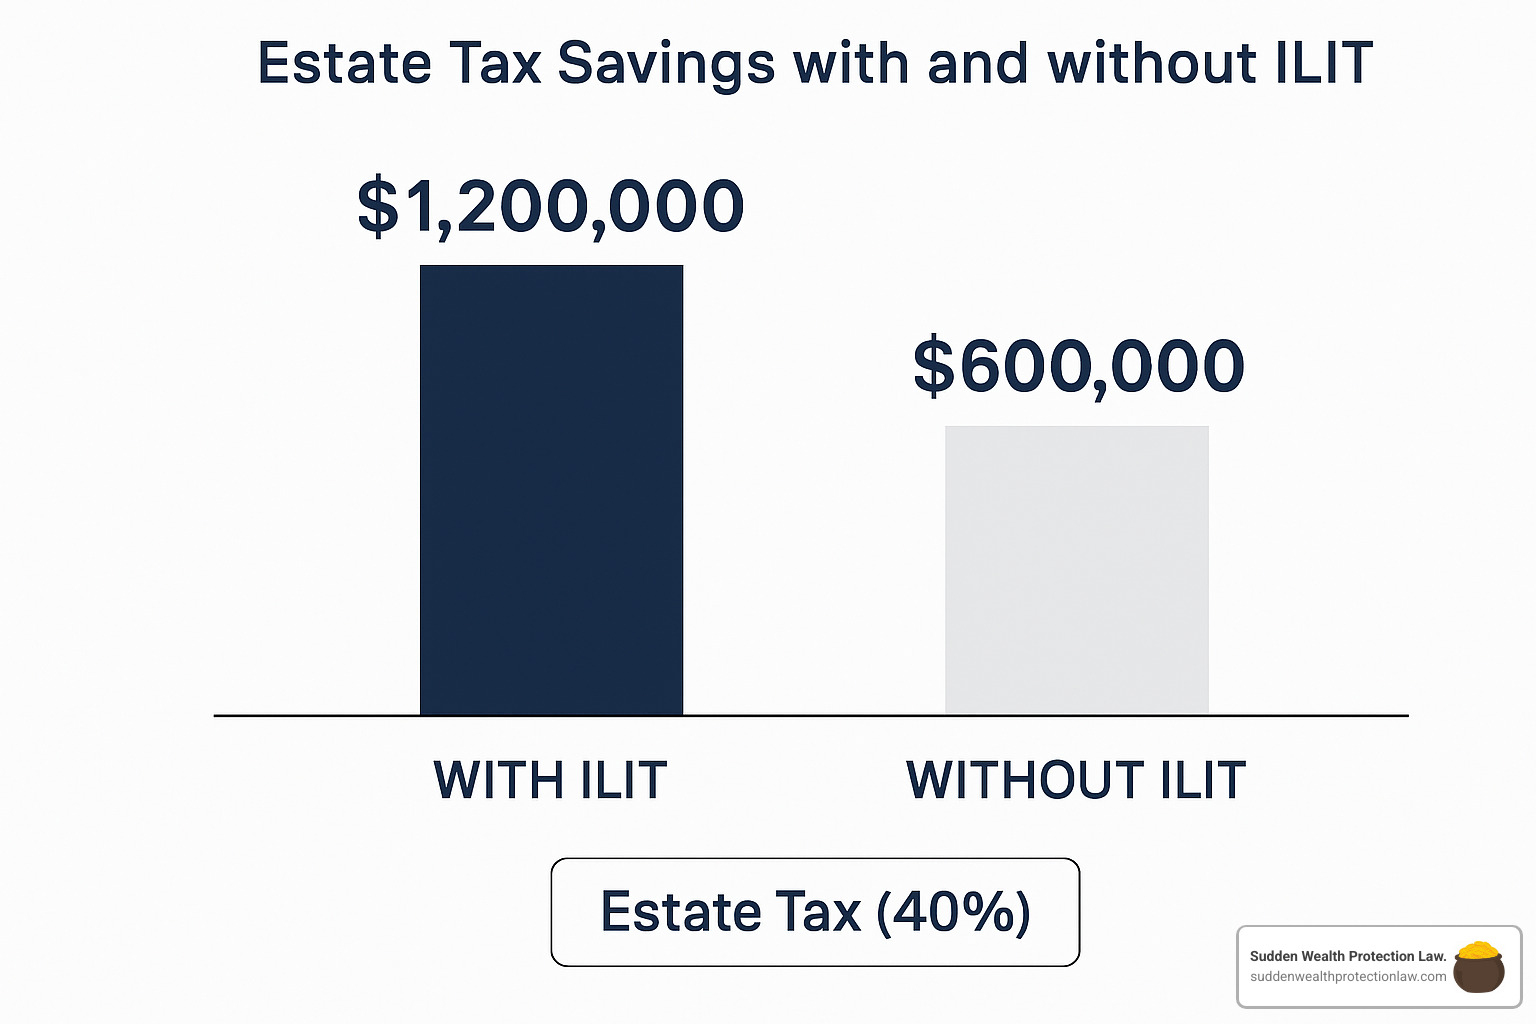
Let’s be honest: most people don’t get excited about estate planning until they see the numbers. When you realize that a $2 million life insurance policy could trigger $740,000 in federal estate taxes, suddenly an ILIT starts looking pretty attractive.
Estate Tax Elimination
Here’s where the math gets interesting. The federal estate tax exemption sits at $13.61 million per person in 2024, but that’s about to change dramatically. Come 2025, this exemption gets slashed by more than half, potentially exposing millions more families to the 40% federal estate tax rate.
Arizona families have an advantage since our state doesn’t impose its own estate tax. But if you own property in other states or might relocate in retirement, you could face state estate taxes with thresholds as low as $1 million in some states.
The beauty of an ILIT is its simplicity for tax purposes. A $500,000 policy owned personally could cost your heirs $185,000 in federal estate taxes. That same policy owned by an ILIT? Zero estate tax impact. The death benefit flows directly to your beneficiaries, completely bypassing your taxable estate.
Latest tax rates and projections
Asset Protection from Creditors
One of the most powerful yet underused benefits of an irrevocable life insurance trust is bulletproof creditor protection. When you transfer a life insurance policy to an ILIT, those assets become unreachable by your creditors—and your beneficiaries’ creditors too.
This protection is absolutely crucial for business owners, medical professionals, and anyone in a high-liability profession. Imagine you’re a surgeon facing a malpractice lawsuit, or a business owner dealing with creditor claims. Your personal assets might be at risk, but the life insurance death benefit sitting in your ILIT remains completely protected.
The protection extends beyond your lifetime. If your adult child faces divorce proceedings, gets sued, or encounters financial difficulties, the trust assets stay safe as long as they haven’t been distributed yet. The spendthrift provisions in the trust document create legal barriers that creditors simply can’t penetrate.
More info about asset protection services
Control Over Distribution Timing
Perhaps the most underappreciated benefit is the control an ILIT gives you over when and how your beneficiaries receive their inheritance. You’re not just leaving money—you’re creating a framework for responsible wealth transfer.
Many parents worry about leaving substantial sums to minor beneficiaries or young adults who might not be financially mature. An ILIT solves this by allowing you to structure milestone distributions—perhaps 25% at age 25, 35% at age 30, and the remainder at age 35.
The trustee discretion component adds another layer of protection. You can grant your trustee authority to delay or modify distributions if a beneficiary is struggling with substance abuse, going through a messy divorce, or facing other circumstances that make immediate distribution unwise.
Tax Advantages and Gift Planning Strategies
The benefits of an irrevocable life insurance trust extend far beyond basic estate tax savings. These trusts open up sophisticated wealth transfer strategies that can multiply your family’s financial legacy while keeping the IRS at bay.
Leveraging Annual Gift Exclusions
Think of the annual gift tax exclusion as your yearly “free pass” for wealth transfer. In 2024, you can give $18,000 per beneficiary without touching your lifetime exemption. Through Crummey powers, ILITs transform this modest annual allowance into a powerful funding mechanism.
The math is compelling. A family with three children can fund $54,000 in annual premiums using only gift exclusions. Over 20 years, that’s $1.08 million in premium payments that could generate several million in death benefits—all without using a penny of your lifetime exemption.
Generation-Skipping Transfer Benefits
Generation-skipping strategies reveal another layer of benefits of an irrevocable life insurance trust. The generation-skipping transfer tax hits transfers to grandchildren and beyond with a brutal 40% rate, but ILITs help you sidestep this entirely.
The leverage effect works in your favor again. Instead of applying your GST exemption to the full death benefit, you apply it to the smaller annual premium gifts. This means your $13.61 million GST exemption can shelter death benefits worth many times that amount.
Special Situations and Advanced Planning
ILITs aren’t just for straightforward estate planning—they shine in complex situations where families need creative solutions. The benefits of an irrevocable life insurance trust become even more pronounced when you’re dealing with business ownership, special needs beneficiaries, or multi-generational wealth transfer.
Business Owners and ILITs
Running a business creates estate planning challenges most families never face. Your company might represent 70% of your net worth, but your kids have zero interest in running it. When you die, how will your family pay estate taxes without destroying the business you spent decades building?
This is where ILITs become invaluable for estate liquidity. The trust provides tax-free cash to pay estate taxes, allowing your family to keep the business intact. No forced sales, no fire-sale prices, no watching your life’s work get dismantled to pay the IRS.
Business continuity planning gets more sophisticated with ILITs. You can structure buy-sell agreements where the trust purchases life insurance on each partner. When someone dies, the insurance proceeds fund the buyout, ensuring surviving partners can afford to purchase the deceased owner’s interest while providing fair compensation to the family.
Special Needs Beneficiaries
Having a child with special needs adds layers of complexity to estate planning that can feel overwhelming. Direct inheritance could be devastating—it might disqualify your child from Medicaid eligibility, SSDI protection, and other government benefits they depend on for survival.
ILITs offer a solution that protects both your child’s inheritance and their access to essential services. The trust can receive the life insurance proceeds and make controlled distributions that supplement rather than replace government benefits.
More info about Arizona asset protection trusts
Potential Drawbacks and Considerations
While the benefits of an irrevocable life insurance trust are substantial, these tools aren’t right for everyone. Understanding the limitations helps you make informed decisions.
The irrevocability is the biggest hurdle for most people. Once you sign those documents, you can’t change your mind. You can’t access the policy’s cash value for emergencies, modify beneficiaries when family circumstances change, or take back control if the trustee isn’t performing well.
This loss of control feels uncomfortable, especially for people who’ve built wealth by staying hands-on with their financial decisions. The administrative complexity creates ongoing headaches. Your trustee must file annual gift tax returns, send Crummey notices to beneficiaries every time you make a gift, and maintain detailed records.
Annual administration costs can range from $2,000 to $5,000 or more, depending on the trust’s complexity. Add trustee fees, tax preparation, and legal updates, and you’re looking at significant ongoing expenses that continue for decades.
The three-year rule creates timing pressure that many people underestimate. If you transfer an existing policy and die within three years, the IRS treats the death benefit as if you still owned it.
When an ILIT Might Not Be Right
ILITs work best for people with substantial estates facing real tax exposure. If your total estate is well below current exemption levels and likely to stay there, the complexity might not justify the benefits.
People who value control and flexibility often struggle with ILITs. If you’re the type who likes to adjust strategies as circumstances change, giving up all control over a valuable asset might feel too restrictive.
Cash flow constraints make ILITs impractical for many families. If you can barely afford the life insurance premiums now, committing to fund them through annual gifts for decades might create financial stress.
Finally, if you need access to policy cash value for retirement income or emergency funds, an ILIT won’t work. Once the trust owns the policy, that money is off-limits to you permanently.
Frequently Asked Questions about Irrevocable Life Insurance Trust Benefits
Navigating trusts can feel like charting a course through choppy waters. Let’s tackle some of the most common concerns about the benefits of an irrevocable life insurance trust.
Can I change an ILIT after it’s created?
“Irrevocable” means exactly what it says. Once an ILIT is set up, changing it is incredibly difficult. You’d typically need the unanimous consent of all beneficiaries and the trustee, and even then, a court might need to give its blessing.
The best way to handle this is to get it right the first time. We spend time upfront, digging deep into your goals and family dynamics to ensure the trust document reflects your exact wishes.
What happens if I die within three years of transferring a policy?
If you transfer an existing life insurance policy into an ILIT and then pass away within three years of that transfer, the IRS considers that death benefit part of your taxable estate.
This is why having the ILIT purchase a new policy from day one is often the smarter play. There’s no three-year waiting period with a newly acquired policy.
How much does it cost to set up and maintain an ILIT?
Initial setup costs typically fall in the range of $3,000 to $7,500, depending on complexity. Annual administration costs generally run $1,500 to $3,000.
When you weigh these costs against potential tax savings, the calculation changes dramatically. A $1,000,000 life insurance policy could trigger $400,000 or more in estate taxes without an ILIT. Compare that to the few thousand dollars in setup and maintenance fees, and you’ll see that an ILIT often pays for itself many times over.
Conclusion
The benefits of an irrevocable life insurance trust make these tools invaluable for comprehensive estate planning. From eliminating estate taxes to protecting assets from creditors, ILITs provide multiple layers of protection for your family’s financial future.
Here’s the reality: current federal estate tax exemptions are historically high but temporary. The scheduled reduction in 2025 will make ILITs relevant for many more families. Acting now, while exemptions are high, allows you to leverage current law for maximum benefit.
At Sudden Wealth Protection Law, we help Arizona families steer these complex decisions. Our approach combines technical expertise with practical guidance, ensuring your estate plan reflects your values and protects your family’s interests.
Paul Deloughery has spent over 25 years watching families struggle with wealth transfer challenges. His experience shows that estate planning isn’t just about taxes—it’s about creating a legacy that empowers your children and grandchildren to be responsible stewards of wealth.
ILITs are powerful tools in that mission, providing both financial protection and the structure needed for successful wealth transfer. They create a framework that protects your family’s assets while teaching the next generation about responsible financial management.
The key is working with experienced professionals who understand both the technical requirements and the family dynamics involved. Don’t let the complexity of ILITs prevent you from exploring their benefits.
Many families find that the benefits of an irrevocable life insurance trust extend far beyond what they initially expected. The peace of mind alone—knowing your family is protected from creditors, estate taxes, and poor financial decisions—makes the planning process worthwhile.
More info about revocable vs irrevocable trusts
Ready to explore how an ILIT might benefit your family? Contact our office to schedule a consultation and find how these powerful tools can protect your legacy for generations to come.

