

Why Arizona Families Are Turning to Irrevocable Trusts for Asset Protection
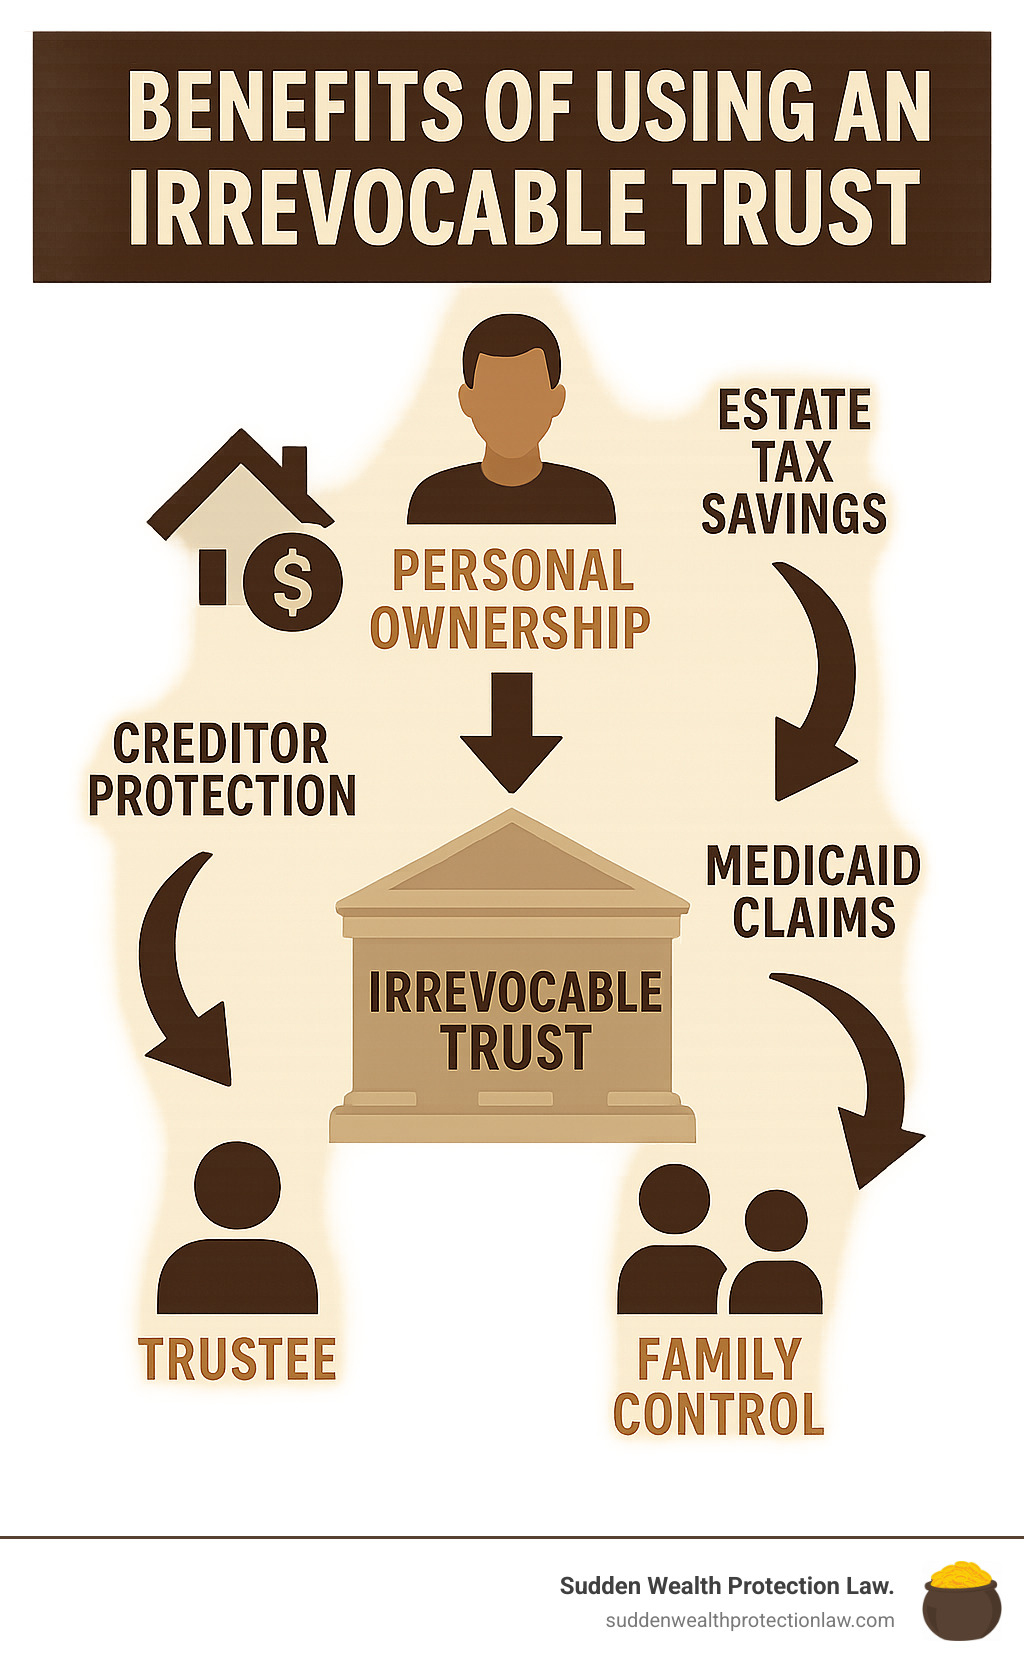
The benefits of using an irrevocable trust can transform how you protect your family’s wealth from lawsuits, taxes, and government claims. Here’s what matters most:
Core Benefits:
- Estate Tax Savings – Remove assets from your taxable estate (up to 40% savings)
- Creditor Protection – Shield assets from lawsuits and business claims
- Medicaid Eligibility – Qualify for long-term care without going broke
- Privacy – Keep family finances out of public probate records
- Control – Dictate exactly how and when heirs receive money
- Legacy Protection – Create multi-generational wealth transfer
Look, I’ve seen families lose everything because they thought a simple will would protect them. It won’t. When you’re facing a lawsuit, dealing with estate taxes that can hit 40%, or watching Medicaid force you to spend down your life savings for nursing home care, you need something stronger.
An irrevocable trust isn’t just paperwork – it’s a legal fortress around your assets. Once you transfer property into it, those assets belong to the trust, not you. That means creditors can’t touch them, the IRS can’t tax them as part of your estate, and Medicaid can’t force you to spend them down.
The trade-off? You give up control. But here’s what most people don’t realize – you can structure these trusts to maintain significant influence over distributions while still getting the protection benefits.
I’m Paul E. Deloughery, and after losing most of a $14 million inheritance in 2009, I’ve spent 25 years helping Arizona families understand the benefits of using an irrevocable trust to avoid the same mistakes I made.
Handy benefits of using an irrevocable trust terms:
- advantages of irrevocable trust
- benefits irrevocable funeral trust
- irrevocable trust for medicaid planning
Why Irrevocable Trusts Matter
Let me paint you a picture that might hit close to home. You’ve built something meaningful – maybe a successful business, saved diligently for retirement, or inherited family wealth. You think you’re set. Then life throws a curveball.
I’ve seen it happen countless times. A lawsuit from a car accident where someone claims you were texting. A business partner’s divorce that somehow drags your company into court. A slip-and-fall at your rental property that turns into a million-dollar claim.
Here’s what keeps me up at night on behalf of my clients: traditional estate planning tools like wills and revocable trusts are about as useful as a screen door on a submarine when these threats come knocking.
Estate taxes can devour up to 40% of everything you’ve worked for if your estate exceeds $13.61 million. That threshold might seem high, but with inflation and appreciating assets, more families are getting caught in this trap than ever before.
Then there’s the probate nightmare. While your family grieves, they’re stuck waiting months or years for courts to sort through your affairs. Meanwhile, probate costs are eating up 3-7% of your estate’s value.
But here’s the threat that really gets personal: Medicaid spend-down requirements. In Arizona, long-term care costs average over $108,000 annually. Before Medicaid steps in to help, they’ll force you to burn through virtually every asset you own.
The benefits of using an irrevocable trust become crystal clear when you realize these aren’t distant possibilities – they’re statistical probabilities. What makes this even more frustrating? Most of these disasters are completely preventable with proper planning.
The Big 7 Benefits of Using an Irrevocable Trust
When families ask me why they should consider giving up control of their assets, I tell them about the seven protection benefits that can save them millions.
Estate Tax Savings: Keep Uncle Sam Out of Your Pocket
The federal estate tax hits like a sledgehammer at 40% for everything above $13.61 million per person in 2024. But here’s the kicker – that exemption gets cut roughly in half come 2026.
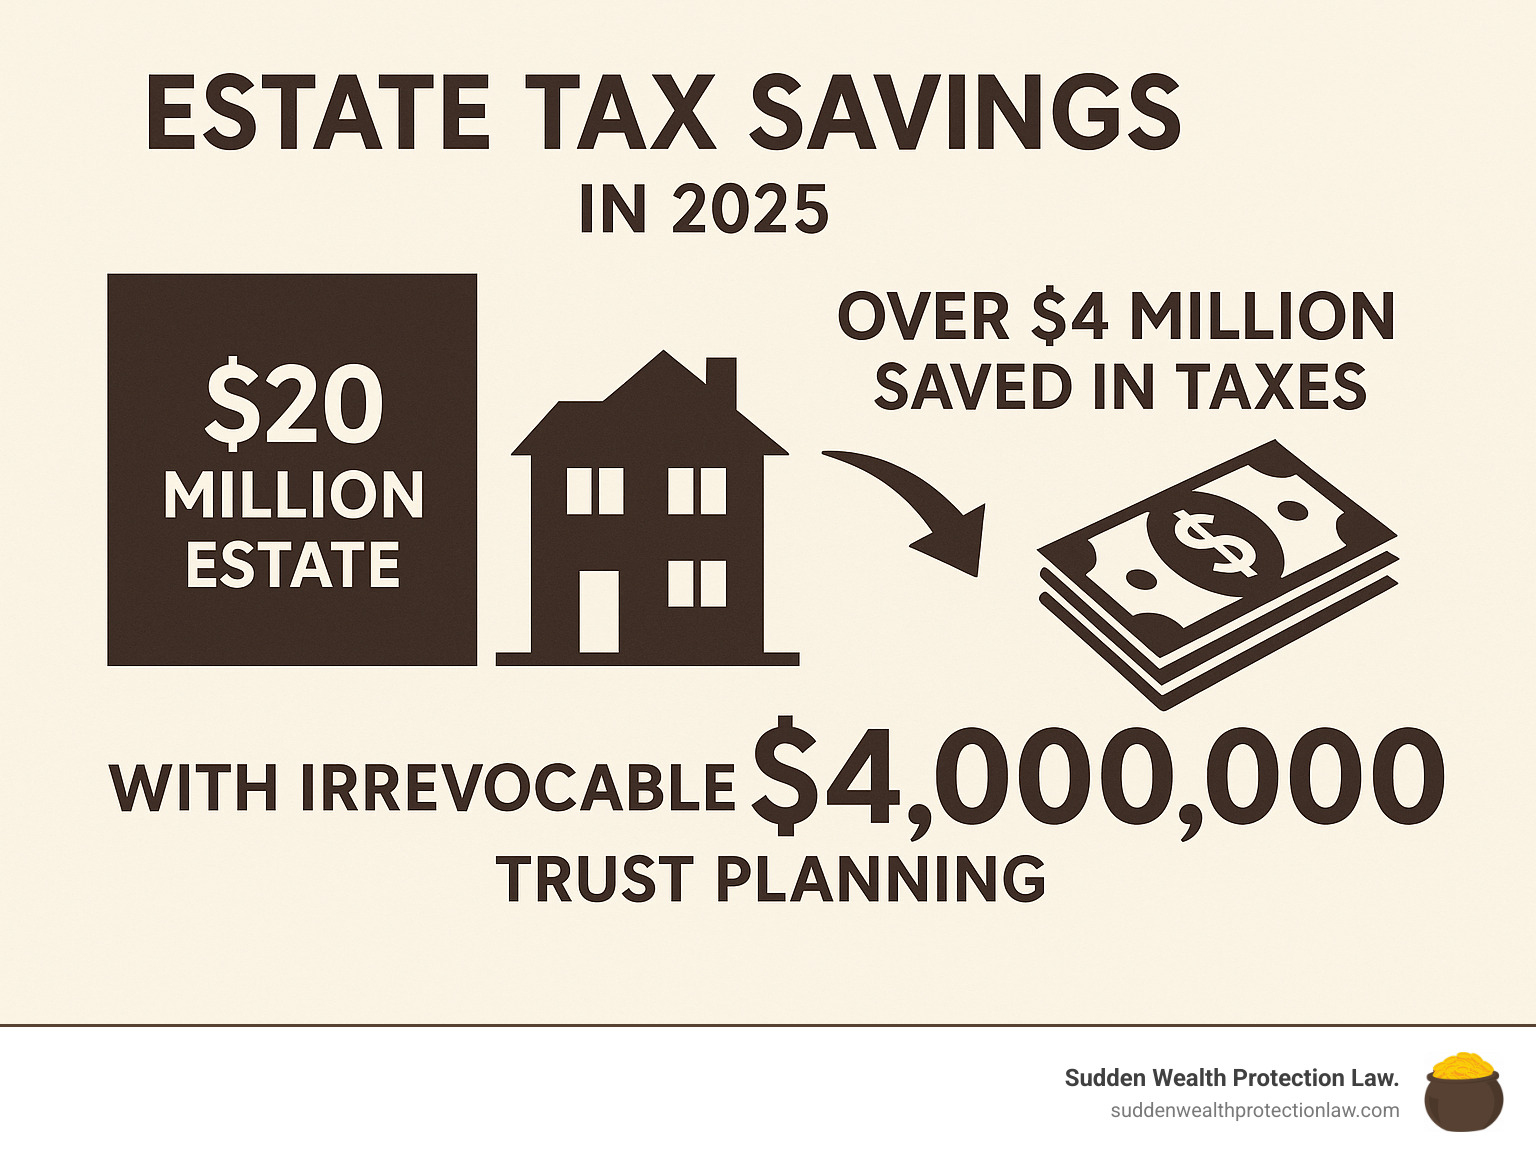
How irrevocable trusts create tax savings: When you transfer assets into the trust, they’re permanently removed from your taxable estate. You can fund these trusts using your annual exclusion gifts of $19,000 per beneficiary in 2025, and all future growth happens outside your estate’s reach.
I worked with a Phoenix business owner whose $20 million estate faced $2.6 million in federal taxes. By moving $10 million into an irrevocable trust, he removed that amount plus all future appreciation from his taxable estate. The result? His family potentially saves over $4 million in taxes.
Learn more about the advantages of irrevocable trust strategies for tax planning.
Asset Protection From Lawsuits & Creditors
This is where irrevocable trusts show their real power. Placing assets in an irrevocable trust shields those assets from creditors—both the grantor’s and the beneficiary’s. Trust assets are also out of reach in lawsuits, as they belong to the trust, not the guarantor or beneficiary.
Arizona’s spendthrift trust laws create strong protection, meaning creditors generally cannot force distributions from properly structured trusts. This builds a legal firewall around trust assets that’s nearly impossible to breach.
Our Asset Vault Trust incorporates special powers of appointment that maximize both flexibility and protection. Unlike traditional irrevocable trusts, the Asset Vault Trust allows for strategic modifications while maintaining bulletproof creditor protection.
Find how Arizona trust asset protection can shield your wealth from creditors and lawsuits.
Qualifying for Medicaid Without Going Broke
Long-term care costs in Arizona average over $100,000 annually, and Medicaid forces you to spend down to just $2,000 in countable assets before qualifying for benefits.
Medicaid Asset Protection Trusts (MAPT) change everything. Transfer assets into an irrevocable trust at least five years before needing care, and those assets become non-countable for Medicaid eligibility.
Keeping Family Drama Private
Probate costs and delays typically consume 3-7% of estate value in Arizona, and the process takes 6-18 months minimum. Trust privacy advantages keep everything confidential.
Understanding the differences in trust vs will vs probate helps you choose the right privacy protection strategy.
Controlling How and When Heirs Spend
One of the most powerful benefits of using an irrevocable trust is controlling distributions long after you’re gone. You can structure age-based payouts, milestone incentives, and discretionary trustee powers.
Spendthrift protections prevent beneficiaries from assigning or pledging future distributions, protecting them from their own creditors and poor financial decisions.
Strategic Gifting & Charitable Plays
Irrevocable trusts open up sophisticated gifting strategies that dramatically reduce tax burdens. Irrevocable Life Insurance Trusts (ILITs) remove life insurance proceeds from your taxable estate. Grantor Retained Annuity Trusts (GRATs) transfer appreciating assets at reduced gift tax values.
Peace of Mind & Multi-Generational Legacy
The ultimate benefit isn’t financial – it’s peace of mind. Dynasty trusts can last for centuries, with each generation benefiting without owning assets directly.
Our Asset Vault Trust incorporates special powers of appointment that allow future modifications while maintaining maximum protection. This creates flexibility that traditional irrevocable trusts simply can’t match.
Irrevocable vs Revocable Trusts: The Control-Protection Trade-Off
Here’s where most people get stuck: they want maximum protection with zero loss of control. Unfortunately, the legal world doesn’t work that way. The benefits of using an irrevocable trust come at the cost of flexibility.
Think of it this way – a revocable trust is like keeping your valuables in a safe deposit box that you control. But if creditors come knocking, they can force you to open that box because you still own what’s inside.
An irrevocable trust is different. When you place assets in an irrevocable trust, the transfer of assets is permanent. You no longer have an interest in or control over those assets. It’s like giving your valuables to a trusted friend with specific instructions. You can’t take them back, but creditors can’t reach them either.
| Feature | Revocable Trust | Irrevocable Trust |
|---|---|---|
| Control | Full | Limited |
| Estate Tax | No savings | Significant savings |
| Creditor Protection | None | Strong |
| Medicaid Planning | Not effective | Highly effective |
| Privacy | Good | Excellent |
| Flexibility | High | Low (but Asset Vault Trust adds flexibility) |
Learn more about revocable trust vs irrevocable trust differences.
Where the Benefits of Using an Irrevocable Trust Outshine a Revocable One
The benefits of using an irrevocable trust become essential when protection trumps flexibility.
High-net-worth families face the biggest decision point. If your estate exceeds the federal exemption threshold, a revocable trust offers no estate tax savings. Irrevocable trusts remove assets from your estate entirely, potentially saving millions.
Lawsuit exposure makes the choice even clearer. Doctors facing malpractice claims or business owners with personal guarantees need assets beyond the reach of creditors. A revocable trust provides zero protection.
Long-term care planning represents another area where revocable trusts fall short. Medicaid treats revocable trust assets as available resources. Properly structured irrevocable trusts can preserve assets while still allowing you to qualify for care.
Common Irrevocable Trust Flavors & Arizona Nuances
Not all irrevocable trusts are cut from the same cloth. After 25 years of watching families get burned by cookie-cutter planning, I can tell you that choosing the wrong trust type is like bringing a butter knife to a gunfight.
Irrevocable Life Insurance Trusts (ILITs) are workhorses for high-net-worth families. These trusts own your life insurance policies outside your estate, which means the death benefit doesn’t get hammered by estate taxes.
Special Needs Trusts become essential when families have disabled loved ones. These can be funded by the beneficiary themselves (first-party trusts) or by family members (third-party trusts).
Medicaid Asset Protection Trusts (MAPTs) are game-changers for families facing long-term care costs. You can shield assets from Arizona’s nursing home expenses while keeping the right to live in your home. But here’s the catch – you need five years of advance planning.
Our Asset Vault Trust isn’t your grandfather’s irrevocable trust. This proprietary structure incorporates special powers of appointment that give you unprecedented flexibility while maintaining maximum creditor protection.
Charitable trusts serve dual purposes. Charitable Remainder Trusts let you receive lifetime income while getting immediate tax deductions.
Arizona’s creditor protection statutes give properly structured trusts serious teeth. Our spendthrift trust laws create legal barriers that can withstand aggressive collection efforts.
Explore Arizona asset protection trusts and find how state law works in your favor.
Pick the Right Tool: Benefits of Using an Irrevocable Trust Type
Matching your trust to your goals isn’t rocket science, but it requires precision.
For estate tax reduction, Grantor Retained Annuity Trusts (GRATs) and ILITs work beautifully. The key is acting before your assets appreciate significantly.
For serious asset protection, the Asset Vault Trust stands alone. The Asset Vault Trust’s special powers of appointment provide flexibility that other structures simply can’t match.
For Medicaid planning, MAPTs require surgical precision. You’re not just protecting assets – you’re navigating complex federal rules while preserving your ability to qualify for benefits.
Trustee selection makes or breaks your strategy. Corporate trustees bring continuity and expertise but lack personal knowledge of your family. Family trustees understand your values but may lack professional management skills.
Setting One Up: Process, Pitfalls, and Protection Strategies
Here’s the truth about setting up an irrevocable trust: one mistake can destroy everything you’re trying to protect. The benefits of using an irrevocable trust only work when the trust is properly drafted, funded, and administered.
Drafting Precision Makes or Breaks Protection
Your trust document isn’t just paperwork – it’s the legal foundation that determines whether your assets survive creditor attacks. Critical drafting elements include clear trust purposes and powers, proper spendthrift provisions that prevent creditors from reaching trust assets, and trustee succession planning.
Funding and Retitling: Where Most People Fail
A beautifully drafted trust that isn’t properly funded is worthless. The funding process starts with obtaining a separate tax identification number (EIN) for the trust, then opening trust bank accounts in the trust’s name. Every asset you want protected must be retitled into the trust name.
You’ll need to update beneficiary designations on retirement accounts and life insurance policies to name the trust as beneficiary. Real estate deeds must be prepared and recorded correctly.
Common Pitfalls That Destroy Protection
The biggest mistake I see is retaining too much control. If you keep the power to revoke the trust, change beneficiaries, or control distributions, you’ve defeated the entire purpose.
Improper funding leaves assets vulnerable to the exact threats you’re trying to avoid. Poor trustee selection creates ongoing management problems that can last for generations.
The Five-Year Protection Clock Starts Now
For maximum creditor protection and Medicaid planning benefits, assets should be in the trust for at least five years before any claims arise. The clock starts ticking when you complete the funding process, not when you sign the trust document.
Why Professional Counsel Isn’t Optional
Irrevocable trusts require experienced legal counsel who understands both the technical requirements and practical implications. While you can change specific trust provisions in limited circumstances, prevention is always better than correction.
Learn about comprehensive asset protection strategies and implementation.
Timeline & Checklist to Lock In Your Shield
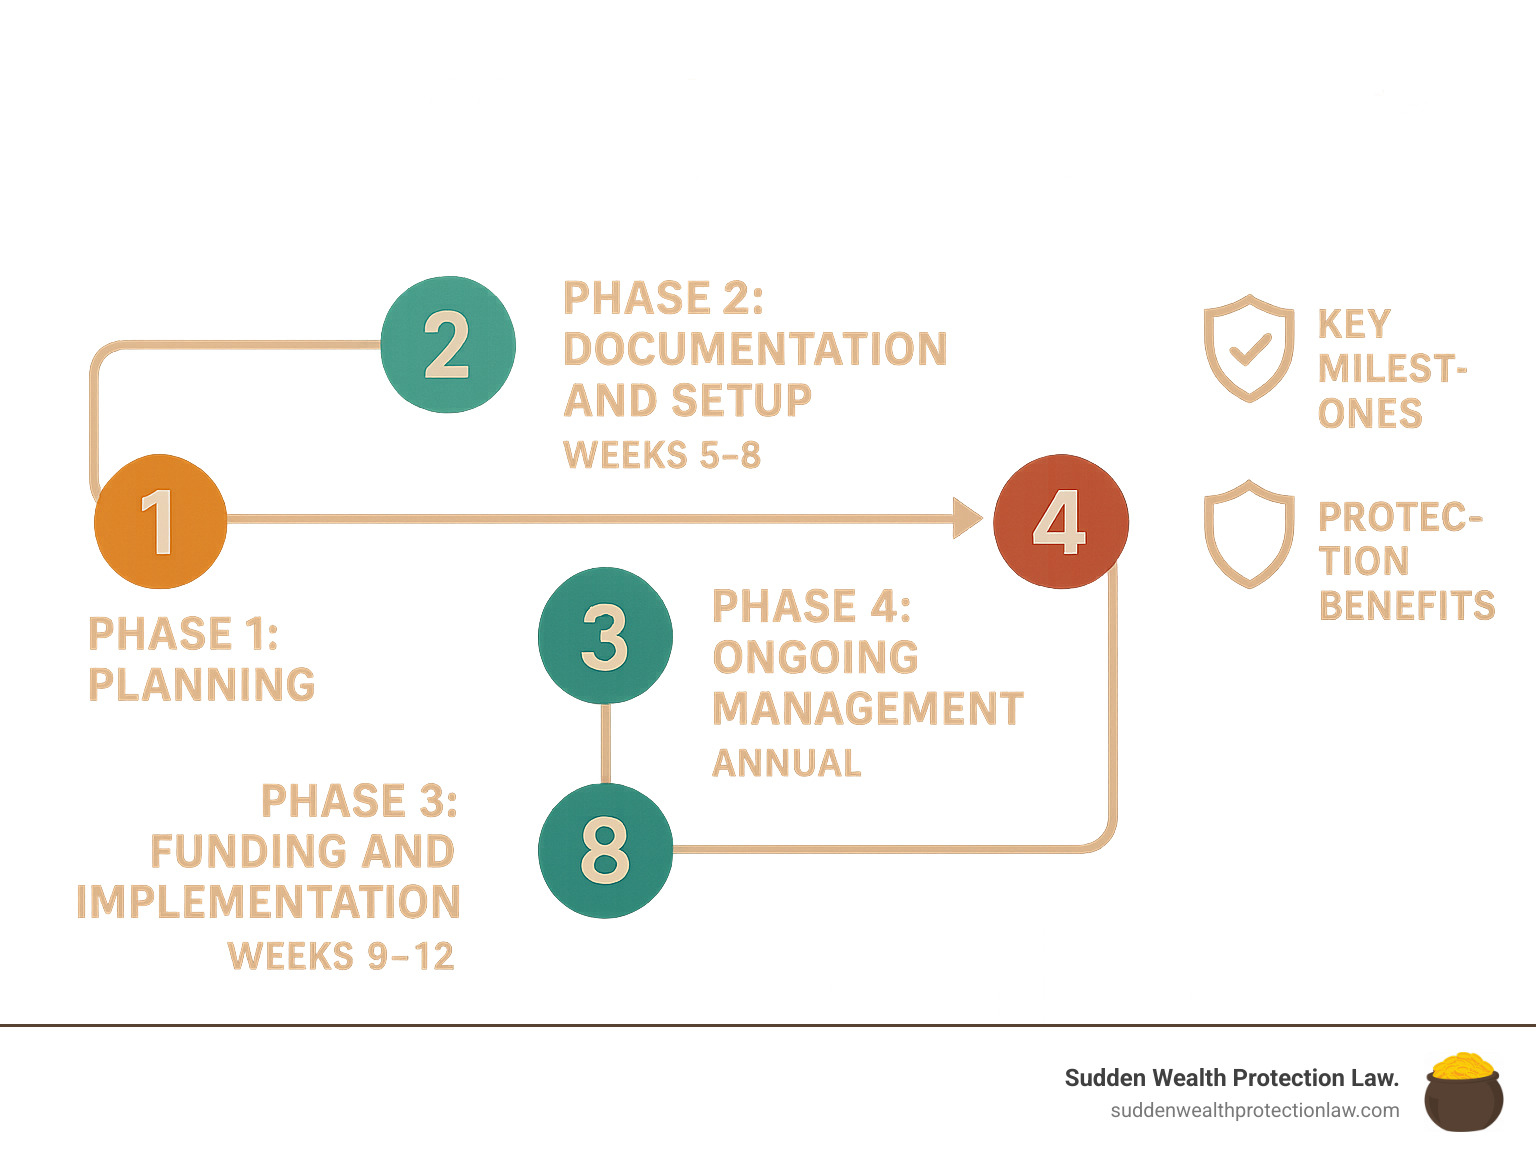
Getting your irrevocable trust up and running properly takes about three months if you do it right.
Weeks 1-4: Planning and Design
During the first month, we assess your protection needs and goals to understand exactly what threats you’re facing. We’ll choose trustees and successor trustees and design distribution provisions that balance your family’s needs with protection requirements.
Weeks 5-8: Documentation and Setup
Once we know exactly what you need, we draft the trust agreement with all the specific provisions required for your situation. We’ll obtain the EIN and open trust accounts so funding can begin immediately after signing.
Weeks 9-12: Funding and Implementation
The final month focuses on retitling all trust assets and updating insurance beneficiaries to reflect the trust structure. We establish ongoing administration procedures during this phase.
Ongoing Annual Management
The benefits of using an irrevocable trust require ongoing attention. Filing required tax returns keeps you compliant with IRS requirements. Regular review of distribution needs ensures beneficiaries get appropriate support.
Find how to protect your assets through proper trust implementation.
Frequently Asked Questions about Benefits of Using an Irrevocable Trust
What level of control can the grantor keep?
This is the question that keeps most people awake at night when considering irrevocable trusts. The answer determines whether your trust actually protects your assets or just creates expensive paperwork.
Here’s the hard truth: you must give up direct ownership of trust assets completely. You can’t revoke the trust when you feel like it, you can’t change beneficiaries on a whim, and you can’t treat trust income like your personal checking account.
But you’re not necessarily powerless. With careful structuring, you can retain the ability to serve as an investment advisor within limits, appoint successor trustees, and keep certain powers of substitution.
The Asset Vault Trust we use incorporates special powers of appointment that allow future modifications while maintaining protection. This gives you significantly more flexibility than traditional irrevocable trusts without sacrificing the benefits of using an irrevocable trust.
The more control you try to keep, the less protection you actually get. The art is finding that sweet spot where you get meaningful protection while preserving the flexibility you need.
Can an irrevocable trust ever be changed or terminated?
Despite what the name suggests, irrevocable trusts aren’t carved in stone. Courts can order modifications when circumstances change dramatically. If all the beneficiaries agree to changes and you can show it won’t violate the trust’s core purposes, that’s another path.
Trust protectors are becoming more popular – these are independent third parties with specific powers to adapt the trust to changing circumstances.
Arizona allows something called decanting, which lets you transfer assets to a new trust with updated terms. It’s like pouring wine from an old bottle into a new one – same wine, better container.
While modifications are possible, they require careful legal analysis and often court involvement. It’s much better to draft the trust correctly from the start.
Who should consider creating one and when is the right time?
The benefits of using an irrevocable trust aren’t for everyone, but they’re absolutely essential for families facing specific risks.
You’re an ideal candidate if your net worth exceeds $5 million and you’re approaching estate tax thresholds, you work in a high-risk profession like medicine or law, you own a business with personal guarantees, or you have family members with special needs.
Timing is everything in asset protection. The protection only works prospectively – you can’t wait until someone’s suing you to set up the shield. Medicaid planning requires five years of advance planning.
Watch for warning signs: increasing professional liability exposure, growing business success that creates bigger targets, aging parents who need care planning, substantial investment portfolios, or real estate holdings with liability risks.
The cost of waiting isn’t just financial – it’s the peace of mind that comes from knowing your family’s wealth is protected.
Conclusion
The benefits of using an irrevocable trust become crystal clear when you’re staring down a lawsuit, watching estate taxes devour your life’s work, or seeing Medicaid force you to spend down everything you’ve built. These aren’t abstract legal concepts – they’re practical weapons in the war to protect your family’s future.
I’ve been on both sides of this equation. I lost most of a $14 million inheritance because I thought traditional planning would be enough. It wasn’t. The hard truth is that wills and revocable trusts are like bringing a knife to a gunfight when you’re facing serious wealth threats.
Estate taxes can take 40% of everything above the exemption threshold. Creditors can strip away decades of savings in a single judgment. Long-term care costs can force you to liquidate your family farm to pay for nursing home bills.
But properly structured irrevocable trusts can stop all of these threats cold. When assets belong to the trust instead of you, creditors can’t touch them. When appreciation happens inside the trust, the IRS can’t tax it as part of your estate.
The trade-off is real – you give up direct control over those assets. But our Asset Vault Trust incorporates special powers of appointment that provide flexibility traditional irrevocable trusts simply can’t match.
The window for action is closing. Estate tax exemptions are scheduled to drop in 2026. Every day you wait increases your exposure to lawsuits, tax changes, and health crises that could wipe out your family’s security.
You can’t protect assets after the threat arrives. Asset protection only works prospectively. Medicaid planning requires five years of advance notice. Estate tax planning becomes impossible once exemptions disappear.
Your family’s financial future depends on what you do right now. You can hope these threats never materialize, or you can build the legal fortress that keeps them at bay.
Learn more about our Asset Vault Trust and find how it combines maximum protection with unprecedented flexibility.
Ready to secure your legacy? Schedule a strategy session to explore how the benefits of using an irrevocable trust can shield your wealth from taxes, creditors, and government claims. The protection you build today determines whether your family thrives or merely survives tomorrow.

