

Why Understanding Trustee-Beneficiary Roles Can Save Your Family From Legal Hell
Can a trustee be a beneficiary of the trust — this question hits my desk at least twice a week, usually from families who’ve found their “simple” trust arrangement has become a minefield of accusations and hurt feelings.
Quick Answer:
Yes, a trustee can legally serve as a beneficiary of the same trust.
But: They cannot be both the sole trustee and the sole beneficiary without any other beneficiaries (current or remainder), as this would invalidate the trust by merging legal and equitable ownership.
Reality Check: Dual roles create inherent conflicts of interest, which can strain family relationships and lead to disputes if not carefully managed.
Best Practice: Appointing co-trustees or a neutral co-trustee is often best because it provides checks and balances and reduce the risk of self-dealing or favoritism.
Here’s what I’ve learned after 25 years of cleaning up trust disasters: The moment you put someone in charge of assets they also stand to inherit, you’ve lit a fuse. Maybe it burns slow, maybe it explodes immediately — but it will burn.
I’ve watched siblings destroy decades of relationships over a trustee-beneficiary who favored themselves in distributions. I’ve seen surviving spouses accused of self-dealing because they didn’t understand their fiduciary duties. And I’ve helped families steer the aftermath when “convenient” dual roles turned into expensive litigation.
The legal answer is straightforward — Arizona law permits trustee-beneficiaries under specific circumstances. The practical answer is more complex, because mixing these roles amplifies every family tension and creates a paper trail that other beneficiaries will scrutinize with a magnifying glass.
I’m Paul E. Deloughery, and I’ve spent over two decades helping Arizona families protect their wealth and avoid the exact conflicts that arise when can a trustee be a beneficiary of the trust questions aren’t properly addressed. After inheriting and losing $14 million myself, I understand how trust arrangements can either preserve family harmony or tear it apart.
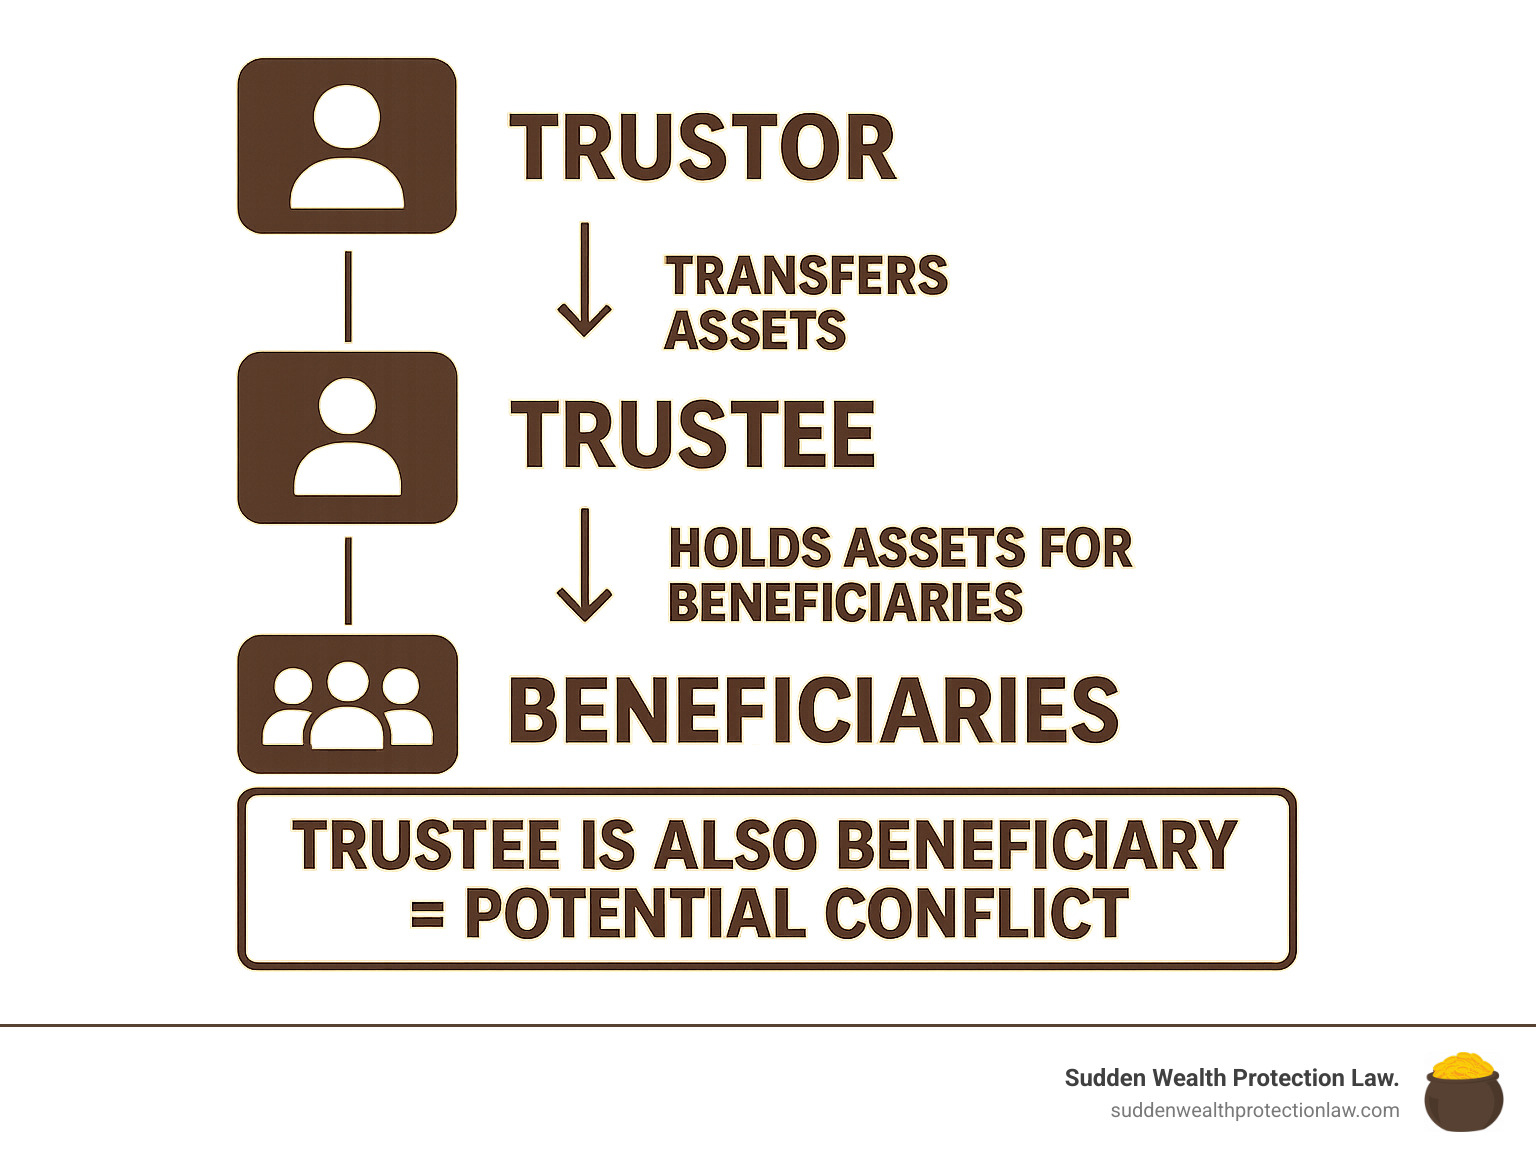
Simple guide to can a trustee be a beneficiary of the trust terms:
Trust 101: Parties and Fiduciary Ground Rules
Before we dive into whether can a trustee be a beneficiary of the trust, you need to understand the cast of characters in every trust drama. Think of it like a three-person play where sometimes one actor tries to play multiple roles — and that’s where things get messy.
The trustor (you’ll also hear them called the grantor or settlor) is the person who creates the trust and funds it with their assets. They’re essentially the playwright and producer rolled into one — they write the script for how the trust operates and provide the money to make it happen. Understanding the difference between trustee versus trustor becomes crucial when we start mixing roles.
The trustee is the person who actually manages the trust day-to-day. They hold what lawyers call “legal title” to the assets, which means their name is on the accounts and deeds. But here’s the key: they don’t get to use these assets for their own benefit. They’re more like a professional money manager with very strict rules about what they can and cannot do.
The beneficiaries are the people who actually get to enjoy the trust assets. They hold “equitable title,” which means they have the right to receive distributions and benefits from the trust, even though their names aren’t on the accounts. They’re the ones the whole trust exists to benefit.
Now here’s where it gets interesting for families: What is a trust grantor often overlaps with the other roles, especially in revocable living trusts where mom or dad sets up the trust, manages it themselves, and also benefits from it during their lifetime.
The Arizona Trust Code recognizes these arrangements, but it also sets up strict rules about how they must operate. When someone wears multiple hats, the potential for conflicts — and lawsuits — multiplies exponentially.
Key Duties Every Arizona Trustee Owes
Here’s what most families don’t realize: being a trustee isn’t just about writing checks and filing tax returns. Arizona law imposes some of the heaviest legal responsibilities in our entire legal system on trustees. These fiduciary duties don’t get lighter when a trustee is also a beneficiary — they actually become more scrutinized.
The duty of loyalty means the trustee must put the beneficiaries’ interests ahead of their own, always. When you’re both trustee and beneficiary, this creates an immediate conflict. You can’t give yourself a bigger distribution just because you think you deserve it or because you’re doing all the work.
The duty of impartiality requires treating all beneficiaries fairly according to the trust terms. Fair doesn’t necessarily mean equal, but it means following the grantor’s instructions without playing favorites.
The prudent investor rule means managing trust investments like a careful, experienced investor would. Your personal risk tolerance or investment hunches don’t matter — you have to consider what’s best for all the beneficiaries and the trust’s long-term purposes.
The duty to account requires keeping meticulous records and providing regular reports to beneficiaries. When you’re also a beneficiary, other family members will examine every expense, every investment decision, and every distribution with a microscope.
These duties create what I call a legal straitjacket. Many well-meaning family members who take on trustee roles don’t realize how strictly courts enforce these standards — until they’re sitting in my office facing a lawsuit from their own siblings.
Can a Trustee Be a Beneficiary of the Trust?
Here’s the straight answer to can a trustee be a beneficiary of the trust: Yes, but with significant caveats that can make or break your trust arrangement.
Arizona Revised Statutes § 14-10802 doesn’t prohibit a trustee from also being a beneficiary. In fact, it’s become standard practice in family trusts, especially revocable living trusts where a surviving spouse serves as both trustee and beneficiary after their partner dies.
The law recognizes that family trusts often need this flexibility. When a widow is managing her deceased husband’s trust while also receiving distributions for her living expenses, it makes perfect sense. Adult children serving as trustees of their parents’ trust while also being beneficiaries can provide continuity and reduce costs significantly.
But here’s where families get tripped up: the arrangement must be structured properly to avoid legal disasters. What is a trustee in a will becomes infinitely more complex when that same person stands to inherit from the estate.
The critical distinction lies between revocable and irrevocable trusts. In revocable trusts, the grantor typically retains control and can modify arrangements if conflicts arise. In irrevocable trusts, the structure becomes permanent, making trustee-beneficiary conflicts potentially explosive.
I’ve watched too many families assume that appointing a co-trustee is optional. It’s not — at least not if you want to sleep peacefully knowing your trust won’t become a courtroom battleground.
When the Same Hat Fits Twice: “can a trustee be a beneficiary of the trust” in revocable living trusts
Revocable living trusts are where can a trustee be a beneficiary of the trust questions most naturally arise, and they’re specifically designed to handle this dual role arrangement.
Picture the classic scenario: Husband and wife create a joint revocable living trust. During their lifetimes, they serve as co-trustees and primary beneficiaries. When one spouse dies, the survivor seamlessly continues as sole trustee and primary beneficiary. No probate court, no delays, no public records.
The surviving spouse can pay monthly bills, manage investments, and take distributions for their support — all without court oversight. It’s efficient, private, and cost-effective. The convenience factor is undeniable, and the tax neutrality keeps things simple.
But here’s what blindsides most families: When the surviving spouse eventually dies, their adult children often become successor trustees while also being beneficiaries. That transition is where relationships explode.
I’ve mediated countless disputes where adult children accused their deceased mother of excessive distributions during her trustee years. The surviving spouse thought she was following the trust terms for her reasonable support. The children thought mom was spending their inheritance on luxuries. Both sides had documentation supporting their position.
The vested interest that makes trustee-beneficiaries effective managers also creates the very conflicts that tear families apart.
The Line You Cannot Cross: sole trustee + sole beneficiary = busted trust
One rule stands absolute in Arizona trust law: A sole trustee cannot be the sole beneficiary of the same trust. This violates the fundamental legal principle that trusts require separation between legal and beneficial ownership.
When the same person holds both roles exclusively, the trust “merges” under the merger doctrine and essentially ceases to exist legally. Courts will treat the arrangement as if the person simply owns the assets outright, eliminating any trust protections entirely.
This merger doctrine exists for rock-solid reasons. If you could create a trust solely for your own benefit while maintaining complete control, it would become an illegitimate tax shelter. The IRS and courts have consistently invalidated these arrangements, and the court precedents are crystal clear.
The practical consequences are devastating. Creditors can reach the assets directly, tax benefits disappear overnight, and the trust’s asset protection evaporates completely. I’ve seen families lose hundreds of thousands in tax benefits because they didn’t understand this basic limitation.
The creditor reach issue particularly stings because many people create trusts specifically for asset protection, only to find their structure actually made them more vulnerable to lawsuits.
Benefits vs. Risks of a Trustee-Beneficiary Arrangement
Let me be brutally honest about the trade-offs when asking can a trustee be a beneficiary of the trust.
After watching families steer these dual roles for over two decades, I can tell you there are genuine advantages — but they come with risks that can destroy both wealth and relationships if you’re not careful.
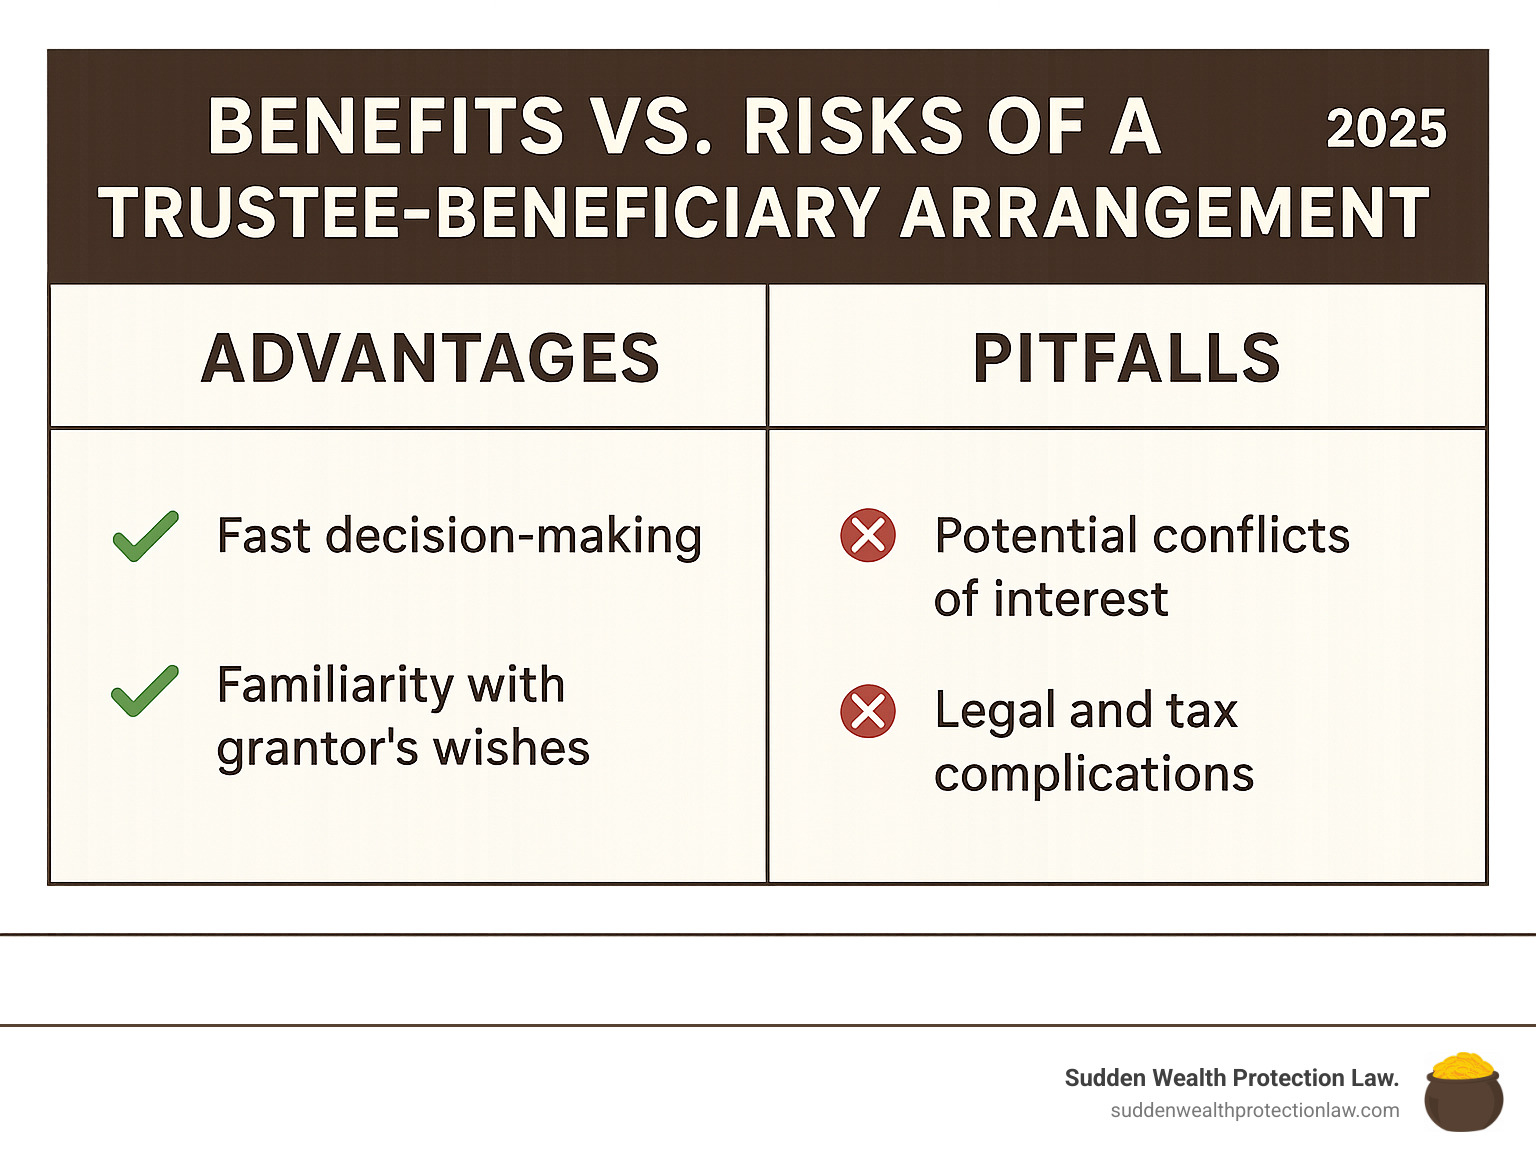
Potential Upsides Worth Grabbing
When can a trustee be a beneficiary of the trust arrangements work well, they create real value for families.
Speed becomes your superpower. A trustee-beneficiary can make decisions immediately without coordinating with outside parties or waiting for committee approvals. When your aging parent needs emergency medical care, their adult child can authorize trust distributions that same day. No bureaucracy, no delays, no missed opportunities.
Nobody knows the family like family. Professional trustees read trust documents; family members understand the grantor’s heart. They know which assets carry emotional significance, which beneficiaries struggle with addiction, and what grandpa really meant when he wrote those vague distribution guidelines. This institutional knowledge prevents costly mistakes that outsiders often make.
The math is compelling too. Professional trustees typically charge 1-2% of trust assets annually — that’s $10,000 to $20,000 per year on a million-dollar trust. Over two decades, you’re looking at hundreds of thousands in saved fees. Family member trustees work for free or minimal compensation.
Skin in the game changes everything. A trustee-beneficiary has genuine motivation to preserve and grow trust assets because poor performance hurts their own inheritance. They’ll fight harder for good investment returns and watch expenses more carefully than someone collecting a fee regardless of performance.
Understanding the distinction between income beneficiary vs principal beneficiary roles helps explain why these incentives matter so much — trustees who benefit from both income and growth have balanced motivations.
Family privacy stays protected. Professional trustees create paper trails and involve outside parties in sensitive family matters. Family trustees keep financial information within the circle of trust, maintaining the confidentiality that many wealthy families value.
Why It Blows Up in Court
But here’s the reality that keeps me busy with trust litigation calls — dual roles create a minefield of potential conflicts.
Every distribution becomes evidence. When a trustee-beneficiary takes money from the trust, other beneficiaries immediately question the motives. Was that $50,000 distribution for legitimate medical expenses, or was sister padding her own pockets? Even proper distributions create suspicion and resentment.
The burden of proof flips against you. In disputes, courts apply heightened scrutiny to any transaction that benefits the trustee personally. Instead of beneficiaries proving wrongdoing, the trustee-beneficiary must prove every decision was proper and made in good faith. That’s a much harder standard to meet.
Sibling rivalry gets expensive. I’ve watched adult children destroy decades of relationships over perceived favoritism in trust distributions. When brother serves as trustee and takes what seems like more than his fair share, the family explodes. These aren’t business disputes — they’re emotional nuclear wars that consume both wealth and relationships.
Documentation failures become smoking guns. Family trustees often keep casual records, assuming everyone trusts them. But when conflicts arise, missing receipts and informal distributions become evidence of mismanagement. Courts interpret poor record-keeping as potential self-dealing.
The statistics don’t lie. Trust contests involving conflicts of interest destroy families at an alarming rate. Legal fees often exceed the disputed amounts, leaving everyone poorer and angrier than when the fight started.
The most heartbreaking cases I handle involve families where the trustee-beneficiary acted in good faith but failed to understand how their dual role would be perceived. Good intentions don’t protect you from litigation when other beneficiaries feel cheated.
Best Practices to Keep Dual Roles Out of Hot Water
If you’re determined to proceed with a trustee-beneficiary arrangement — and sometimes it makes perfect sense — here’s your survival playbook.
Appoint Co-Trustees: Never leave a beneficiary as sole trustee if you can avoid it. Add an independent co-trustee — either a professional or neutral family member — to provide oversight and break tie votes.
Written Distribution Guidelines: Vague trust language like “for health, education, maintenance, and support” invites disputes. Specify what constitutes reasonable distributions and document the decision-making process.
Transparent Accounting: Provide detailed annual reports to all beneficiaries, even if not legally required. Show every distribution, expense, and investment decision. Transparency prevents suspicion from festering.
Reasonable Compensation: If the trustee-beneficiary takes fees, document the work performed and use industry-standard rates. Excessive compensation becomes evidence of self-dealing.
Independent Advice: For major decisions, obtain written opinions from attorneys, accountants, or investment advisors. Third-party validation protects against claims of self-interested decision-making.

Playbook for “Can a Trustee be a Beneficiary of the Trust” Without Getting Sued
Here’s your step-by-step checklist for managing the can a trustee be a beneficiary of the trust question safely:
-
Annual Beneficiary Meetings: Hold formal meetings to discuss trust performance, planned distributions, and beneficiary concerns. Document everything.
-
Consent Letters: For significant distributions to themselves, trustee-beneficiaries should obtain written consent from other beneficiaries or court approval.
-
Investment Committee: For large trusts, create an investment committee with independent members to oversee asset management decisions.
-
Mediation Clauses: Include mandatory mediation provisions in the trust document to resolve disputes without immediate litigation.
-
Regular Reviews: Schedule periodic reviews with trust attorneys to ensure compliance with fiduciary duties and changing laws.
Understanding discretionary beneficiary vs final beneficiary distinctions helps clarify when these protections are most critical.
Special Situations Where a Trustee Should NOT Be a Beneficiary
Sometimes the answer to can a trustee be a beneficiary of the trust is a hard no — especially when you’re trying to protect assets from creditors or lawsuits.
I’ve seen too many families think they could have their cake and eat it too. They want maximum asset protection and family control. But asset protection trusts operate on a brutal principle: you can’t shield assets from creditors while maintaining complete control over them. Courts aren’t stupid, and neither are creditors’ attorneys.
When your primary goal is keeping assets away from potential claimants — whether from business lawsuits, professional liability, or personal creditors — having a beneficiary serve as trustee creates a gaping hole in your protection strategy. The moment a beneficiary controls trust assets, creditors can argue those assets should be available to satisfy claims.
Arizona’s asset protection statutes recognize this reality. The legal separation between trustee and beneficiary isn’t just paperwork — it’s the foundation that makes protection work. Remove that separation, and you’ve built a fortress with the front door wide open.
This is exactly why traditional family trust structures often fail when serious creditor protection is needed. Convenience and control become your enemies when lawsuits hit.
When You Need Maximum Shielding—Think Asset Vault Trust, Not a Beneficiary-Trustee
Here’s where asset protection planning gets real: you must choose between control and protection. Families who try to have both usually end up with neither.
Our Asset Vault Trust structure (which operates similarly to what some attorneys call 541 Trusts) solves this dilemma through careful design. Instead of giving beneficiaries direct control, we incorporate a special power of appointment that provides flexibility while maintaining the legal separation creditors can’t penetrate.
The independent trustee requirement isn’t a limitation — it’s your protection. When creditors or courts examine the trust structure, they see genuine separation between you and the trust assets. No beneficiary control means no creditor access.
But here’s the sophisticated part: the special power of appointment lets you influence distributions and ultimately direct where assets go upon your death. You get meaningful input without the legal control that destroys protection.
For Arizona families facing potential liability from business operations, professional practices, or other high-risk activities, mixing trustee and beneficiary roles can eliminate the very protection they’re trying to create. I’ve watched business owners lose everything because they prioritized convenience over proper structure.
The Asset Vault Trust maintains that crucial legal separation while giving you more flexibility than most people realize. It’s not about giving up control — it’s about being smart enough to structure control in a way that actually works when you need it most.
Frequently Asked Questions about Trustees Who Are Also Beneficiaries
Is a trustee-beneficiary allowed to pay themselves?
This is where the rubber meets the road with can a trustee be a beneficiary of the trust arrangements. Yes, trustee-beneficiaries can absolutely pay themselves — but they’re walking a legal tightrope that trips up more people than you’d expect.
Here’s the deal: You can take distributions according to the trust terms and reasonable trustee fees for your services. But — and this is crucial — you must treat yourself exactly like you’d treat any other beneficiary. No special favors, no creative interpretations, no “I deserve this because I’m doing all the work.”
If the trust says distributions are for “health, education, maintenance, and support,” those same standards apply whether you’re writing a check to yourself or your sibling. I’ve seen trustee-beneficiaries justify luxury vacations as “maintenance” while denying their brother’s request for college tuition. That’s a lawsuit waiting to happen.
Trustee compensation must be reasonable and comparable to what a professional trustee would charge. Taking 3% annually when the industry standard is 1% becomes exhibit A in a breach of fiduciary duty case. Document every hour worked and justify every fee taken.
The golden rule? Document everything. Every distribution decision, every fee calculation, every expense — treat it like you’ll have to defend it in court, because you might.
What happens if other beneficiaries suspect foul play?
When beneficiaries smell something fishy, they have significant weapons in Arizona’s legal arsenal. They can demand detailed accountings, challenge distributions in court, and petition to remove the trustee-beneficiary entirely.
Here’s what keeps me busy: Once suspicion takes root, the burden flips. Instead of beneficiaries proving wrongdoing, you must prove your actions were proper. Courts don’t give trustee-beneficiaries the benefit of the doubt — they apply heightened scrutiny to every transaction that benefited you personally.
I’ve watched trustee-beneficiaries spend $50,000 in legal fees defending a $10,000 distribution because they couldn’t document their decision-making process. The math doesn’t work, but the law doesn’t care about your good intentions.
Beneficiaries can seek damages for losses caused by your breaches of fiduciary duty. If you took excessive distributions or made poor investment decisions that benefited you, you’re personally liable to make other beneficiaries whole. Your personal assets — not just trust assets — are on the line.
The nuclear option? Removal as trustee. Courts will boot trustee-beneficiaries who can’t prove they’re acting impartially. Once you’re removed, good luck repairing those family relationships.
Does Arizona tax a trustee-beneficiary differently?
Arizona follows federal tax principles, so your dual role doesn’t create special tax treatment for distributions. Money flowing to you as a beneficiary gets taxed the same whether you’re the trustee or not.
But here’s the wrinkle: Trustee fees are taxable income, even if those fees come from trust assets you’d eventually inherit anyway. You can’t avoid income tax by calling trustee compensation a “distribution.”
The complexity multiplies with irrevocable trusts, where income tax consequences depend on timing and structure. Some distributions carry taxable income to beneficiaries, others don’t. As trustee-beneficiary, you control that timing — which creates another potential conflict of interest.
Professional tax advice becomes essential when you’re wearing both hats. The intersection of trust taxation, fiduciary duties, and family dynamics requires expertise that goes beyond basic tax preparation.
Conclusion
The question can a trustee be a beneficiary of the trust has a straightforward legal answer but creates a minefield of practical challenges that can blow up families for generations.
Yes, Arizona law allows it. But after watching hundreds of families tear themselves apart over these arrangements, I can tell you the real question isn’t whether you can do it — it’s whether you should.
Here’s what I’ve learned: Dual roles work beautifully when everyone gets along and trusts each other completely. They become legal disasters when human nature kicks in and people start questioning motives, comparing distributions, and keeping score of who got what.
The sweet spot is revocable living trusts with mature family members who understand they’re wearing two hats — and that the trustee hat always comes first. These arrangements provide continuity, save money, and keep family business private.
The danger zone is irrevocable trusts with discretionary distributions, especially when significant wealth is involved. The potential for conflict multiplies exponentially when people can’t change the rules and the stakes are high.
But here’s the thing that matters most: Can a trustee be a beneficiary of the trust questions aren’t really about legal technicalities. They’re about whether your family can handle the inherent tension between someone’s duty to be fair and their natural desire to take care of themselves.
When asset protection is your primary goal, beneficiary-trustees usually defeat the purpose. That’s where our Asset Vault Trust structure provides the separation you need while maintaining family influence through special powers of appointment. You get protection without completely losing control.
The families who succeed with trustee-beneficiary arrangements follow the playbook religiously — co-trustees, transparent accounting, written guidelines, and regular communication. The families who end up in my office for litigation thought they could wing it because “we all trust each other.”
Trust doesn’t eliminate the need for structure. If anything, preserving trust requires more structure, not less.
At Sudden Wealth Protection Law, we help Arizona families make these decisions based on their real dynamics, not their wishful thinking. Sometimes that means embracing trustee-beneficiary arrangements with proper safeguards. Sometimes it means choosing structures that prevent conflicts before they start.
The cost of getting it wrong isn’t just legal fees — it’s family relationships that can’t be repaired. Learn more about our trust and estate dispute services or call us to discuss whether your family can handle the dual-role arrangement you’re considering.
Don’t let convenience today become conflict tomorrow. The stakes — both financial and emotional — are too high to leave to chance.

