

Why You Should Give a Damn About Trusts
Estate trusts for dummies starts with one brutal truth: your family’s financial future hangs in the balance while you’re paralyzed by legal jargon. Here’s what you need to know right now:
Trust Basics:
- Trust = Legal arrangement where one person (trustee) manages assets for another person’s benefit (beneficiary)
- Revocable Trust = You keep control, can change it anytime, avoids probate
- Irrevocable Trust = You give up control, but get powerful asset protection and tax benefits
- Living Trust = Created while you’re alive, manages assets during incapacity
- Testamentary Trust = Created in your will, only activates when you die
You think trusts are complicated? Try explaining to your kids why half their inheritance went to probate attorneys and court fees. Inaction is the real enemy here.
I’ve watched families torn apart in probate court – grown children fighting over assets that should have been protected years earlier. The nightmare isn’t the trust setup. It’s what happens when you don’t have one.
Your legacy is sitting there, completely exposed. Every lawsuit, every creditor, every family dispute becomes a threat to everything you’ve built. This guide cuts through the legal BS and shows you exactly how to protect what’s yours.
I’m Paul E. Deloughery, founder of Sudden Wealth Protection Law in Arizona. After losing most of a $14 million inheritance myself, I’ve spent 25 years helping families avoid the same financial devastation through proper estate trusts for dummies planning strategies. The hard lessons I learned became the foundation for protecting my clients’ wealth from probate courts, creditors, and family disputes.
Easy estate trusts for dummies word list:
What the Hell is a Trust? The Basic Ingredients
Let’s cut the legal fog. A trust is your personal instruction manual for your money and property, but with legal teeth. It’s a binding legal arrangement—a set of rules telling someone how to manage your assets for the people you care about. You’re essentially saying, “Here’s my property and my rules. Follow them to the letter.”
The beauty of this arrangement is control. Your assets are actively managed by someone you’ve chosen, following the roadmap you’ve created. This setup helps you avoid probate, protect your wealth from creditors, and ensure your family gets exactly what you intended—not what some judge thinks is fair.
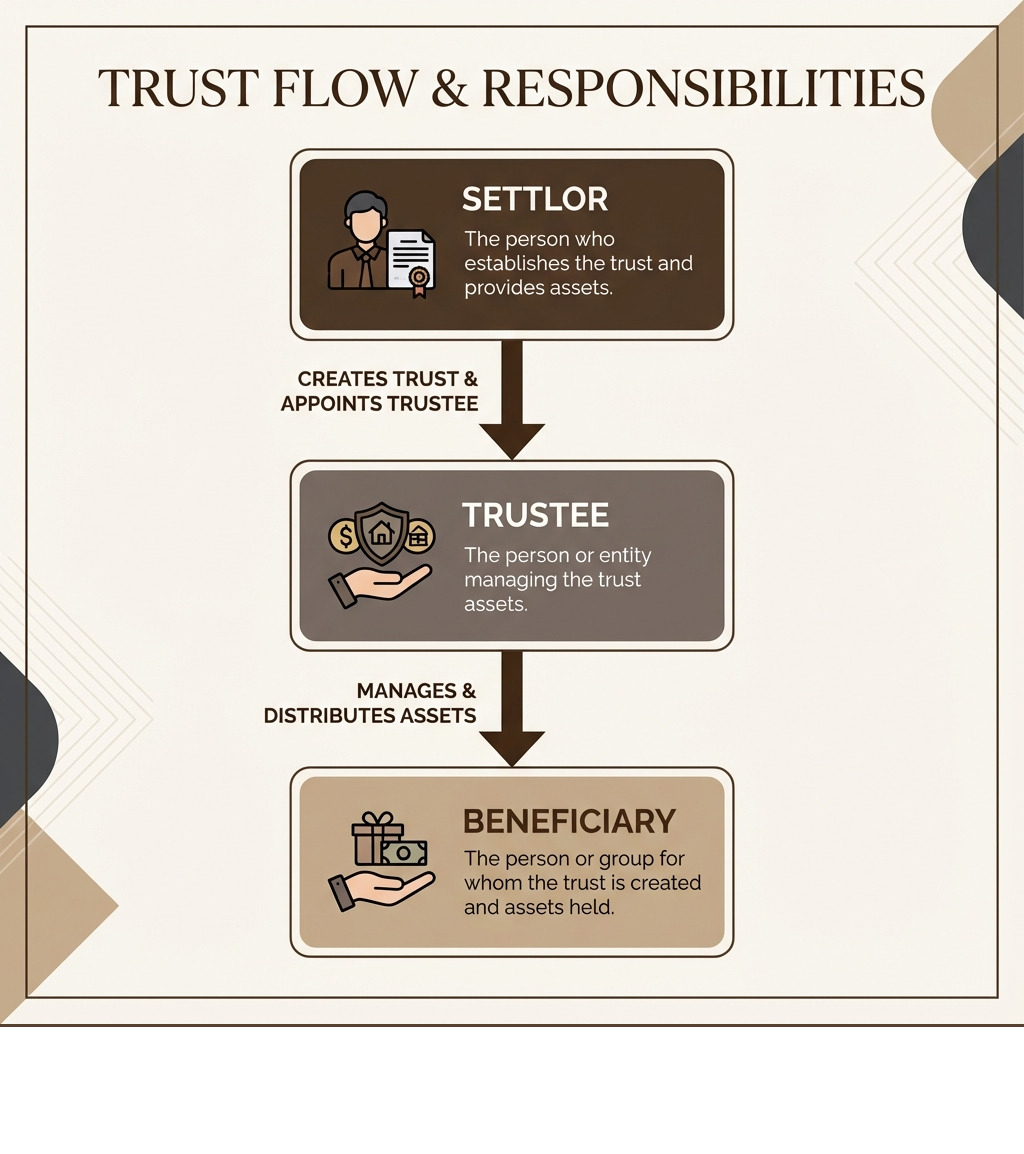
The People Involved: Settlor, Trustee, and Beneficiary
Every trust needs three players to work. Think of it like a relay race—if anyone drops the baton, the whole thing falls apart.
You’re the Settlor – the person who creates this whole arrangement. You decide what goes into the trust, who benefits, and what rules to follow. You’re writing the playbook for your wealth.
The Trustee is your quarterback – the person who manages everything day-to-day. They hold legal title to your trust property and have a fiduciary duty. That’s lawyer-speak for “they have to put the beneficiaries’ interests first, or they can get sued into oblivion.”
Choosing your trustee is critical. Don’t just pick your favorite nephew. You need someone with financial skill, integrity, and a backbone to follow your instructions when family pressure mounts. Many people choose professional trustees—like trust companies or experienced attorneys—because family dynamics get ugly when money is involved.
Your beneficiaries are the end game – the people (or charities) who will ultimately receive the benefits from your trust. These are the folks you’re trying to protect and provide for. You can name specific individuals, set up distributions for groups, or even include charities.
The “Stuff” and The “Rules”: Assets and the Trust Document
Your estate trusts for dummies setup needs two more essential pieces.
First, trust property—the actual assets you’re putting into the trust. This can be your house, investments, or business interests. But here’s the crucial part: you have to transfer ownership of these assets into the trust’s name. This is called funding the trust, and it’s where most people screw up.
I can’t tell you how many families I’ve seen with beautiful trust documents that are worthless because they never changed the titles on their assets. If your house is still in your name when you die, it’s going to probate—trust or no trust. If it’s not in the trust, it doesn’t count.
Second, the trust agreement—the legal document that spells out how your trust operates. This is your instruction manual for the trustee, covering everything from how to invest the money to when your kids can access their inheritance. Think of it as your voice from the grave.
The trust document needs to be crystal clear. Vague language leads to family fights, and family fights lead to lawyer fees that eat up your kids’ inheritance.
For a deeper dive into trust basics, check out this helpful resource: What Is a Trust?.
The Main Flavors of Trusts: Choosing Your Weapon
Picking the right trust is like choosing the right tool. You wouldn’t use a butter knife to carve a turkey, and you shouldn’t use the wrong trust for your family’s protection. The game comes down to one question: Do you want maximum control during your lifetime, or maximum protection from the wolves circling your wealth?
This isn’t an academic exercise. I’ve seen families lose everything by choosing convenience over protection. The key is understanding the trade-offs, because the wrong choice can leave your assets completely exposed.
When we’re talking estate trusts for dummies, the decision usually boils down to two main battles: revocable versus irrevocable, and living versus testamentary. Each choice shapes your control, protection, and timing.
| Feature | Revocable Trust | Irrevocable Trust |
|---|---|---|
| Control | Grantor retains full control; can amend or revoke. | Grantor gives up control; generally cannot be changed. |
| Asset Protection | No protection from grantor’s creditors or lawsuits. | Strong protection from creditors, lawsuits, and long-term care costs. |
| Probate Avoidance | Yes, assets avoid probate. | Yes, assets avoid probate. |
| Tax Benefits | No estate tax benefits (assets remain in estate). | Potential federal estate tax reduction. |
Revocable vs. Irrevocable: The Flexibility vs. Protection Trade-Off
This is the classic flexibility versus protection dilemma, and it’s where most people get stuck.
Revocable trusts (or living trusts) are the people-pleasers. You keep complete control. Want to change beneficiaries? Done. Need to pull money out? No problem. You’re typically the grantor and initial trustee, so you call the shots. For tax purposes, the trust uses your Social Security number; the IRS sees no difference between you and the trust. When you die or become incapacitated, your successor trustee steps in, and your assets avoid the probate nightmare.
But here’s the catch, and it’s a big one: because you control everything, the law sees the assets as yours. This means your creditors can still get to those assets. Got into a car accident and are being sued? Those trust assets are fair game. Facing a business lawsuit? They can come after your trust. A revocable trust is like a well-organized filing cabinet—efficient for management, but it offers zero protection when the building is on fire.
Irrevocable trusts are the opposite. Once you create and fund it, you give up ownership and control of those assets. It’s permanent, and that permanence is its power. Because you no longer own the assets, they’re protected from your future creditors, lawsuits, and even the devastating costs of long-term care (after the required look-back period, typically five years for Medicaid). For larger estates, they can also slash your federal estate tax liability by removing assets from your taxable estate. This is where sophisticated tools like Irrevocable Life Insurance Trusts (ILITs) come in, ensuring your life insurance payout goes to your family tax-free and protected, instead of being eaten by estate taxes.
Think of a revocable trust as a tent—easy to set up and move, but it won’t protect you in a hurricane. An irrevocable trust is a fortress—harder to build and you can’t change the walls, but it’ll keep your family safe when the storm hits.
Living vs. Testamentary Trusts: A Simple “estate trusts for dummies” Breakdown
Timing matters. When your trust comes to life is just as important as its type.
Living trusts (or inter vivos trusts) are created and funded while you’re alive. This is the key to their power. When you die, the assets are already in the trust, so they completely bypass probate court, giving your family immediate access without the delays, costs, and public exposure. The often-missed benefit is incapacity protection. If you have a stroke or develop dementia, your successor trustee can immediately step in to manage your financial affairs without court hearings or a public, humiliating guardianship process.
Testamentary trusts are created through your will, so they only come to life after you die and after your will goes through probate. This is a critical failure. Your will must be filed with the court, your assets are frozen, and an inventory of everything you own becomes public record. Creditors are notified, lawyers are paid, and months (or years) later, whatever is left is used to fund the trust. The downside is obvious: zero probate avoidance and zero incapacity protection. Your family still faces the time, expense, and public scrutiny of probate court just to get the trust started. While they can offer some long-term protection for beneficiaries once funded, they sacrifice the most important immediate benefits of trust planning.
Why Bother? The Real-World Benefits of an Estate Trust
Let’s be honest. The “trouble” of setting up an estate trusts for dummies plan is nothing compared to what your family faces without one. I’ve seen too many families learn this the hard way, watching their inheritance get tangled in legal knots for years.
Avoiding probate isn’t a fancy legal maneuver; it’s saving your family from a bureaucratic nightmare. Probate can drag on for months or years, freezing your assets while fees devour 3-7% or more of your estate’s value. That’s money that should go to your family, not the legal machine.
What really gets me fired up is that probate is a public spectacle. Every detail of your financial life—what you owned, who you owed, who gets what—becomes an open book for anyone to see. A properly funded living trust changes everything. Your assets bypass probate, and privacy becomes your family’s shield—no public records, no court drama, no nosy neighbors or predatory scammers looking at your family’s inheritance.
Asset Protection: Building a Fortress Around Your Wealth
This is where trust planning gets serious. I’ve seen families lose everything because they thought lawsuits and creditors were other people’s problems. They’re not. In today’s world, one bad car accident or a business dispute can wipe out a lifetime of work.
Irrevocable trusts create a legal fortress around your wealth. Once assets are properly placed in these trusts, they’re no longer considered yours, meaning creditors, lawsuits, and even bankruptcy generally can’t touch them. It’s not about hiding money; it’s about legally and ethically protecting what you’ve earned for your family.
Divorce can also devastate family wealth. Assets held in a properly structured protective trust can be designated to stay within your bloodline instead of walking out the door with an ex-spouse of one of your children.
Here in Arizona, we use specialized strategies like the Asset Vault Trust (also called a 541 Trust) that provides maximum protection with remarkable flexibility. This irrevocable trust uses a special “power of appointment,” which allows a trusted, independent person (a “trust protector”) to make limited changes to the trust in the future if laws or family circumstances change. This gives you ironclad protection from creditors with the ability to adapt, which is a game-changer for long-term planning.
Control from the grave sounds morbid, but it’s one of the most powerful and loving things you can do. You dictate how and when beneficiaries get their inheritance. A trust can fund a grandchild’s college education but not a sports car. It can provide a steady monthly income to a spendthrift relative while protecting the principal from being blown in a year. You ensure your wealth is used to build up your family, not enable their worst impulses.
Planning for incapacity is crucial. If you can’t manage your affairs due to illness or injury, a living trust lets your successor trustee step in immediately—no court, no public guardianship, no family fights over who should be in charge.
Special Situations: A custom “estate trusts for dummies” approach
Specialized trusts solve unique challenges that a simple will can’t handle:
- Minor children: Leaving a large inheritance directly to an 18-year-old is one of the worst financial mistakes you can make. Imagine your son getting a check for $250,000 the day he starts college. How long do you think that money lasts? A trust lets you appoint a responsible trustee to manage the funds for his actual needs—tuition, housing, health—while protecting the principal from being spent on a fleet of jet skis and a spring break trip to Cabo. You can set distribution ages, like one-third at 25, one-third at 30, and the rest at 35, giving them time to mature.
- Beneficiaries with disabilities: A direct inheritance could disqualify them from essential government benefits like Supplemental Security Income (SSI) or Medicaid, which have strict asset limits. A Special Needs Trust (SNT) acts as a protective pocket for assets, separate from the beneficiary’s personal funds. This means the trust can pay for things that government benefits don’t cover—like a specialized vehicle, a vacation, therapy, or a new computer—without counting as a resource that would kick them off their lifeline programs. It’s the difference between basic survival and a life with dignity and comfort.
- Blended families: This is a minefield of potential conflict. A common fear is that the surviving spouse will remarry and leave all the assets to their new family, disinheriting the children from the first marriage. A Qualified Terminable Interest Property (QTIP) Trust is the perfect solution. It provides income and support for your surviving spouse for the rest of their life. They’re taken care of. But they can’t touch the principal. When they pass away, the remaining assets go directly to your children, not their children or a new spouse. It prevents bitter family disputes before they can even start.
The “Trusts are for Rich People” Myth and Other Lies
Let’s cut through the nonsense that keeps regular folks from protecting their families. I’ve heard these myths a thousand times, and they’re all garbage designed to keep you paralyzed while your assets sit there naked and vulnerable.
“Trusts are only for the wealthy.” This is the granddaddy of all lies. Look, the wealthy use trusts because they’re smart, not because they have some special privilege. If you own a house, have a retirement account, or carry life insurance, you’ve got something worth protecting. I’ve watched middle-class families lose $50,000 to probate on a $300,000 estate. That’s money that should have gone to the kids, not the courthouse.
Probate doesn’t care if you’re worth $200,000 or $2 million – it’ll eat up 5-10% either way. The wealthy figured this out years ago. The rest of us? We’re still buying into the myth that estate trusts for dummies planning is some luxury item we can’t afford.
“Setting up a trust costs too much.” Here’s some math that’ll wake you up. A quality trust might cost you $3,000-$5,000 upfront. Probate? That’ll run $15,000-$30,000 easy, sometimes way more. Plus your family gets to wait 18 months while lawyers get rich and your assets sit frozen. Which sounds like the better deal?
Think of it like insurance. You pay now to avoid a much bigger hit later. Every day you wait, you’re gambling with your family’s financial future.
“You lose control once assets go into a trust.” Only if you choose to. With a revocable trust, you keep complete control – you can change it, add assets, remove assets, or scrap the whole thing tomorrow if you want. You’re typically the trustee, so nothing changes in how you manage your money day-to-day.
Now, irrevocable trusts do require giving up control. But that’s exactly why they offer bulletproof asset protection. You can’t have it both ways – maximum control and maximum protection. Pick your poison based on what keeps you up at night.
“Trusts are only useful after you die.” Wrong again. This might be the most dangerous myth because it ignores one of the biggest benefits: incapacity planning. What happens if you have a stroke tomorrow? With a trust, your chosen successor trustee steps in immediately. Without one? Your family gets to beg a judge for permission to pay your bills.
I’ve seen families spend months in court fighting over guardianship while dad’s assets sit frozen and the bills pile up. A living trust prevents that nightmare entirely. It’s not just about death – it’s about living with dignity when life goes sideways.
The truth is simple: these myths exist because the system profits from your confusion. While you’re worried about whether trusts are “for you,” probate attorneys are buying vacation homes with fees from estates that should have been protected years ago.
Setting Up a Trust: The No-Nonsense Checklist
So, how do you set up an estate trusts for dummies plan? Let me be crystal clear: this is not a DIY project. I’ve spent decades cleaning up the wreckage from people who tried to save a few bucks with online forms or cheap legal software. These DIY disasters often contain fatal flaws, use the wrong type of trust, or are never funded correctly, leaving families in worse shape than if they had done nothing at all. You wouldn’t perform your own heart surgery, so don’t draft the complex legal documents that govern your family’s entire financial future.
The stakes are too high. Hire a professional who lives and breathes this stuff. For a broader understanding of the process, you can consult: Setting Up a Trust in Your Estate Plan.
Step 1: Define Your Goals
Before calling an attorney, get clear on what problem you’re trying to solve. This is about protecting what matters most. Don’t just say “I need a trust.” Know your ‘why.’ Are you worried about:
- Asset protection from lawsuits in your high-risk profession?
- Probate avoidance to spare your family that public, expensive, and time-consuming nightmare?
- Beneficiary protection for minor children, a relative with a spending problem, or those with special needs?
- Incapacity planning in case you have a stroke or accident and can’t manage your own affairs?
- Tax savings for a larger estate that might be subject to federal or state estate taxes?
- Blended family harmony, ensuring your spouse is cared for while your kids are protected?
Clear objectives help your attorney design the right tool for the job, not just a generic, one-size-fits-all document.
Step 2: Draft and Fund the Trust
This is where your legal professional takes the wheel, but your job isn’t over.
Hire a competent attorney who specializes in estate planning and trusts—not your cousin who does personal injury law. They’ll draft the trust document to reflect your specific goals and comply with your state’s laws.
When you get the draft, review it carefully. Don’t just skim and sign. Ask questions. Make sure you understand who the trustees are, who the beneficiaries are, and how the distributions will work. This document will speak for you when you can’t, so make sure it says exactly what you want.
Here’s where most people stumble: funding is critical. A trust document is just expensive paper if it’s not funded. Funding means changing the ownership titles of your assets from your name to the trust’s name. This isn’t just about your house. It’s everything: your checking and savings accounts, your non-retirement brokerage accounts, your business ownership interests (LLC membership, S-Corp shares). Even valuable personal property, like art collections or classic cars, should be formally assigned to the trust. I’ve seen estates where the house was in the trust, but a $500,000 investment account was forgotten. Guess what went to probate? That half-million dollars, chewed up by fees and delays, all because of one missed signature.
Step 3: Don’t Just Set It and Forget It
Creating a trust is a huge step, but it’s not the last one. Your life changes, and your trust needs to change with it. Thinking you are done after you sign the papers is a rookie mistake. A trust is a living plan, not a historical document. I tell my clients to review their trust every 3-5 years, or immediately after any major life event, including:
- Marriage or divorce (yours or a beneficiary’s)
- The birth or adoption of a child or grandchild
- The death of a spouse or beneficiary
- A beneficiary developing a disability, an addiction, or serious financial trouble
- A significant increase or decrease in your net worth
- Buying or selling a major asset like a business or real estate
- Moving to a different state (as state laws differ significantly)
An outdated trust can be just as dangerous as no trust at all. An ex-spouse could still be listed as a beneficiary. A new child might be accidentally disinherited. Your chosen trustee may have passed away or may no longer be the right person for the job. A periodic review with your attorney prevents a lifetime of regret for your family.
Conclusion: Stop Procrastinating and Protect What’s Yours
Here’s the bottom line: estate trusts for dummies isn’t about dumbing down legal concepts. It’s about cutting through the BS to show you what’s at stake. You’ve learned trusts are strategic tools that offer control, privacy, and a wall of protection against lawsuits, creditors, and incapacity.
Let’s be brutally honest: a will alone is not enough. A will is a roadmap to probate court, not an escape route. It guarantees your family will spend months or years in legal limbo while courts and attorneys pick through your assets.
The math is simple: the cost of inaction is the highest cost of all. Probate fees can devour 3-7% of your estate, your family’s privacy is destroyed, and your assets are frozen when your loved ones need them most.
You’ve worked too hard to let it all be squandered because you couldn’t be bothered to set up proper protection.
At Sudden Wealth Protection Law, we specialize in Arizona estate planning that works. We’ve seen what happens when families don’t plan—and we’ve seen the peace of mind that comes when they do. Our mission is to empower families and business owners to protect their assets and create a lasting legacy.
Don’t leave your family’s future to chance or the mercy of probate courts. Take control. Protect what’s yours.
The time for procrastination is over. Your family’s financial security depends on the decisions you make today.
Protect your family and assets with our Wills and Trusts services

