

Family trust management is the key to safeguarding your family’s future assets, ensuring they are protected and distributed according to your wishes. Here’s a quick summary to get you started:
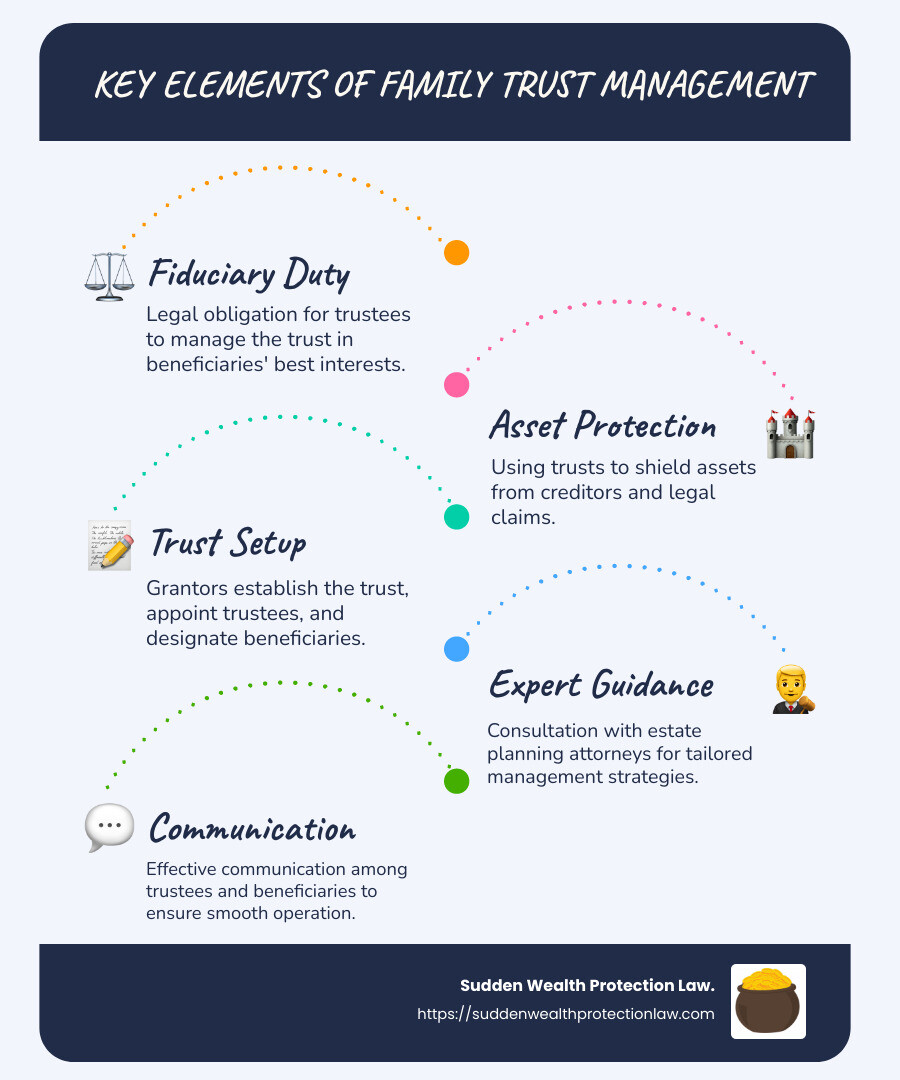
- Fiduciary Duty: Trustees have a legal obligation to manage the trust in the best interests of the beneficiaries.
- Asset Protection: Trusts can shield assets from creditors and legal claims, ensuring a smooth transfer of wealth.
- Trust Setup: Grantors establish the trust, appoint trustees, and designate beneficiaries to manage and benefit from the assets.
- Expert Guidance: Consult an experienced estate planning attorney for a custom strategy and seamless management.
I’m Paul E. Deloughery, founder of Sudden Wealth Protection Law in Phoenix, Arizona. With over 25 years in legal practice and experience in estate management, I specialize in family trust management to help individuals secure their legacies and avoid pitfalls.
Key Family trust management vocabulary:
– Arizona Estate Planning
– estate planning attorney chandler
– trust attorney mesa az
Understanding Family Trusts
Family trusts are like a safety net for your family’s assets, ensuring they are managed and distributed according to your wishes. Let’s break down the key components: trustee roles, beneficiary rights, and the trust document.
Trustee Roles
The trustee is the captain of the ship, steering the trust in the right direction. They have some crucial responsibilities:
- Integrity: Trustees must be honest and transparent. They need to act in the best interests of the beneficiaries.
- Impartiality: A good trustee balances the needs of all beneficiaries fairly, without favoritism.
- Financial Savvy: Managing a trust requires an understanding of investments and taxes. Trustees need to make wise decisions to grow and protect the assets.
Choosing the right trustee is critical. They are not just managing assets; they are upholding the grantor’s intent and ensuring the trust complies with legal and tax obligations.
Beneficiary Rights
Beneficiaries are the family members who benefit from the trust. They have several important rights:
- Right to Information: Beneficiaries should be informed about the trust’s terms and the assets it holds. They deserve regular updates from the trustee.
- Right to Distributions: They are entitled to receive distributions as outlined in the trust document. This could be income, periodic payments, or specific distributions based on milestones.
- Right to an Accounting: Beneficiaries can request an accounting of the trust’s activities to ensure transparency and that the trustee is fulfilling their duties.
Trust Document
The trust document is the blueprint for the trust. It outlines everything:
- Terms and Conditions: This includes how the assets should be managed and distributed.
- Roles and Responsibilities: It specifies who the trustee and beneficiaries are and their respective roles.
- Instructions for Asset Management: The document guides the trustee on how to handle investments, distributions, and other financial matters.
The trust document is essential for ensuring the trust operates smoothly and according to the grantor’s wishes. It provides the roadmap for all parties involved, ensuring clarity and understanding.
In the next section, we’ll dive into Family Trust Management Essentials, focusing on asset management, compliance, and communication strategies to ensure your family trust runs like a well-oiled machine.
Family Trust Management Essentials
Managing a family trust can feel like juggling a few different balls. But, with the right strategies, it can be handled smoothly and effectively. Let’s explore the essentials of Family Trust Management: asset management, compliance, and communication.
Choosing the Right Trustee
The trustee plays a pivotal role in managing a family trust. Picking the right trustee is like choosing the right captain for a ship. They need to steer the trust in the right direction.
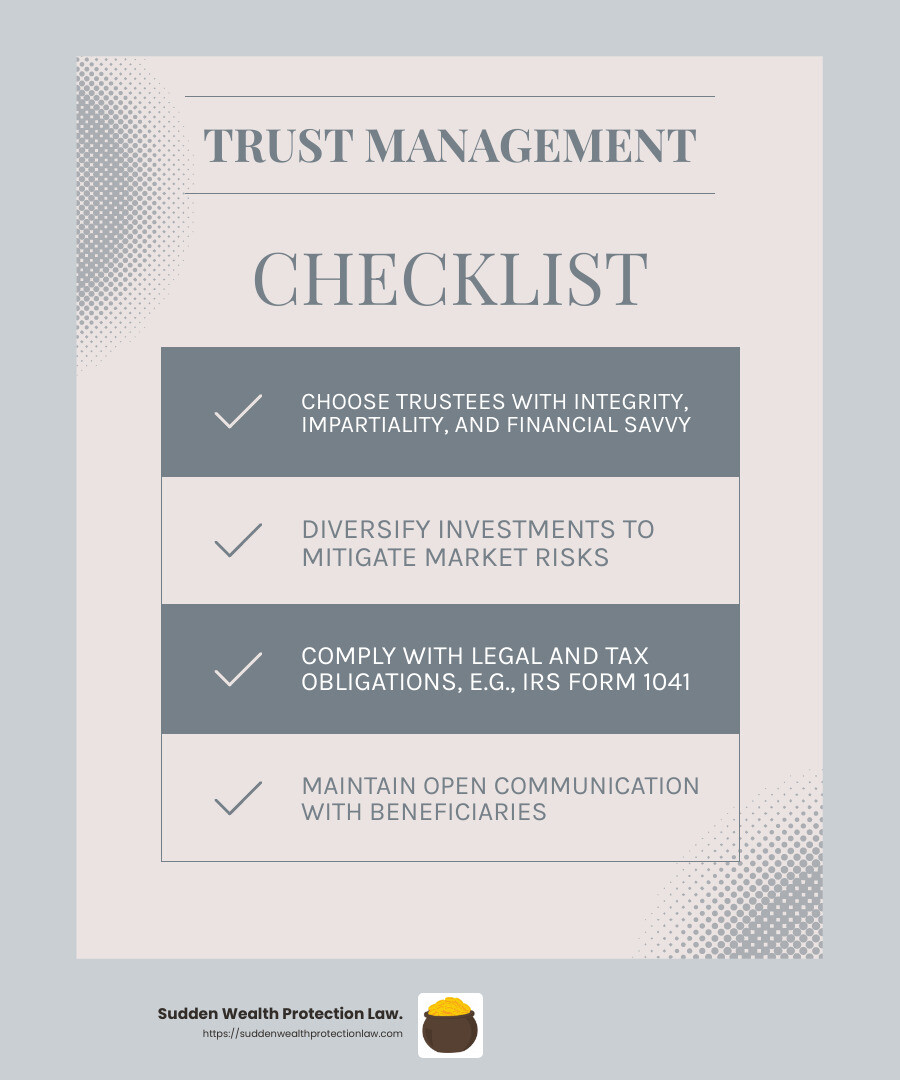
Integrity, impartiality, and financial savvy are key qualities for a trustee. They must act honestly, treat all beneficiaries fairly, and make smart financial decisions. Trustees should have a clear understanding of investments and taxes, ensuring the trust’s assets are managed wisely.
Sometimes, having more than one trustee, known as co-trustees, can be beneficial. It allows for multiple perspectives and shared decision-making, which can be a safeguard for the trust’s assets.
Asset Management Strategies
Asset management is at the heart of any trust. Trustees must focus on diversification, prudent investing, and risk management to protect and grow the trust’s assets.
- Diversification: This involves spreading investments across different asset classes to reduce risk. It’s like not putting all your eggs in one basket. By diversifying, trustees can protect the trust from market fluctuations.
- Prudent Investor: Trustees should adhere to the Uniform Prudent Investor Act (UPIA) guidelines. This means making investment decisions that a prudent person would make, focusing on both the safety and growth of the trust’s assets.
- Risk Management: Understanding and managing risks is crucial. Trustees must balance potential returns with possible risks, ensuring the trust’s long-term stability.
Compliance and Communication
Compliance is about following the rules. Trustees must ensure the trust complies with all legal and tax obligations. This includes filing necessary tax returns, like the IRS Form 1041, and adhering to state-specific regulations.
Communication is equally important. Keeping beneficiaries informed fosters trust and transparency. Trustees should provide regular updates on the trust’s status, including financial performance and any distributions made. Open communication can prevent misunderstandings and disputes.
By focusing on these essentials, trustees can manage a family trust effectively, ensuring it serves its purpose. In the following section, we’ll explore Legal and Tax Considerations, diving into the complexities of IRS guidelines and tax exemptions. Stay with us!
Legal and Tax Considerations
When it comes to Family Trust Management, navigating legal and tax considerations is critical. Let’s break down some key elements: IRS Form 1041, UPIA guidelines, and tax exemptions.
IRS Form 1041: The Trust’s Tax Return
Just like individuals file tax returns, trusts must also report their financial activities. This is done using IRS Form 1041. Think of it as the trust’s version of a personal tax return. It details the trust’s income, deductions, and any income distributed to beneficiaries.
- When to File: If a trust earns more than $600 in a year or has a nonresident alien as a beneficiary, filing Form 1041 is mandatory.
- What It Covers: The form reports income generated by trust assets, such as interest, dividends, and capital gains. It also accounts for deductions and distributions to beneficiaries.
Filing this form correctly is crucial to avoid penalties. Consulting with a tax professional who specializes in trusts can ensure compliance and accuracy.
UPIA Guidelines: Smart Investing
The Uniform Prudent Investor Act (UPIA) provides a framework for trustees to manage trust investments. It emphasizes a strategy of diversification and prudent investing.
- Diversification: The UPIA advises trustees to spread investments across various asset classes. This reduces risk, much like not putting all your eggs in one basket.
- Prudent Decisions: Trustees are encouraged to make investment choices that balance risk and return. They should consider the trust’s needs and the beneficiaries’ interests.
Trustees don’t need to be investment experts but should work with advisors who understand these guidelines.
Tax Exemptions: Reducing the Burden
Trusts enjoy certain tax exemptions, which can ease the financial load:
- Standard Deductions: Simple trusts can deduct $300, while estates can deduct $600 from their taxable income.
- Estate Tax Benefits: Trusts can help minimize estate taxes by utilizing gift and estate tax exemptions. This is particularly beneficial for married couples, who can double their exemptions.
Understanding these exemptions is vital for effective trust management. It allows trustees to maximize the trust’s value while minimizing tax liabilities.
By mastering these legal and tax considerations, trustees can ensure the trust operates smoothly and efficiently. Next, we’ll tackle the Challenges in Family Trust Management, exploring common problems and how to overcome them.
Challenges in Family Trust Management
Managing a family trust can be a rewarding yet challenging endeavor. Let’s explore some common problems: administrative costs, beneficiary disputes, and regulation complexity.
Administrative Costs: The Price of Peace of Mind
Running a family trust isn’t cheap. From legal fees to accounting services, the expenses can add up quickly.
- Legal Fees: Establishing a trust requires legal expertise, which comes with a price tag. Ongoing legal advice ensures compliance and can prevent costly mistakes.
- Accounting Services: Trusts need meticulous record-keeping. Filing tax returns and managing distributions are just a couple of the tasks that require professional attention.
To manage these costs, consider seeking cost-effective services without sacrificing quality. Sometimes investing in expert advice upfront can save money in the long run.
Beneficiary Disputes: Keeping the Peace
Not all beneficiaries will see eye to eye. Disputes can arise over how assets are distributed or how the trust is managed.
- Communication is Key: Clear communication can prevent misunderstandings. Regular updates and transparent decision-making help keep everyone informed.
- Mediation: When conflicts arise, mediation by a neutral third party can be invaluable. It helps find resolutions without resorting to costly litigation.
By fostering open dialogue and addressing concerns early, trustees can minimize family conflict and maintain harmony.
Regulation Complexity: Navigating the Maze
Trust laws are intricate, and managing a trust involves navigating a maze of regulations.
- Legal Compliance: Trustees must ensure the trust adheres to all relevant laws. This includes understanding tax obligations and investment guidelines.
- Staying Informed: Laws and regulations can change. Trustees should stay informed about legislative updates and seek advice from professionals who specialize in trust and estate law.
A proactive approach to regulation can prevent legal issues and ensure the trust operates smoothly.
By understanding these challenges and employing strategies to address them, trustees can manage family trusts with confidence. Up next, we’ll explore Frequently Asked Questions about Family Trust Management to further clarify common concerns and misconceptions.
Frequently Asked Questions about Family Trust Management
What is the downside of a family trust?
Family trusts can be incredibly beneficial, but they come with some downsides. The most significant is rigidity. Once a trust is set up, changing its terms can be difficult or even impossible. This inflexibility can become a problem if circumstances change, like new family dynamics or financial situations.
Another downside is the potential for family conflict. Disputes might arise over how assets are distributed or managed. Even with a clear trust document, disagreements can occur, especially if beneficiaries feel decisions aren’t fair.
How is a family trust managed?
Family trust management involves several key elements:
- Trustee Selection: Choosing the right trustee is crucial. This person (or institution) will manage the trust’s assets and make decisions according to the trust document. They should have integrity, be impartial, and possess sound financial judgment.
- Asset Distribution: The trustee is responsible for distributing assets to beneficiaries as outlined in the trust document. This requires careful attention to the settlor’s wishes and the needs of the beneficiaries.
- Communication: Keeping beneficiaries informed about the trust’s administration is essential. Regular updates and transparent decision-making help prevent misunderstandings and disputes.
Managing a trust effectively ensures it serves its intended purpose, safeguarding assets and supporting beneficiaries.
What is the 5-year rule for trusts?
The 5-year rule is important for individuals considering Medicaid. When applying for Medicaid, there’s a look-back period of five years. This means any assets transferred to a trust within five years before applying could affect eligibility.
For those aiming to qualify for Medicaid while preserving assets, it’s crucial to plan early. Assets transferred to an irrevocable trust before the 5-year window may not count against Medicaid eligibility.
Additionally, understanding the role of remainder beneficiaries is vital. These beneficiaries receive what’s left in the trust after the primary beneficiary’s needs are met. Planning for remainder beneficiaries can ensure the trust’s assets are used wisely and according to the settlor’s wishes.
Managing a family trust involves navigating these complexities, but with the right guidance, it can be a powerful tool for asset protection and family harmony. Up next, we’ll explore Conclusion to wrap up our insights on family trust management. Stay with us!
Conclusion
Navigating the complexities of family trust management can seem daunting, but with the right support, it becomes a rewarding endeavor. At Sudden Wealth Protection Law, we specialize in crafting personalized solutions that protect your family’s legacy while addressing unique needs and goals. Our approach ensures that your assets are safeguarded and that your wishes are honored.
Our commitment to personalized solutions means we tailor our services to fit your specific circumstances. Whether it’s selecting the right trustee or planning for tax implications, we offer expert guidance every step of the way. Our founding attorney, Paul Deloughery, believes in empowering families to make informed decisions that align with their values and long-term objectives.
One standout feature of our service is our unique asset protection strategy, which includes the innovative Asset Vault Trust. This irrevocable trust is designed to offer maximum asset protection while maintaining flexibility through a special power of appointment. This means you can adapt to changes in your family dynamics or financial situation without compromising on security.
We understand that managing a family trust is not just about financial transactions—it’s about preserving family values and ensuring peace of mind. Our compassionate and expert guidance helps you steer challenges, resolve disputes, and achieve favorable outcomes.
For those in Arizona seeking to protect their legacy and ensure seamless estate planning, we invite you to explore our estate planning services. Let us help you create a robust plan that secures your family’s future and honors your intentions. Together, we can ensure your trust fulfills its vital role for beneficiaries now and in the future.

