

Why Family Trusts Matter for Your Legacy
A family trust is a legal arrangement where you transfer assets to a trustee who manages them for the benefit of your family members. It provides a structured way to protect your wealth, avoid probate, and ensure your assets are distributed according to your wishes.
What is a Family Trust?
- Definition: A legal entity where assets are held by trustees for family beneficiaries
- Key Parties: Grantor/settlor (creator), trustee (manager), beneficiaries (recipients)
- Types: Revocable (can be changed) or irrevocable (permanent)
- Primary Benefits: Asset protection, probate avoidance, privacy, tax planning
- Cost: $1,000-$3,000 for basic setup; $3,000-$5,000+ for complex trusts
Family trusts serve many important purposes. They help you:
- Avoid probate – assets transfer directly to beneficiaries without court involvement
- Maintain privacy – unlike wills, trusts aren’t public record
- Protect assets from creditors and potential lawsuits
- Plan for incapacity by naming successor trustees
- Control distributions with specific terms for beneficiaries
- Potentially reduce estate taxes for larger estates
Setting up a family trust requires careful planning. While the initial cost ranges from $1,500 to $5,000 depending on complexity, the long-term benefits often outweigh this investment.
I’m Paul E. Deloughery, founder of Sudden Wealth Protection Law with over 25 years of experience helping Arizona families establish robust family trusts that protect their legacies and ensure smooth wealth transfers. My personal experience of inheriting and subsequently losing substantial wealth drives my passion for creating effective family trusts that truly protect what matters most.
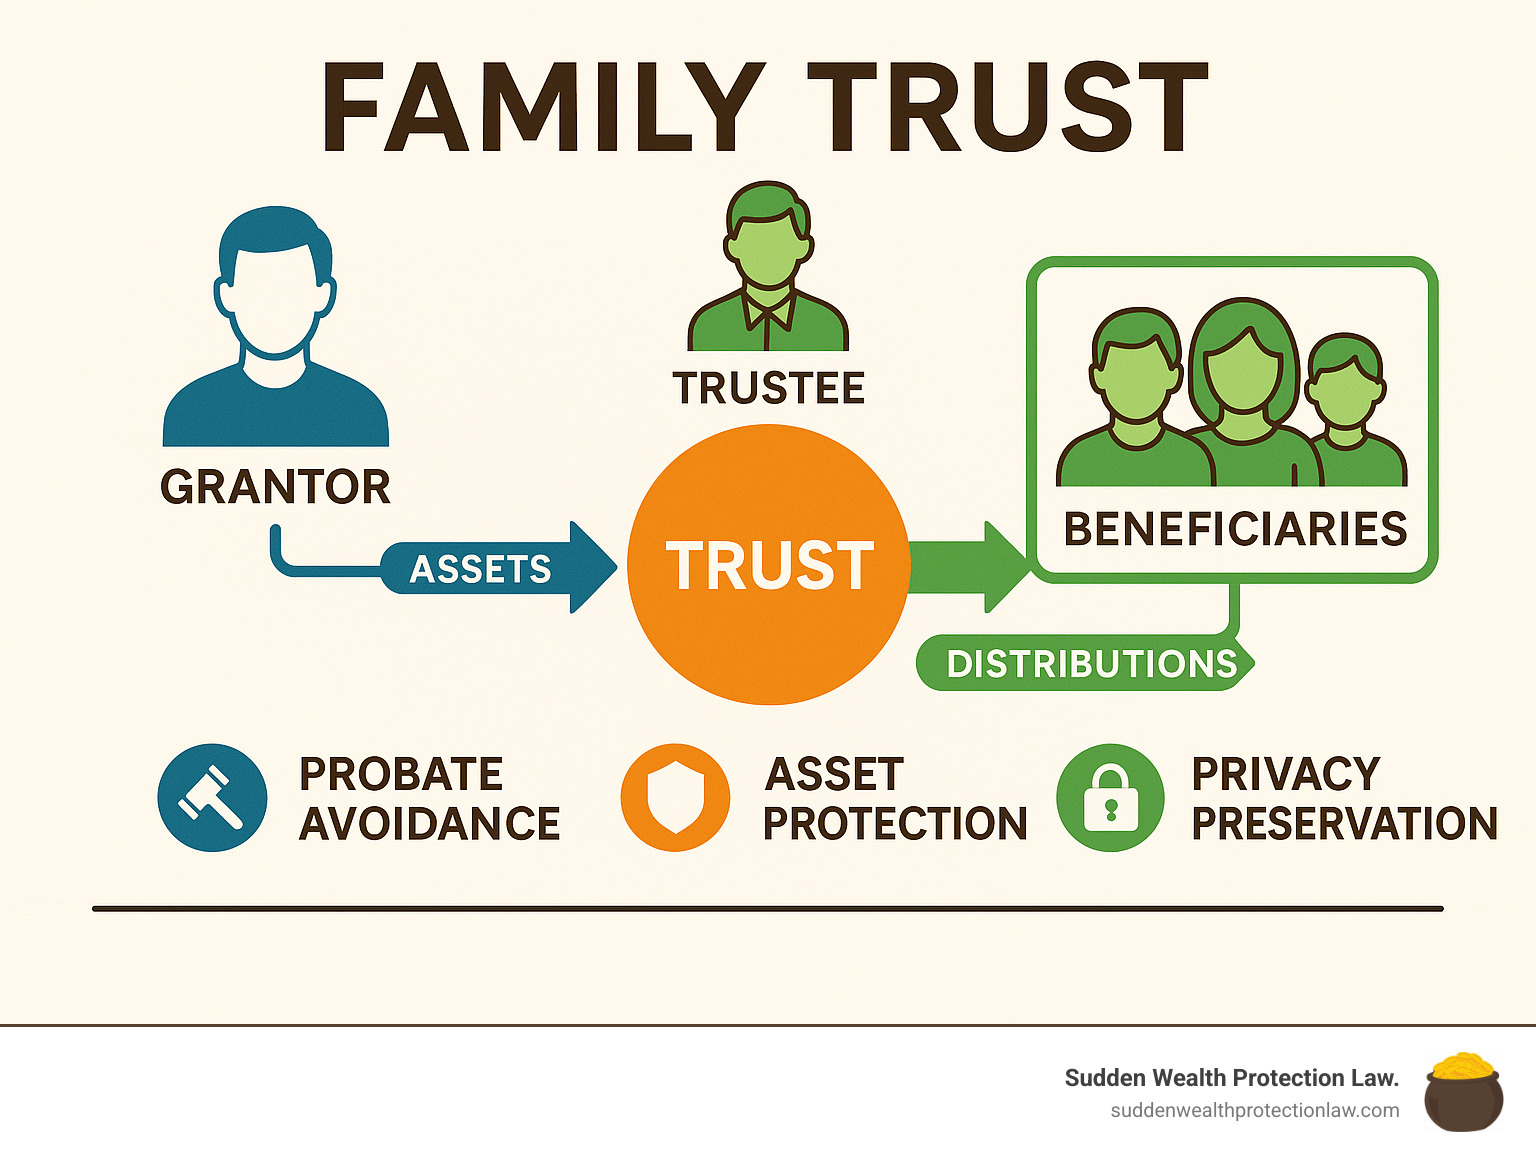
Understanding the Family Trust Basics
When you’re thinking about protecting your family’s future, a family trust can be a powerful tool in your estate planning toolkit. But what exactly is it, and how does it work? Let’s break it down in simple terms.
A family trust is essentially a legal arrangement where you place your assets (like your home, investments, or business) into a protected container. This container—the trust—is then managed according to your instructions, either by you initially or by someone you appoint.
Key Parties in a Family Trust
Think of a family trust as a play with three main characters:
First, there’s you—the grantor or settlor. You’re the director of this show, creating the trust and deciding what assets go into it. Here in Arizona, you might also hear yourself called the trustor or creator.
Second is the trustee—the person who manages everything in the trust. If you set up a revocable trust (one you can change), you can wear this hat too while you’re alive and well. It’s like being both the playwright and the lead actor.
Third are the beneficiaries—typically your family members who will receive benefits from the trust. They’re the audience the whole performance is for!
The Arizona Trust Code (found in Title 14, Chapter 10 of our state’s laws) spells out the rights and responsibilities for each role. Your trust document—sometimes called a trust deed or trust agreement—is like the script that explains how everyone should play their part.

Most family trusts in Arizona can last up to 90 years under something called the Rule Against Perpetuities. That’s a fancy way of saying your legacy can benefit your family for nearly a century!
How Does a Family Trust Work?
Your family trust springs to life once you sign the paperwork and start moving assets into it. Here’s what happens behind the scenes:
Funding the trust is like stocking your new safe with valuables. You’ll transfer ownership of your assets from your personal name into the trust’s name. This step is crucial—if you skip it, those assets won’t get the protection the trust offers.
Retitling assets means changing names on official documents. Your house deed, bank accounts, and investment statements will change from “Jane Smith” to something like “Jane Smith, Trustee of the Smith Family Trust dated March 15, 2023.”
One major benefit? Bypassing probate—that court-supervised process that can take 6-12 months in Arizona and cost your family thousands in legal fees. Assets properly placed in your trust skip this process entirely.
If you ever become unable to manage your affairs, your family trust provides protection during incapacity. Your chosen successor trustee can step in smoothly, without the need for costly court proceedings to appoint a conservator.
After your passing, your successor trustee will distribute your assets according to your wishes—privately and efficiently, without court involvement.
Key Roles Inside a Family Trust
The people involved in your trust have specific responsibilities that keep everything running smoothly:
Your trustee carries a fiduciary duty—a legal obligation to act in the best interests of your beneficiaries, not their own. This means they must invest wisely, keep accurate records, communicate regularly with beneficiaries, and follow your trust instructions to the letter. In Arizona, trustees who fail in these duties can be personally liable for any damages.
Choosing a successor trustee is perhaps your most important decision. This person will take over if you can’t serve as trustee anymore, either temporarily due to illness or permanently after death. Look for someone who’s trustworthy, financially responsible, good at communication, and actually willing to take on this important job—potentially for years.
Your beneficiaries have rights too. Under Arizona law, they’re entitled to information about the trust, accountings of trust assets, and can even petition the court if they believe the trustee isn’t doing their job properly.
For a deeper dive into the roles of trustees and trustors, check out our detailed guide on Trustee Versus Trustor.
A well-designed family trust isn’t just paperwork—it’s peace of mind, knowing you’ve created a roadmap for your family’s financial future that reflects your values and wishes.
Roles & Mechanics of a Family Trust
Now that we’ve covered the basics, let’s explore how assets actually flow through your family trust and what ongoing responsibilities come with it. Think of this as looking under the hood to see how the engine really works.
Asset Transfer: Moving Property Into Your Trust
Funding your family trust is a bit like moving into a new home – different items require different approaches:
For real estate in Arizona, we need to create and record a new deed with your county recorder’s office. If you own property in Maricopa County, we’ll prepare a deed that transfers ownership from your personal name to something like “John Smith, Trustee of the Smith Family Trust dated January 1, 2023.”
Your financial accounts require a different approach. You’ll need to contact each bank or investment company, complete their specific trust transfer forms, and provide what’s called a certificate of trust – a condensed version of your trust document that proves the trust exists without revealing all your private instructions.
Life insurance can be handled by naming your trust as a beneficiary on your policies. However, sometimes it makes more sense to create a separate irrevocable life insurance trust for tax or asset protection reasons.
Don’t forget your digital assets! In our increasingly online world, your cryptocurrency, social media accounts, and digital files need protection too. Arizona’s Revised Uniform Fiduciary Access to Digital Assets Act provides the legal framework for including these modern assets in your trust.
Business interests require special care when transferring to your trust. We’ll need to review operating agreements and potentially get consent from other owners to ensure the transfer doesn’t trigger any unwanted consequences.
Trustee Responsibilities: Ongoing Management
Once your family trust is up and running, the trustee’s job begins in earnest:
Keeping clear annual accounting records might seem optional when you’re serving as both trustee and beneficiary of your own revocable trust. But these records become absolutely essential when your trust becomes irrevocable or when a successor trustee takes over. Good habits now prevent headaches later.
Under Arizona law, trustees of irrevocable trusts generally must provide regular reports to qualified beneficiaries. Your trust document can modify these requirements, but transparency usually prevents problems down the road.
Trustees must also handle investment management according to the Arizona Uniform Prudent Investor Act. This doesn’t mean you need to become a financial wizard overnight, but it does mean being thoughtful about diversification and sometimes seeking professional investment advice.
As for taxes, your revocable living trust typically doesn’t need separate tax returns during your lifetime – everything flows through to your personal return. But irrevocable trusts often need their own tax ID number and annual filings.

Family Trust vs. Will – Which Tool Fits Best?
While both wills and family trusts direct how assets pass to heirs, they work very differently:
| Feature | Family Trust | Will |
|---|---|---|
| Privacy | Private document not made public | Becomes public record through probate |
| Probate | Assets avoid probate court | Assets must go through probate |
| When it takes effect | Can work during incapacity | Only works after death |
| Challenge difficulty | Harder to contest | Easier to contest |
| Cost to create | $1,500-$5,000+ | $300-$1,000 |
| Speed of distribution | Typically weeks | Months to years in probate |
| Incapacity planning | Built-in through successor trustee | Requires separate power of attorney |
For many Arizona families, the privacy and probate-avoidance benefits of a family trust outweigh the higher initial cost, especially for those with real estate or concerns about family disputes.
Updating a Family Trust Over Time
Your family trust isn’t meant to be a static document frozen in time. It should grow and change as your life does:
When you need to make specific changes, amendments allow you to modify particular provisions while leaving the rest intact. Think of these as surgical adjustments to your plan.
For more substantial changes, a complete restatement creates a fresh trust document incorporating all previous changes. This approach helps avoid a confusing patchwork of amendments that might contradict each other.
Life rarely stands still, and several events should trigger a trust review: marriage or divorce, births or deaths in the family, significant asset changes, relocating to another state, or major tax law changes. Each of these milestones represents an opportunity to ensure your trust still reflects your wishes.
Your choice of successor trustees deserves special attention during these reviews. The person you named ten years ago might no longer be in good health or close enough to handle the responsibility. Regular reviews ensure your management plan remains viable.
For more comprehensive information about keeping your estate plan current, visit our Estate Planning page.
Types of Family Trusts & Choosing the Right One
Not all family trusts are created equal. Different types serve different purposes, and choosing the right structure is crucial for achieving your specific goals.

Common Types of Family Trusts
The most common type of family trust is the Revocable Living Trust. Think of it as the “starter model” of trusts that gives you training wheels – you maintain complete control during your lifetime and can change or revoke it whenever you want. It helps you avoid probate while maintaining privacy and provides a plan for incapacity. The downside? Revocable trusts offer limited asset protection during your lifetime and no tax advantages.
When you’re ready for stronger protection, an Irrevocable Trust might be the answer. Once established, these trusts generally cannot be changed – which is both their strength and limitation. They offer stronger asset protection from creditors, potential estate tax benefits, and can protect beneficiaries with special needs. The tradeoff is clear: once assets go in, you typically can’t take them back.
For families concerned about a beneficiary’s financial responsibility, a Discretionary Trust gives the trustee decision-making power over when and how to distribute assets. This approach protects beneficiaries from their creditors, provides flexibility as circumstances change, and can help preserve eligibility for government benefits.
If you have a loved one with disabilities, a Special Needs Trust deserves serious consideration. These specialized trusts provide for supplemental needs while preserving eligibility for crucial government benefits like Medicaid and SSI, ensuring your loved one maintains their quality of life without losing essential support.
For beneficiaries who struggle with financial management, a Spendthrift Trust acts like financial guardrails. It protects them from their own poor spending habits, shields assets from creditors and predators, and can even provide protection during divorce proceedings.
Looking to create a multi-generational legacy? A Generation-Skipping Trust allows assets to pass to grandchildren or later generations, potentially reducing estate taxes across multiple generations while preserving wealth for your family’s future.
The Asset Vault Trust Advantage
At Sudden Wealth Protection Law, we specialize in a powerful hybrid solution called the Asset Vault Trust. This is our name for what is sometimes called a “541 Trust” (referring to Section 541 of the Bankruptcy Code).
The Asset Vault Trust combines the best of both worlds – the protective strength of irrevocable trusts with thoughtful flexibility for real-world needs:
Unlike traditional irrevocable trusts that lock assets away permanently, our Asset Vault Trust incorporates special powers of appointment that provide flexibility while maintaining asset protection. Think of it as having a lock box with a special key that only you can use under certain circumstances.
The lawsuit shield is perhaps its most valuable feature. Assets in the Asset Vault Trust can be protected from creditors, lawsuits, and predatory claims—protection that revocable trusts simply cannot provide. In today’s litigious society, this peace of mind is invaluable.
When properly structured, these trusts offer significant tax efficiency while allowing continued beneficial use of the assets. You don’t have to choose between protection and practical use of your wealth.
Through carefully crafted provisions, you maintain significant influence over trust assets without compromising their protected status. It’s protection without complete surrender of control.
The Asset Vault Trust represents the cutting edge of asset protection planning in Arizona, offering superior protection compared to traditional revocable living trusts. It’s the difference between a standard door lock and a sophisticated security system.
For more detailed information about this powerful trust structure, visit our Asset Vault Trust page.
When a Family Trust Makes Sense
A family trust is particularly valuable in certain situations, and recognizing when you need one is half the battle.
If you’re a high net worth individual with an estate approaching the federal estate tax exemption ($13.61 million in 2024), certain types of trusts can help minimize estate taxes. Why give the government more than necessary when those funds could benefit your family?
For blended families, trusts can ensure your assets benefit both your current spouse and children from previous relationships, preventing unintended disinheritance. They provide clarity and structure where family relationships can be complex.
Business owners find trusts invaluable for protecting their enterprise from personal creditors and ensuring smooth succession. Your life’s work deserves protection that matches the effort you’ve put into building it.
If you have minor children, trusts allow you to control how and when they receive their inheritance, potentially spreading distributions over many years as they mature and develop financial responsibility.
Disability planning becomes much more effective with trusts. Whether you have a child with special needs or are concerned about your own potential incapacity, trusts offer superior protection compared to other planning tools, ensuring care continues seamlessly.
For those with privacy concerns, trusts keep family matters out of the public probate process. In an age of information overexposure, maintaining family privacy is increasingly valuable.
At Sudden Wealth Protection Law, we understand that each family’s situation is unique. We take the time to understand your specific needs and goals before recommending the right trust structure for your situation. After all, the best protection is the one that’s perfectly custom to your family’s circumstances.
Pros, Cons & Cost Breakdown
When considering a family trust, it’s important to weigh both the benefits and potential drawbacks. Like any important financial decision, understanding the full picture helps you determine if this path aligns with your family’s unique needs.
Advantages of Family Trusts
Creating a family trust offers several compelling benefits that make it worth considering. For many Arizona families, asset protection stands out as a primary advantage—particularly with irrevocable structures like our Asset Vault Trust, which can shield your hard-earned wealth from creditors and unexpected lawsuits.
Tax planning represents another significant benefit. While the current federal estate tax exemption sits at a generous $13.61 million per individual in 2024, proper trust structures can still provide meaningful tax advantages for larger estates. The IRS provides detailed guidance on minimizing estate taxes for those whose estates approach or exceed these thresholds.
One of the most appreciated benefits is probate avoidance. Assets properly titled in your family trust bypass the time-consuming and often expensive probate process entirely. This means your loved ones gain access to needed resources in weeks rather than months or years.
Privacy protection is another compelling reason many Arizona families choose trusts. Unlike wills, which become public record during probate, your family trust keeps your financial affairs and distribution wishes completely private—something increasingly valuable in our digital age.
Disadvantages and Considerations
Of course, family trusts aren’t without their considerations. The initial setup costs typically range from $1,500 to $5,000 depending on complexity—a meaningful investment that reflects the customized legal work involved. At Sudden Wealth Protection Law, we view this as an investment rather than an expense, but it’s still important to account for in your planning.
Ongoing maintenance requires attention as well. Depending on your trust type, you might face accounting needs, tax preparation, and potentially trustee fees if you choose professional management. Irrevocable trusts face compressed tax brackets, reaching the highest rates at much lower income thresholds than individual taxpayers.
Some people hesitate about the perceived loss of control, particularly with irrevocable trusts. However, our Asset Vault Trust addresses this concern by incorporating special powers of appointment that maintain flexibility while preserving asset protection benefits.
The complexity factor shouldn’t be overlooked either. Family trusts require more ongoing attention and proper maintenance than simpler estate planning tools—though with proper guidance, this complexity becomes manageable.

Common Mistakes to Avoid in a Family Trust
In my 25+ years helping Arizona families, I’ve witnessed several recurring mistakes that undermine even well-intentioned trust planning. The most prevalent is what I call “funding gaps”—failing to properly transfer assets into your trust. Your beautiful trust document provides zero benefit for assets not actually titled in the trust’s name.
Choosing the wrong trustee creates another common pitfall. Your college roommate might be your best friend, but if they lack financial acumen or live across the country, they might not be your best trustee choice. The right trustee needs time, ability, and the temperament to serve effectively.
Life changes quickly, but trust documents don’t update themselves. Outdated beneficiary designations after births, deaths, marriages or divorces can create unintended consequences that directly contradict your current wishes. Regular reviews help prevent these situations.
Another oversight I frequently encounter is failing to name sufficient successor trustees. Without named backups, your carefully crafted family trust might end up in court if your initial trustee cannot serve—defeating much of the trust’s purpose.
Lastly, proper documentation matters tremendously. Poor record-keeping of trust assets and transactions creates confusion and potential liability issues for trustees, especially after you’re no longer available to answer questions.
Real Costs: What to Expect
Let’s talk dollars and cents. Creating and maintaining a family trust involves both initial and ongoing costs:
For initial setup, DIY software options exist in the $100-$500 range, though I generally don’t recommend this approach for most situations given the potential for costly mistakes. Attorney-drafted basic trusts typically range from $1,500-$3,000, while more complex estate plans with multiple trusts might run $3,000-$5,000 or more, depending on your specific situation.
Ongoing costs vary based on your trust type and complexity. Annual accounting might cost $500-$1,500, professional trustee fees typically run 1-2% of trust assets annually, and tax preparation for irrevocable trusts generally costs $500-$1,000 each year.
While these figures might seem substantial, they’re best viewed in context. Consider them against potential alternatives: probate costs (often 3-5% of your estate’s value), litigation among family members (potentially tens of thousands in legal fees), or estate taxes (up to 40% of your taxable estate).
At Sudden Wealth Protection Law, we believe in transparent pricing that reflects the value of proper planning. We’ve seen how quality trust planning provides peace of mind that far outweighs the investment—and how cutting corners often proves far more expensive in the long run.
Professional guidance throughout this process ensures your family trust accomplishes exactly what you intend, without expensive surprises down the road. Like most important things in life, doing it right the first time creates the best outcome for everyone involved.
Setting Up & Maintaining a Family Trust in Arizona
Creating a family trust in Arizona isn’t just about signing some papers—it’s about building a legal framework that protects your family’s future according to our state’s specific laws.
Arizona-Specific Requirements
Here in Arizona, we have our own set of rules that govern trusts. The Arizona Trust Code (found in Title 14, Chapter 10 of the Arizona Revised Statutes) provides the legal foundation for how trusts work in our state.
When you create a family trust in Arizona, the law (specifically A.R.S. § 14-10402) gives you several ways to establish it. You can transfer property to someone else to serve as trustee, declare yourself as trustee of your own property, or exercise a power of appointment in favor of a trustee.
While Arizona doesn’t strictly require notarization for your trust document to be valid, I strongly recommend having it notarized anyway. This extra step prevents questions about authenticity and is often necessary when transferring real estate into your trust.
Arizona’s community property laws add another layer to consider. As a community property state, most assets acquired during marriage are equally owned by both spouses. This affects how we title property in your family trust and ensures we’re respecting both spouses’ ownership rights.
For real estate, you’ll need to record a new deed with your county recorder’s office. In Maricopa County, for example, this means preparing a deed that transfers ownership from your name personally to your name as trustee of your family trust.
Step-by-Step: Creating Your Family Trust
Creating your family trust in Arizona involves several key steps that transform your wishes into a legally binding arrangement:
First, you’ll need to choose the right trust type for your situation. For many families, a revocable living trust provides the right balance of control and probate avoidance. If asset protection is a priority, our Asset Vault Trust might be more appropriate.
Next, we’ll draft your trust document. This isn’t something to attempt on your own—working with an experienced Arizona estate planning attorney ensures your trust addresses crucial elements like trustee powers, beneficiary rights, and special provisions for unique situations like minor children or beneficiaries with special needs.
When it’s time to execute your trust, you’ll sign it in compliance with A.R.S. § 14-10105. While Arizona doesn’t require witnesses for most trusts, having your signature notarized adds an important layer of authenticity and helps prevent challenges later.
The most commonly overlooked step is funding your trust. This means actually transferring your assets into the trust by recording new deeds, changing account titles at banks and investment firms, and updating ownership records. A trust without assets is like a car without an engine—it simply won’t work when needed.
Don’t forget to update beneficiary designations on assets like life insurance and retirement accounts. These typically pass outside your trust based on their beneficiary forms, so coordination is essential.
Finally, maintain good records of everything transferred into your trust and any changes made over time. This documentation will be invaluable to your successor trustee.
Administering the Trust After Death
When a trust creator passes away, their family trust enters a new phase that requires careful attention from the successor trustee:
The first significant change is that a revocable trust automatically becomes irrevocable at death. This means its terms are now fixed and generally cannot be altered.
The successor trustee must then identify and inventory all trust assets. This often involves gathering statements, deeds, titles, and other documentation to create a complete picture of what the trust owns.
Next comes addressing financial obligations. The trustee must pay legitimate debts, expenses, and taxes from the trust assets. This might include final medical bills, funeral expenses, outstanding loans, and any estate or income taxes due.
Following the trust’s instructions, the trustee develops a distribution plan for transferring assets to beneficiaries. This plan must carefully balance the trust’s terms, beneficiary needs, tax implications, and practical considerations.
The trustee then transfers assets to beneficiaries according to the trust’s terms. This might happen as a single distribution or over time, depending on how the trust was designed.
Once all distributions are complete and obligations fulfilled, the trustee can formally close the trust by providing final accountings to beneficiaries and completing any required paperwork. Some trusts, however, are designed to continue for multiple generations.
Trust administration can feel overwhelming, especially while grieving. At Sudden Wealth Protection Law, we provide compassionate guidance to successor trustees, helping them fulfill their duties with confidence and care.
For more detailed information about navigating the trust administration process, visit our Trust Administration for Dummies page.
Frequently Asked Questions About Family Trusts
How long can a family trust last in Arizona?
Wondering about the lifespan of your family trust? In Arizona, most trusts follow the Rule Against Perpetuities, which traditionally limited trusts to around 90 years. But good news – Arizona law now allows certain trusts to continue for up to 500 years under specific conditions.
For most families, though, we typically design trusts with more practical timeframes. Your trust might last for your beneficiary’s lifetime or until they reach certain milestone ages that you specify (like 25, 30, or 35). This approach balances long-term protection with practical distribution timelines that match your family’s needs.
The right duration depends entirely on your goals. Are you looking to provide lifetime support for a loved one with special needs? Or do you want to help your grandchildren through college before distributing assets? We can tailor the timeframe to match your family’s unique situation.
Can I put my home and business into the same family trust?
Yes, you absolutely can include both your home and business interests in the same family trust. Many of our clients do exactly this for simplicity. However, there are some important considerations to keep in mind:
For business interests, you’ll need to review any operating agreements, bylaws, or shareholder agreements to ensure they don’t restrict transfers to a trust. Some business documents require approval from other owners before making such transfers.
When it comes to your home, placing it in a trust typically won’t affect your ability to live there, but it’s worth checking that the transfer doesn’t impact your homestead exemption or trigger any due-on-sale clause in your mortgage.
In some situations—particularly for substantial assets or when maximum protection is the goal—creating separate trusts might make more sense. For instance, an Asset Vault Trust might be ideal for business interests while a revocable living trust handles your residence.
At Sudden Wealth Protection Law, we look at your complete asset picture before recommending the optimal structure that protects everything you’ve worked so hard to build.
What taxes will the trust pay each year?
Tax treatment is one of the most common questions we hear about family trusts, and it varies significantly depending on what type of trust you establish:
With a Revocable Living Trust (the most common type), there’s good news on the tax front. During your lifetime, this trust is considered a “grantor trust” for tax purposes. This means you don’t need to file a separate tax return for the trust—all income simply flows through to your personal tax return. You’ll continue using your Social Security number for trust accounts, making tax time relatively straightforward.
For Irrevocable Trusts like our Asset Vault Trust, the tax picture changes. These trusts typically need:
– Their own tax identification number (EIN) from the IRS
– Annual filing of Form 1041 (the trust income tax return)
– Payment of taxes on income that remains in the trust
One important consideration: trust tax rates reach the highest brackets much faster than individual rates. In 2023, trusts hit the top tax bracket at just $14,450 of income, compared to $578,125 for individuals.
The Asset Vault Trust we offer at Sudden Wealth Protection Law can be structured in various ways for tax purposes. Depending on your goals, we can design it to be treated as a grantor trust for income tax purposes (flowing through to your personal return) while still providing robust asset protection benefits.
Tax planning for trusts can get complex, which is why we recommend working with both our experienced estate planning team and your tax professional. Together, we can ensure your trust is structured to optimize tax benefits while achieving your protection goals.
The right trust structure isn’t just about avoiding probate—it’s about creating a comprehensive plan that addresses taxes, asset protection, and family legacy in one cohesive strategy.
Conclusion
Creating a family trust is one of the most powerful ways to protect your family’s future. It’s not just paperwork—it’s peace of mind, knowing you’ve taken concrete steps to safeguard what you’ve built and ensure it benefits those you love most.
Throughout this guide, we’ve explored how family trusts can help you avoid probate, maintain privacy, protect assets from creditors, and create a lasting legacy that reflects your values. Whether you’re concerned about estate taxes, have a blended family, own a business, or simply want the smoothest possible transition of wealth to your loved ones, the right trust structure can make all the difference.
At Sudden Wealth Protection Law, we understand that each family’s situation is unique. That’s why we don’t offer one-size-fits-all solutions. Instead, we work closely with you to design a personalized strategy that addresses your specific concerns and goals. Our Asset Vault Trust offers superior protection compared to traditional revocable living trusts, combining the security benefits of irrevocable trusts with carefully crafted flexibility that allows you to maintain appropriate control.
I’ve seen how proper trust planning can prevent family conflicts, protect vulnerable beneficiaries, and ensure your hard-earned assets don’t end up in the wrong hands. I’ve also witnessed the complications and heartache that can arise when these important decisions are postponed or overlooked.
Estate planning might seem overwhelming at first, but it doesn’t have to be. With compassionate, expert guidance, you can understand every aspect of your plan and feel confident in the protection it provides. The initial investment of time and resources in creating a proper family trust pays dividends for generations to come.
Your family’s financial security is simply too important to leave to chance. Whether you’re just starting to think about estate planning or need to update existing documents, we’re here to help you create a plan that protects what matters most.
To learn more about how we can help you create a comprehensive estate plan that includes the right family trust for your situation, visit our page on Wills and Trusts or contact our Phoenix office to schedule a consultation.
The greatest gift you can give your family isn’t just financial assets—it’s the security of knowing those assets are protected and will be distributed according to your wishes, with minimal complications and maximum benefit to those you love.

