

Why Financial Abuse of Vulnerable Adults Is Arizona’s Hidden Crisis
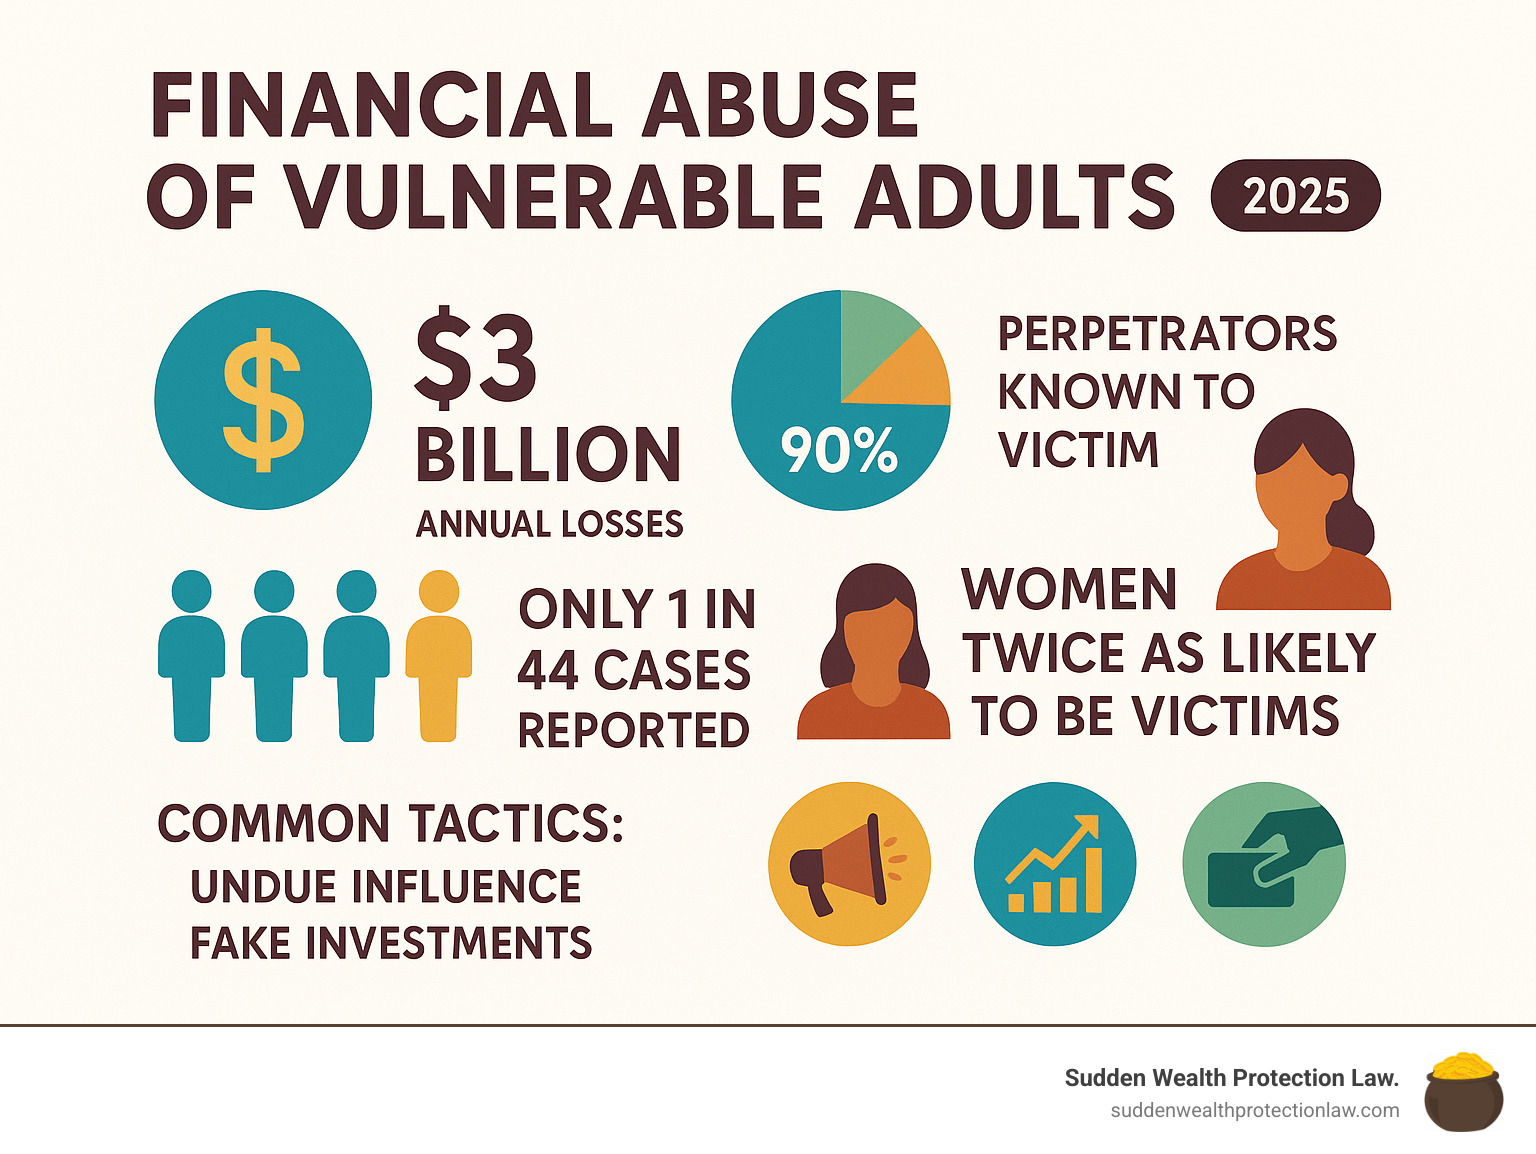
Financial abuse of vulnerable adults is a quiet, devastating crime that costs victims nationwide an estimated $3 billion annually. It’s when someone illegally or improperly uses a vulnerable person’s money or assets for their own gain—often through coercion, fraud, or undue influence.
Here’s the brutal truth: while families worry about strangers, the real threat often comes from within. A staggering 90% of perpetrators are family members, caregivers, or other trusted individuals. This is the adult child pressuring a parent for a “loan” that’s never repaid, the caregiver who gains control of a bank account, or the new “friend” who appears just as an inheritance does.
The damage isn’t just financial. Victims lose their independence and emotional well-being, and families are torn apart by legal battles that could have been prevented. Worse, only 1 in 44 cases is ever reported, leaving countless victims to suffer in silence.
I’m Paul E. Deloughery. In my 25 years of practicing law, I’ve seen this type of exploitation destroy families faster than any probate dispute. After losing a significant inheritance myself, I’ve dedicated my practice to helping Arizona families protect their wealth from this hidden crisis.
What Is Financial Abuse of Vulnerable Adults?
The uncomfortable truth about financial abuse of vulnerable adults is that it’s rarely a smash-and-grab. It’s the slow, methodical exploitation of trust. It happens when someone in a position of power—a family member, caregiver, or friend—improperly uses another person’s money or property for their own benefit. We’re talking about draining savings accounts, selling property without permission, or manipulating someone into changing their will.
The victims are typically elderly, cognitively impaired, or physically dependent on others. They are chosen because they are less likely to notice, report, or be believed. This crime costs victims an estimated $3 billion annually in the U.S., with women facing nearly double the risk. What’s heartbreaking is that 90% of perpetrators are people the victim knows and trusts.
Common Tactics in Financial Abuse of Vulnerable Adults
These predators use refined methods.
- Undue Influence: This is more effective than brute force. They isolate the victim, create dependency, and then gradually take control of financial decisions. A son “helping” with bills slowly redirects funds to his own accounts.
- Fake Investment Schemes: A scammer posing as a financial advisor promises incredible returns on non-existent investments, preying on the victim’s desire to leave a legacy.
- Sweetheart Scams: A lonely person is showered with attention by a new “partner” who soon develops expensive emergencies requiring immediate cash. The romance is fake, but the financial devastation is real.
- Caregiver Theft: The person trusted with daily care overcharges for services, forges signatures, or simply helps themselves to valuables, knowing the victim is too dependent to report them.
Why Financial Abuse of Vulnerable Adults Often Goes Unreported
Only 1 in 44 cases of financial elder abuse ever gets reported. Victims suffer in silence for several reasons:
- Shame and Embarrassment: No one wants to admit they were fooled, fearing they’ll be seen as mentally incompetent and lose their independence.
- Dependence on the Abuser: If your child is stealing from you but also drives you to doctor’s appointments, reporting them feels impossible. You risk losing essential support, however toxic it may be.
- Cognitive Decline: Victims may not fully understand what’s happening or may be unable to recall key details, making it difficult to build a case.
- Fear of Retaliation: Victims worry about neglect, anger, or even physical harm if they speak up. They fear being forced into a nursing home if the abuse becomes public.
Spotting the Red Flags Early
If you’re worried about a loved one, you need to know what to look for. The signs are often subtle shifts and things that just don’t add up.

You know your loved one’s habits. When sudden, unexplained financial changes appear, your alarm bells should ring. Look for:
- Large, nonsensical withdrawals from bank accounts.
- Bills going unpaid despite sufficient funds.
- New credit cards or loans your loved one doesn’t recall opening.
- New names added to existing bank accounts without a clear reason.
- Signature discrepancies on checks or legal documents. A shaky or completely different signature is a massive red flag.
- Abrupt changes to legal documents, like a will suddenly favoring a new acquaintance or property deeds being transferred without family knowledge.
The personality shifts are just as telling. A once-social parent becomes withdrawn and secretive about money. This often happens because they’re being deliberately isolated by a manipulator. Also, watch for missing possessions and payments for unnecessary services from a “handyman” or “advisor” who is constantly around.
Behavioral Clues Family Members Miss
Sometimes the most telling signs are behavioral, and they’re easy to miss when you want to trust people.
The “new best friend” is the biggest red flag I see families ignore. This person becomes indispensable, quickly gaining trust while systematically isolating your loved one from others to make manipulation easier.
Pay attention to control over communication. Does someone else always answer the phone? Is it impossible to speak privately with your loved one? This isn’t helpfulness; it’s a barrier.
Watch for unexplained “loans” or gifts from your family member to a new friend or caregiver. When a cautious person starts writing large checks to someone they barely know, it’s likely coercion disguised as kindness.
The most heartbreaking clue is fear or anxiety around a specific person. If your loved one seems nervous or quiet when someone is present or mentioned, trust your gut. They may be afraid to speak up due to threats or intimidation. If something feels wrong, it probably is.
Legal Tools to Stop the Bleeding (Arizona Focus)
When you find financial abuse of vulnerable adults, time is your enemy. Every day you wait, more assets can vanish. The good news is that Arizona law provides powerful tools to fight back.
Your first step is to call Arizona Adult Protective Services (APS) at 1-877-SOS-ADULT. They are the emergency responders for elder abuse. They will screen your report and, if appropriate, launch an investigation. It’s a critical first step for official documentation.
But APS is just the beginning. To stop the bleeding and recover stolen assets, we can deploy several legal strategies:
- Fiduciary Litigation: When a person in a position of trust—like an agent under a Power of Attorney or a guardian—misuses funds, we can haul them into court, force an accounting of every penny, and have them removed.
- Revoking a Power of Attorney (POA): If the victim has the mental capacity, they can revoke a POA. If not, we can seek a court order to terminate the agent’s authority.
- Conservatorship: We can ask the court to appoint a responsible person (a conservator) to manage the victim’s financial affairs. This puts a financial bodyguard in place, supervised by the court. A POA is granted by the individual with little oversight; a conservatorship is court-ordered and comes with built-in supervision from day one.
- Emergency Injunctions: To act fast, we can get a temporary restraining order to freeze bank accounts, halt property transfers, and prohibit the abuser from contacting the victim. It’s financial CPR.
For more information on the legal framework, the Department of Justice offers Scientific research on elder exploitation.
Legal Remedies for Financial Abuse of Vulnerable Adults in Arizona
Once abuse is proven, Arizona law has serious consequences for perpetrators.
Under Arizona Revised Statutes §46-456, financial exploitation of a vulnerable adult is a felony. This means potential jail time, hefty fines, and a permanent criminal record for the abuser.
While criminal prosecution brings a certain satisfaction, it doesn’t always get the money back. That’s where civil lawsuits come in. We can sue the perpetrator to recover stolen assets and, in some cases, pursue treble damages—an award of three times the actual damages. This is about making the victim whole and punishing the abuser.
Arizona’s mandatory reporting laws also require professionals like bankers, doctors, and lawyers to report suspected abuse to APS or law enforcement. Finally, a court can disinherit an abuser, ensuring they don’t profit from the person they victimized. The message is clear: Arizona does not tolerate those who prey on the vulnerable.
How to Report and Recovery
You’ve spotted the red flags. Now you must act. Hesitation is the abuser’s best friend.
When facing financial abuse of vulnerable adults, every day counts.
If your loved one is in immediate danger, call 911 first.
Otherwise, your first call should be to Arizona Adult Protective Services at 1-877-SOS-ADULT. Be ready to provide names, dates, dollar amounts, and any relevant health issues.
While APS investigates, you must move on other fronts. Contact your loved one’s bank and investment firms. Most have protocols for suspected elder abuse and can place temporary holds on accounts. Also, file a report with your local police department to initiate a parallel criminal investigation.
Recovery isn’t just about stopping the abuse; it’s about getting the money back. This often requires a civil lawsuit and forensic accounting to trace every dollar and build a bulletproof case for restitution.
For more resources, visit the National Adult Protective Services Association at More info about APS resources.
Step-by-Step Reporting Checklist
When you report the abuse, be prepared. You are building a case.
- Document Everything: Gather bank statements, copies of forged documents, emails, and photos of missing valuables. Create a timeline of events.
- Gather Victim’s Information: Have their full name, address, date of birth, and a summary of their health conditions ready.
- Identify the Suspected Abuser: Provide their name, relationship to the victim, and level of access to finances.
- Be Specific: Don’t just say “money is missing.” Say, “$5,000 was withdrawn from savings on March 15th, and the signature on the slip is a forgery.”
- Freeze Accounts: Work with financial institutions to place holds on suspicious accounts and transactions immediately.
- Call an Experienced Attorney: APS and the police handle safety and criminal charges, but a lawyer focused on elder law is essential for recovering stolen assets through civil litigation. They can also seek emergency court orders to freeze assets before they disappear forever.
Preventive Strategies for Families & Professionals
Financial abuse of vulnerable adults is like a house fire: by the time you smell smoke, the damage is done. Smart families build firewalls before they’re needed. Prevention requires common sense and a willingness to have uncomfortable conversations.
Start with open communication. Secrecy is an abuser’s best friend. Talk about finances and common scams. Many older adults grew up in a more trusting era and don’t recognize today’s sophisticated schemes. Explain the “grandparent scam” (a grandchild supposedly needs bail money) and tech support scams. Make sure they know the IRS will never call demanding payment via gift cards.
Build a network of oversight. Don’t put all financial responsibilities in one person’s hands, even a trusted family member.
- Trusted Contacts: Designate a trusted person at financial institutions to receive alerts for unusual activity, like large withdrawals or international wire transfers.
- Regular Monitoring: Set up automatic transaction alerts. If your loved one isn’t tech-savvy, ask to be added to receive duplicate paper or electronic statements. You’re not controlling their money; you’re acting as a second set of eyes.
- Durable Power of Attorney Safeguards: When creating a POA, build in checks and balances. Require the agent to provide regular financial reports to another family member or a professional. Consider naming co-agents who must act together for major decisions.
- Background Checks: If you hire professional caregivers, verify their references and run a background check. Do the same for any new financial advisors or accountants.
The bottom line is that financial abuse thrives in isolation. By creating transparency and oversight, you can protect your loved ones before a crisis occurs.
Frequently Asked Questions about Financial Abuse of Vulnerable Adults
These are the questions that keep families up at night. After 25 years in this field, I’ve heard them all. Here are the straight answers.
How quickly must I act once I suspect exploitation?
Immediately. The clock starts ticking the second you suspect something is wrong. Financial abuse of vulnerable adults is not a problem that gets better with time. Every day you hesitate is another day for an abuser to drain accounts, transfer property, or destroy evidence. Don’t spend weeks “gathering more evidence.” Act on your gut instinct. Call Adult Protective Services, notify law enforcement, and get an attorney involved right away.
Can a revoked Power of Attorney still cause damage?
Absolutely. Revoking a Power of Attorney is just the first step. Until you notify every financial institution in writing, the former agent can still walk into a bank with their old paperwork and clean out an account. Proper revocation requires proactive, aggressive notification. You must inform all banks and businesses, change online passwords, and cancel credit cards. Simply signing a piece of paper isn’t enough to protect the assets.
What if the perpetrator is another family member?
This is the most common and heartbreaking scenario. About 90% of this abuse is committed by family or other trusted individuals. But here’s the hard truth: blood is not a license to steal. The law doesn’t care about family dynamics when it comes to protecting a vulnerable person. I’ve seen cases where children had to take legal action against their own siblings to stop the theft. It’s a gut-wrenching choice, but the alternative—standing by while your loved one loses everything they worked for—is far worse. Arizona law provides strong remedies, including treble damages in civil court. Sometimes, the only way to stop the abuse is to make it clear there are severe financial consequences.
Conclusion
The hard truth is that financial abuse of vulnerable adults will continue to devastate Arizona families until we confront it head-on. The annual losses, estimated at $3 billion, aren’t just statistics; they represent real people losing their security, independence, and dignity.
In my 25 years of practice, I’ve learned that families who plan ahead and remain vigilant can protect what matters most. The legal tools exist, and the laws are on your side, but you must act before the crisis hits. Small steps today—like setting up oversight for a Power of Attorney or having frank conversations about money—can prevent massive heartache tomorrow.
If you already see red flags, don’t wait. Every hour matters when a lifetime of savings is at stake. Your loved one deserves to age with dignity, not at the mercy of a predator. Protecting their assets is about preserving their peace of mind—and yours.
If you suspect financial abuse or want to build stronger protections for a vulnerable family member in Arizona, we’re here to help. Sometimes the most loving thing you can do is also the hardest: standing up to an abuser, even if they share your last name.
More info about elder financial exploitation services

