

Why ILIT Trust Administration Can Make or Break Your Estate Plan
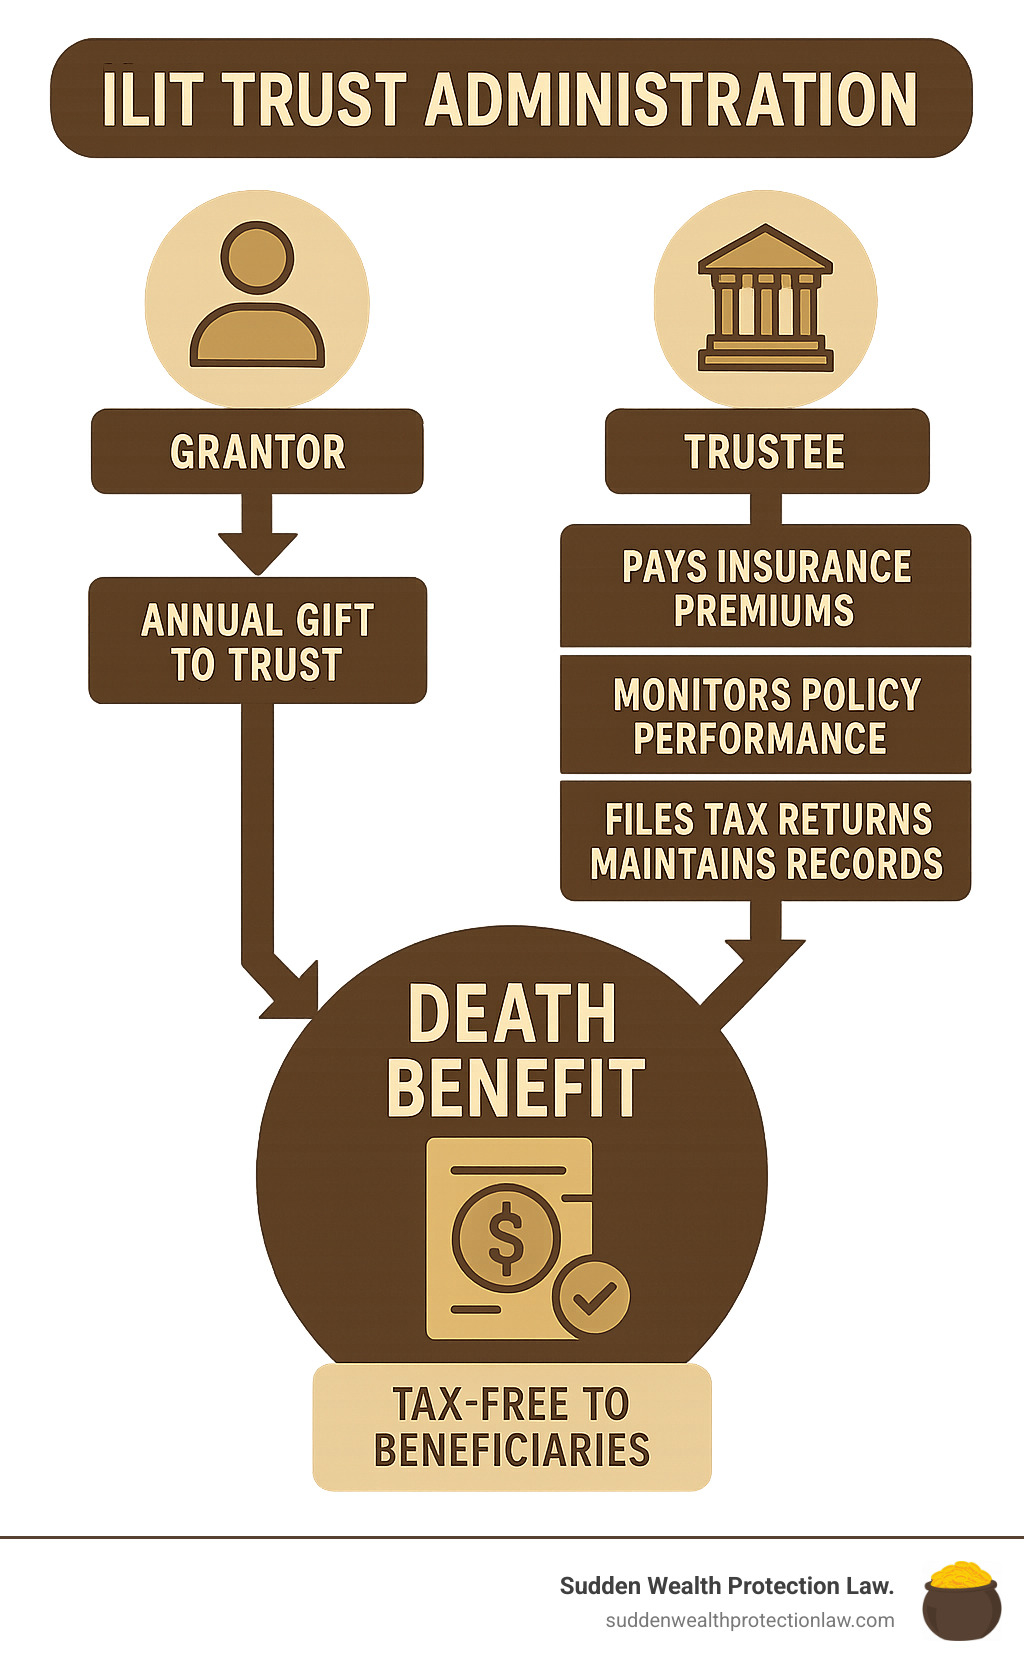
ILIT trust administration is the ongoing management and oversight of an Irrevocable Life Insurance Trust after it’s established. Here’s what you need to know:
Key ILIT Administration Tasks:
- Send annual Crummey notices to beneficiaries
- Make timely premium payments to keep policies active
- Monitor insurance policy performance and carrier financial strength
- File required tax returns (Forms 709, 1041)
- Maintain detailed records of all trust transactions
- Ensure compliance with gift tax exclusion limits
- Review and potentially remediate underperforming policies
You’ve drafted the perfect Irrevocable Life Insurance Trust. The client signed off, everyone’s happy, and you think the job is done.
Wrong.
The real danger starts after you close the file. An ILIT isn’t some dusty document that sits in a safe deposit box. It’s a financial weapon that requires constant maintenance, and when that maintenance fails, the explosion is spectacular.
I’ve seen it happen too many times. A well-meaning family member takes over as trustee, skips a few Crummey notices, lets a premium slide, and suddenly a $5 million death benefit gets pulled back into the taxable estate. The family gets hit with a $2 million tax bill they never saw coming, and guess who gets the malpractice lawsuit?
Research shows that on average, 30% of policies will need remediation each year. These aren’t just numbers – they’re families watching their legacies evaporate because nobody understood that proper administration isn’t optional.
I’m Paul E. Deloughery, and I’ve spent over 25 years watching families lose millions because they treated ILIT trust administration like an afterthought instead of the ongoing fiduciary duty it actually is. After inheriting and losing $14 million myself, I learned these lessons the hard way so you don’t have to.
Ilit trust administration glossary:
An Attorney’s Guide to Navigating the ILIT Minefield
Picture this: You’ve just finished drafting what might be the most neat Irrevocable Life Insurance Trust you’ve ever created. The grantor (your client) is thrilled about shielding their $10 million death benefit from estate taxes. The trustee (usually a well-meaning family member) nods confidently about their responsibilities. The beneficiaries are already dreaming about their tax-free windfall.
Everyone shakes hands, you close the file, and you think you’ve just scored a major victory against the IRS.
Here’s the brutal truth: You’ve just handed someone a loaded financial weapon, and most trustees have no idea how to keep it from exploding.
An ILIT isn’t some dusty document that goes into a safe deposit box and magically works forever. It’s more like adopting a high-maintenance pet that needs daily care, regular feeding, and constant attention. Miss a meal, skip a vet appointment, or forget to walk it, and suddenly your beautiful creation becomes a very expensive problem.
I’ve watched too many families learn this lesson the hard way. A missed Crummey notice here, a skipped premium payment there, or a trustee who stops monitoring the insurance policy’s performance – and suddenly that carefully crafted estate plan becomes a malpractice claim with your name on it.
The three-year look-back rule alone can pull that entire death benefit back into the taxable estate if the grantor dies within three years of establishing the trust. But that’s just the beginning of what can go wrong.
Think of ILIT trust administration as active military duty, not a peaceful retirement. The trustee isn’t just holding paperwork – they’re the commanding officer of a complex financial operation that requires precision, timing, and expertise. One tactical error, and the entire mission fails.
The families who get this right? They preserve millions in wealth for future generations. The ones who treat it casually? They’re the ones calling you at 2 AM after getting a tax bill that could have been completely avoided.
Your job as their attorney isn’t finished when you sign off on the trust documents. It’s just beginning.
The ILIT: A Powerful Weapon That Can Backfire Spectacularly
An ILIT is designed for one primary mission: to own a life insurance policy so the proceeds are not included in the grantor’s taxable estate. With the federal estate tax exemption set to be slashed in half come 2025, this tool is more critical than ever. But its power is matched only by its fragility.
The Core Mission: Defeating the Estate Tax
Here’s the reality check nobody wants to hear. Right now, the estate tax exemption sits pretty at $13.61 million per person and $27.22 million for married couples. Sounds generous, right? Don’t get comfortable.
Come 2025, that safety net gets cut in half thanks to the 2025 sunset provision. Suddenly, families who thought they were in the clear are staring down a massive estate tax bill. I’ve watched this movie before, and it doesn’t end well.
An ILIT keeps that life insurance death benefit completely out of your taxable estate. Think about it—you’ve built wealth in illiquid assets like the family business, real estate, or that art collection you’ve been curating for decades. Your kids inherit it all, but they need cash to pay Uncle Sam.
Without tax-free liquidity, they’re forced into fire sales. The family ranch that’s been in your bloodline for generations? Gone to pay taxes. The business you spent your life building? Liquidated at pennies on the dollar.
That’s where proper ilit trust administration becomes crucial. The death benefit from your ILIT provides the cash your heirs need without forcing them to sell off everything you worked to build. You can see exactly what’s coming with the 2024 tax rates and projections.
Understanding the difference between who creates and who manages the trust is fundamental to making this work. Check out Trustee Versus Trustor to get clear on these critical roles.
Beyond Taxes: A Shield for the Beneficiaries
But here’s what most attorneys miss—an ILIT isn’t just about dodging taxes. It’s about protecting your beneficiaries from themselves and the world around them.
Creditor protection is huge. Your son gets sued for a car accident, or your daughter goes through a messy divorce. Without an ILIT, that life insurance payout becomes fair game for creditors and ex-spouses. The money you intended for your family’s security ends up in someone else’s pocket.
An ILIT creates a fortress around those funds. The death benefit stays protected, no matter what financial storms your beneficiaries face.
Then there’s controlled distributions—the ability to dictate exactly how and when your money gets distributed. Want your grandkids to get college funding but not a massive lump sum at 18? An ILIT lets you set those rules.
This is especially critical for special needs planning. If you have a loved one with disabilities, an ILIT can provide ongoing support without jeopardizing their eligibility for government benefits. It’s about ensuring that inheritance improves their life instead of creating new problems.
For families dealing with significant wealth and complex legacy planning needs, tools like our Asset Vault Trust can provide even more protection. This irrevocable trust incorporates a special power of appointment for maximum flexibility while maintaining rock-solid asset protection.
The key is understanding that effective ilit trust administration goes far beyond just paying premiums. It’s about creating a comprehensive shield that protects both your wealth and your family’s future. For more insights on managing these complex arrangements, dive into Family Trust Administration.
The Trustee’s Gauntlet: A Masterclass in ILIT Trust Administration
The trustee is the captain of this ship, and most are sailing into a storm without a map. Their duties are not suggestions; they are fiduciary obligations with real teeth. Getting this wrong means personal liability.
The Annual Crummey Notice Ritual
Picture this: you’re the trustee of a multi-million dollar ILIT, and you forgot to send a simple letter. That one oversight just cost the family hundreds of thousands in unnecessary taxes. Welcome to the high-stakes world of Crummey notices.
The Crummey letter is your golden ticket to the annual gift tax exclusion. When the grantor makes a gift to the ILIT (usually to pay those hefty life insurance premiums), you must notify each beneficiary of their temporary right to withdraw that money. This transforms what would be a “future interest” gift into a “present interest” gift, qualifying it for the annual exclusion—$18,000 per beneficiary in 2024, or $36,000 if the grantor’s spouse consents.
Here’s where it gets tricky. You’re not just sending a casual heads-up. You’re creating beneficiary withdrawal rights that must be carefully documented. The beneficiary typically has 30 days to withdraw the funds, though most never do (and you’re hoping they don’t, since you need that money for premiums).
The meticulous documentation requirement cannot be overstated. You need proof the notice was sent, received, and that the withdrawal period expired without action. Miss this step, and the IRS might disallow the gift tax exclusion entirely. That means the grantor’s lifetime exemption gets eaten away unnecessarily, or worse, they face immediate gift tax liability.
This ritual happens every single time money goes into the trust. No exceptions. It’s part of your IRS compliance duties, and frankly, it’s where most trustees stumble. The process is straightforward, but the consequences of getting it wrong are devastating. This is just one critical piece of the broader puzzle in Administration of Estates and Trusts.
Managing the Policy: Your Most Critical and Neglected Duty
If Crummey notices are the paperwork that trips up trustees, policy management is the iceberg that sinks the whole ship. Most people think life insurance is a “buy it and forget it” product. That’s a dangerous myth that costs families millions.
Your fiduciary duty extends directly to that life insurance policy sitting inside the trust. Miss a premium payment, and the policy lapses. Game over. The entire ILIT strategy collapses, and you’re personally liable for the mess.
But it goes deeper than just paying bills on time. You need continuous policy performance monitoring. Life insurance policies are complex financial instruments that can deteriorate over time. Interest rates change, mortality costs shift, and what looked like a solid policy ten years ago might be hemorrhaging cash today.
You also need to keep an eye on the insurer’s financial strength. A financially shaky insurance company puts the entire death benefit at risk. What good is a $5 million death benefit if the carrier goes belly-up?
Here’s the sobering reality: 30% of policies need remediation each year. That’s not a typo. Nearly one in three policies requires some form of intervention—premium adjustments, policy restructuring, or complete replacement. The lapsation risk is real, and it’s your job to prevent it.
Policy remediation isn’t optional maintenance; it’s emergency surgery. When a policy starts failing, you have a narrow window to fix it before permanent damage occurs. This might mean increasing premiums, adjusting death benefits, or even replacing the entire policy. The key is catching problems early, before they become catastrophic.
Navigating the Tax and Legal Labyrinth
Beyond sending letters and managing policies, you’re wading into a swamp of tax and legal complexity that would make most people’s heads spin.
Gift Tax Returns (Form 709) become your annual homework assignment. If the grantor’s gifts exceed the annual exclusion, or if you’re making generation-skipping transfer tax elections, Form 709 is mandatory. Even gifts within the annual exclusion might require filing if you’re making specific GST tax elections. Get this wrong, and you’ve created a tax nightmare.
The GST Tax exemption adds another layer of complexity. Most ILITs benefit multiple generations, which triggers generation-skipping transfer tax rules. You’ll likely want to elect out of automatic GST allocation to maintain flexibility, but that requires proper filing and documentation.
Grantor trust rules create an interesting twist. The ILIT is typically structured so the grantor pays income taxes on any trust income during their lifetime. While ILITs don’t usually generate much income (since they primarily hold life insurance), understanding this distinction is crucial for proper tax reporting.
The irrevocability of the trust isn’t just a name—it’s a straitjacket. Once assets go into the ILIT, the grantor loses control. You can’t modify terms on a whim or accommodate changing family circumstances without jumping through major legal hoops. This inflexibility is the price of tax benefits.
Then there’s the three-year look-back rule—the trap that catches even experienced attorneys. If the grantor transfers an existing life insurance policy to the ILIT and dies within three years, the IRS pulls the death benefit back into their taxable estate. The entire tax strategy fails. The safest approach is having the ILIT purchase a new policy from day one, avoiding this landmine entirely.
For the technical details on this rule, review The IRS three-year rule explained. When the insured eventually dies, you’ll need Form 712 from the insurance company for the estate tax return, regardless of whether the proceeds are actually taxable.
ILIT trust administration demands expertise, attention to detail, and constant vigilance. It’s not a part-time job or something you can wing. The financial stakes are too high, and the legal consequences too severe, to treat this responsibility casually.
Common Landmines and How to Disarm Them
Years in this field teach you to spot the tripwires before they go off. Improper ilit trust administration isn’t a possibility; it’s a probability unless you are actively preventing it. The consequences are severe, ranging from a failed tax strategy to a trustee getting sued.
I’ve watched too many families find the hard way that an ILIT without proper administration is like a loaded gun with a faulty safety. It looks secure until it goes off in your face.
The High Cost of Incompetent ILIT Trust Administration

Let me paint you a picture of what incompetent ILIT trust administration actually costs. It’s not just embarrassing—it’s financially devastating.
The most obvious disaster is when the death benefit gets pulled back into the taxable estate. $5 million policy you set up to avoid estate taxes? With sloppy administration, it suddenly becomes taxable. At a 40% federal estate tax rate, that’s $2 million gone. Poof. Your brilliant tax strategy just became a $2 million mistake.
But wait, there’s more. A missed premium payment or a poorly monitored policy can cause the entire death benefit to vanish. The beneficiaries don’t just lose the tax advantage—they lose everything. The policy lapses, and decades of premium payments disappear into thin air.
Then comes the trustee liability. When beneficiaries realize their inheritance got botched, they don’t just shrug it off. They sue. And trustees who breach their fiduciary duty face personal liability. I’ve seen well-meaning family members lose their own assets defending lawsuits because they thought being a trustee was just signing a few papers once a year.
The litigation risk doesn’t stop with the trustee. Beneficiary disputes become inevitable when someone realizes the trust was mismanaged. Siblings turn against each other, families split apart, and legal fees eat up whatever’s left of the estate.
Choosing Your Captain: The Critical Trustee Decision
Here’s where most people get it wrong. They choose a trustee like they’re picking someone to water their plants while they’re on vacation. This isn’t about finding someone you trust with your house key—it’s about finding someone who can steer complex financial and legal waters without sinking the ship.
An individual trustee might seem like the obvious choice. It’s usually a family member, it feels personal, and hey, they’re free. But free can be the most expensive option of all. Does your brother-in-law understand Crummey notices? Can he monitor insurance policy performance? Will he remain impartial when beneficiaries start arguing about distributions?
The conflict of interest problem is real. When the trustee is also a beneficiary, they’re essentially refereeing a game they’re playing in. That rarely ends well.
A corporate trustee brings expertise, impartiality, and longevity to the table. Yes, they charge fees, but those fees are insurance against catastrophic mistakes. They understand the intricacies of ILIT trust administration, have systems for compliance, and won’t disappear when things get complicated.
Think about it this way: would you rather pay a professional fee or risk losing millions because Uncle Bob forgot to send the Crummey notices?
For more insight into what trustees actually do (and what they’re liable for), check out What Does a Trustee Do?.
When to Call for Backup: Outsourcing Administration
Sometimes the smartest thing you can do is admit you’re in over your head. Outsourcing ILIT trust administration isn’t giving up—it’s getting smart about risk management.
The complexity factor alone should give you pause. Multiple policies, intricate beneficiary structures, generation-skipping considerations—these aren’t weekend projects. When the lack of expertise becomes apparent, the time constraints overwhelming, or the risk mitigation needs obvious, professional administration starts looking like the bargain it actually is.
Professional administrators bring policy monitoring that actually monitors, premium management that prevents lapses, and Crummey notice execution that satisfies the IRS. They handle compliance reporting without breaking a sweat and provide tax coordination that keeps your CPA happy.
The record-keeping alone is worth the fee. When the IRS comes knocking (and they will), you want audit-ready documentation, not a shoebox full of receipts and good intentions.
Most importantly, they provide policy remediation when things go sideways. 30% annual remediation statistic? Professional administrators don’t just spot problems—they fix them before they become disasters.
The bottom line? Outsourcing ILIT administration is like hiring a pilot for your private jet. You could try to fly it yourself, but do you really want to risk the crash?
Conclusion: Treat ILITs with the Respect They Demand
Here’s the hard truth: an ILIT isn’t some simple document you can draft, file away, and forget about. It’s a sophisticated financial instrument that demands the same level of ongoing attention you’d give to a high-stakes court case. The difference is, when this one goes wrong, there’s no appeal.
I’ve watched too many families learn this lesson the expensive way. A $10 million estate suddenly facing a $4 million tax bill because someone thought ILIT trust administration was optional. Adult children finding their inheritance evaporated because a well-meaning uncle serving as trustee didn’t understand that monitoring policy performance wasn’t just a suggestion.
The stakes are simply too high to wing it. Proper ILIT trust administration isn’t about checking boxes or following some generic checklist. It’s about understanding that you’re the guardian of a family’s financial legacy. Every Crummey notice, every premium payment, every policy review—these aren’t administrative tasks. They’re the difference between your clients’ wishes being honored and their beneficiaries getting blindsided by preventable disasters.
The complexity isn’t going away. If anything, with estate tax exemptions set to plummet in 2025, these tools are becoming more critical and more scrutinized. The IRS isn’t getting more forgiving, and beneficiaries aren’t getting more patient with trustees who fumble their responsibilities.
If you’re staring at an ILIT that needs administration, or you’re advising clients who are, don’t treat this as something you can figure out as you go. The learning curve is steep, and the cost of mistakes is measured in millions, not thousands.
At Sudden Wealth Protection Law, we’ve steerd these treacherous waters for over two decades. We’ve seen what happens when administration fails, and more importantly, we know how to prevent those failures before they destroy a family’s legacy.
Protect your family’s legacy by ensuring your trust is administered correctly.

