

Income beneficiary vs principal beneficiary distinctions can make or break your estate plan. Here’s the key difference:
| Type | Receives | Taxation | Common Examples |
|---|---|---|---|
| Income Beneficiary | Earnings generated by trust assets (interest, dividends, rent) | Taxed as regular income | Surviving spouse, retired parents |
| Principal Beneficiary | The underlying trust assets themselves | Generally not taxed until sold (capital gains) | Children, charities, future generations |
A trust represents one of the most powerful tools in estate planning, but understanding who gets what—and when—makes all the difference. When a grantor establishes a trust, they typically divide the benefits between two key roles: income beneficiaries and principal beneficiaries.
Income beneficiaries receive the earnings generated by trust assets—things like interest, dividends, and rental payments. Principal beneficiaries (sometimes called remainder beneficiaries) ultimately receive the trust’s core assets themselves.
This distinction matters tremendously in practice. For example, a surviving spouse might receive all income from rental properties held in trust, while the children are designated to receive the properties themselves after the spouse’s death. The trustee must steer these competing interests carefully.
Under Arizona law, trustees have specific obligations to both types of beneficiaries. They must balance generating reasonable income while preserving principal value—a balancing act that requires careful attention to both the trust document and state statutes.
I’m Paul E. Deloughery, founder of Sudden Wealth Protection Law, and I’ve spent over 25 years helping families steer the complexities of income beneficiary vs principal beneficiary designations to protect their wealth and ensure smooth transfers between generations. My experience includes both creating trusts that properly balance these interests and resolving disputes when improper classifications lead to family conflict.

Why This Guide Matters
Understanding the distinction between income and principal beneficiaries isn’t just legal minutiae—it’s fundamental to achieving your estate planning goals. When clients come to our Phoenix office, they often express specific desires:
“I want to make sure my spouse is taken care of for life, but I also want my children to inherit the family business intact.”
“I’m worried my son might squander his inheritance—can I give him just the earnings while preserving the core assets?”
These common concerns highlight why getting income beneficiary vs principal beneficiary designations right matters. The wrong structure can lead to:
- Family disputes over trust distributions
- Unintended tax consequences for beneficiaries
- Depletion of assets meant for future generations
- Trustees caught in the crossfire of competing interests
By clearly defining who gets what—and when—you can ensure your wishes are followed and family harmony is preserved. Let’s explore how these designations work in practice.
Trust Principal and Income 101
Understanding the difference between income beneficiary vs principal beneficiary starts with grasping what exactly makes up the “principal” and “income” of a trust. Think of this as the foundation that everything else builds upon.
Trust Principal (sometimes called corpus) is essentially the core assets of the trust:
– The original property you place into your trust
– Any extra assets you contribute later
– Growth in value of those assets over time
– Profits when trust assets are sold (capital gains)
– Money from legal settlements the trust might receive
Trust Income, on the other hand, represents what those assets generate:
– Interest that accumulates in bank accounts
– Dividends your stocks pay out
– Rent checks from trust-owned properties
– Profits distributed from a business in the trust
– Royalty payments from intellectual property
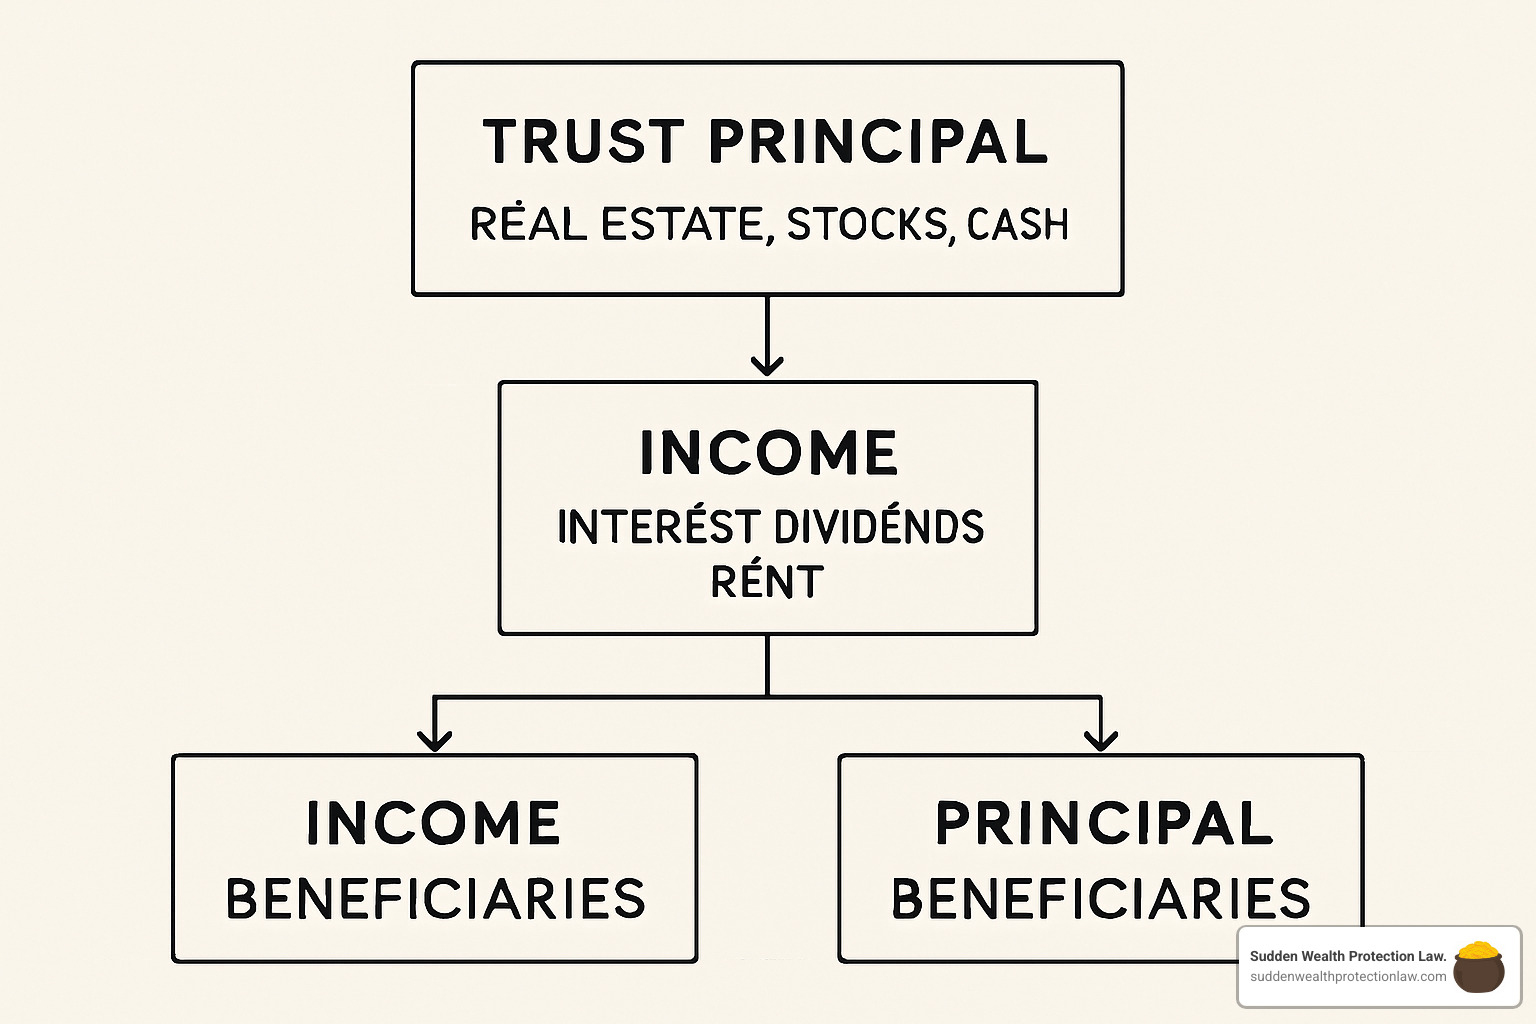
I often explain this to clients using a simple metaphor: the principal is like a fruit tree (the asset itself), while income is the fruit it produces each season. Income beneficiaries get to enjoy the fruit, while principal beneficiaries eventually inherit the tree.
Here’s a straightforward comparison to help clarify the difference:
| Principal (Corpus) | Income |
|---|---|
| Original trust assets | Interest payments |
| Capital gains | Dividends |
| Property sale proceeds | Rental payments |
| Additional contributions | Business profits |
| Lawsuit settlements | Royalties |
| Digital assets (ownership) | Digital asset revenue |
How Arizona Law Defines Principal and Income
Here in Arizona, we follow the Uniform Principal and Income Act, which you’ll find in Arizona Revised Statutes (A.R.S.) 14-11001 through 14-11031. These laws provide a clear roadmap for trustees when the trust document doesn’t spell out every detail.
When determining what counts as principal versus income, Arizona law establishes a clear hierarchy:
First, follow what the trust document specifically says. This is always the starting point, as it represents the grantor’s intentions.
Second, if the document gives the trustee discretion to make these determinations, the trustee may exercise that power.
Third, if neither of those provides an answer, then the statutory default rules kick in.
Under these default rules, capital gains typically remain in the principal bucket, ordinary dividends flow to income, and extraordinary dividends might stay with principal. When capital is returned to the trust, it reduces the asset’s basis and counts as principal.
In my 25 years of practice, I’ve found that many clients don’t realize Arizona law gives trustees some flexibility to make adjustments between principal and income when necessary to ensure fairness to all beneficiaries. This becomes especially important in today’s investment environment.
For a deeper dive into handling trust administration responsibilities, check out our Trust Administration for Dummies guide.
Typical Assets: Income vs Principal
Let’s walk through how common trust assets typically get classified in the real world:
When it comes to real estate, the property itself represents principal, while the monthly rental checks count as income. For stocks, the shares themselves (and any gain when sold) are principal, while quarterly dividends flow to income. With bonds, the face value is principal, and those interest payments are income.
Business interests work similarly—ownership stakes in the company are principal, while distributed profits count as income. Even digital assets follow this pattern: websites, domains, and cryptocurrency holdings are principal, while the revenue they generate (like advertising income or staking rewards) counts as income.
I recently worked with a family whose trust held several rental properties in Phoenix. The properties themselves were principal assets designated for the children, while Mom received all the rental income as the income beneficiary. When they sold one property, the proceeds remained principal—even though they were now cash rather than real estate.
This highlights an important concept: principal can change form without changing classification. When a trust sells an apartment building for cash, that cash remains principal even though it’s now in a completely different form.
Understanding these distinctions isn’t just academic—it directly impacts how beneficiaries benefit from the trust and helps trustees fulfill their legal obligations to treat all beneficiaries fairly.
Income Beneficiary vs Principal Beneficiary: Key Differences
Now that we understand the distinction between principal and income, let’s examine how this affects the two classes of beneficiaries.

When I sit down with clients to explain the income beneficiary vs principal beneficiary relationship, I often use the analogy of a fruit tree. The income beneficiary gets to enjoy the fruit (earnings) while the principal beneficiary ultimately receives the tree itself. This fundamental difference shapes everything from distribution timing to tax consequences.
Income beneficiaries receive the regular earnings from trust assets—those monthly rental checks, quarterly dividend payments, or annual interest. They typically see these payments on a consistent schedule, giving them reliable cash flow. However, they generally can’t touch the underlying assets generating that income. In some cases, they may have rights to request that non-productive assets be sold or converted to income-producing ones, especially if the trust isn’t generating reasonable income.
On the other hand, principal beneficiaries (sometimes called remainder beneficiaries) might wait years or even decades before receiving their share. Their patience is rewarded with the underlying trust assets themselves—the real estate, investment accounts, business interests, or other property that makes up the trust corpus. While they wait, they benefit from the growth and appreciation of these assets, even if they don’t receive regular distributions.
I recently worked with a widow who became the income beneficiary of her late husband’s trust. She receives quarterly distributions from the trust’s investment portfolio, providing her with steady support. Meanwhile, her stepchildren are the principal beneficiaries who will eventually inherit the investment accounts themselves. This arrangement ensures everyone’s needs are met while preserving family harmony.
The timing difference is crucial. As one client colorfully put it, “So my wife gets the milk, and my kids eventually get the cow?” Exactly right—and that timing difference often serves important estate planning goals.
HEMS and Other Distribution Standards
The clean divide between income and principal can be softened through carefully crafted distribution standards. Most commonly, I recommend including HEMS provisions that allow trustees to tap into principal when necessary.
HEMS stands for Health, Education, Maintenance, and Support. This standard gives trustees permission to distribute principal for these specific needs, even to someone who’s primarily an income beneficiary. For example, if an income beneficiary faces unexpected medical bills exceeding their regular distributions, the trustee could potentially distribute principal to cover these costs.
Beyond HEMS, trusts might incorporate other standards that provide different levels of flexibility:
Discretionary provisions give trustees maximum flexibility but provide minimal guidance. Best interests standards allow distributions believed to benefit the beneficiary’s overall wellbeing. Comfort and welfare standards slightly expand the HEMS concept, while happiness standards open the door to luxury distributions.
I always tell clients, “The standard you choose is like setting the thermostat for your trust—too restrictive and beneficiaries might suffer, too loose and your assets might evaporate faster than intended.”
For deeper insights into different beneficiary classifications, check out our guide on Discretionary Beneficiary vs Final Beneficiary.
Tax Impact on Each Class
The tax implications for income beneficiary vs principal beneficiary designations are substantial and often overlooked in planning.
Income beneficiaries receive a Schedule K-1 reporting their distributions, which they’ll pay tax on at their individual income tax rates. The good news? The trust itself gets a deduction for distributed income, and the character of that income (whether ordinary interest, qualified dividends, or other types) flows through to the beneficiary.
Principal beneficiaries generally don’t face immediate income tax on distributions. Instead, they typically receive assets with a carryover basis, meaning they’ll only pay capital gains tax if and when they sell those assets. Depending on the trust structure, there may also be estate tax considerations.
This difference creates interesting planning opportunities. Since trusts hit the highest federal tax bracket of 37% at just $13,450 of taxable income (2023 figures), there’s often a tax advantage to distributing income to beneficiaries in lower tax brackets rather than accumulating it in the trust.
As I explain to trustees, “You’re not just balancing personalities and needs—you’re also balancing tax brackets.” A thoughtful distribution strategy can save thousands in unnecessary taxes.
However, distributing principal reduces the trust’s income-generating capacity, potentially shorting future income beneficiaries. This highlights the delicate balancing act trustees must perform—another reason why clear trust language is essential.
For those interested in statutory frameworks governing these allocations, Probate Code Section 16320 provides detailed rules, though Arizona has its own specific statutes that apply to trusts in our state.
The income beneficiary vs principal beneficiary distinction isn’t just legal technicality—it’s a powerful tool for achieving your specific estate planning goals when properly structured with your family’s unique dynamics in mind.
Trustee Discretion and Compliance Under Arizona Statutes
Trustees walking the tightrope between income and principal beneficiaries face a delicate balancing act. Arizona law doesn’t leave them guessing—it provides a comprehensive roadmap through A.R.S. 14-10801 through 14-10819.
When I sit down with clients who are considering serving as trustees, I always emphasize their core responsibilities under Arizona law. The duty to administer the trust in good faith isn’t just legal jargon—it’s about honoring the trust creator’s intentions. The duty of loyalty means putting beneficiaries’ interests ahead of your own, while the duty of impartiality requires fairness to all beneficiaries, regardless of your personal relationships.
Add to this the duty of prudent administration and compliance with the prudent investor rule, and you have a trustee’s job description in a nutshell. But these seemingly straightforward duties get complicated when you’re trying to please both income and principal beneficiaries.
“I often tell trustees to imagine throwing a dinner party where half your guests are vegetarians and half are carnivores,” says Paul Deloughery. “Arizona trustees must satisfy both groups while following the recipe left by the trust creator. The prudent investor rule gives you some flexibility in how you prepare the meal, but you can’t simply ignore half your guests’ preferences.”
This balancing act requires meticulous record-keeping. Smart trustees maintain detailed accounts of what constitutes principal versus income, how they’ve allocated receipts and expenses, and what distributions they’ve made. These records aren’t just for satisfying legal requirements—they’re your best defense if beneficiaries start questioning your decisions.
Balancing Competing Interests
When income beneficiaries want high-yield investments while principal beneficiaries prefer growth stocks, trustees often feel caught in the middle. I’ve seen this play out countless times in family trusts.
Take the Jenkins family trust I worked with last year. The surviving spouse needed income to maintain her lifestyle, while the adult children were concerned about preserving their inheritance. The solution wasn’t choosing one side over the other—it was finding middle ground through a carefully balanced portfolio and transparent communication.
Smart trustees have several tools at their disposal when facing these conflicts. They can look to explicit trust provisions that might prioritize one beneficiary class. They can seek written consent from adult beneficiaries for major decisions, creating buy-in and reducing later complaints. When conflicts seem irresolvable, petitioning the court for instructions provides legal protection.
Many trustees also find that appointing an independent co-trustee for decisions involving conflicts removes the appearance of favoritism. Whatever approach you take, documenting your reasoning provides a paper trail that demonstrates your thoughtful consideration of all interests.
The duty of loyalty doesn’t mean treating everyone identically—it means honoring the trust’s purpose while giving due consideration to all beneficiaries’ interests.
Adjustments Between Principal and Income
One of Arizona’s most powerful tools for trustees comes from our adoption of the Uniform Principal and Income Act. This legislation gives trustees the flexibility to make adjustments between principal and income when traditional classifications would produce unfair results.
This power is particularly valuable in today’s investment landscape. Modern portfolio theory focuses on total return rather than artificially separating income and growth. Without adjustment power, trustees might feel forced to choose inappropriate investments just to generate “income” on paper.
For example, when interest rates plummeted in recent years, many Arizona trustees faced a dilemma: stick with traditional fixed-income investments yielding next to nothing, or invest for growth and find a way to fairly compensate income beneficiaries. The adjustment power provides the answer.
“It’s like having the ability to reclassify some apples as oranges when that’s what fairness requires,” explains one Phoenix trust administrator. “We can invest for total return and then allocate a reasonable portion to the income beneficiary, satisfying both parties.”
The Uniform Principal and Income Act provides trustees with this flexibility, though trust creators can modify or eliminate this power in their documents. When properly used, these adjustment powers help trustees steer the sometimes competing interests of income beneficiary vs principal beneficiary relationships.
This approach aligns with modern trust administration practices while still honoring the fundamental distinction between those who benefit now and those who benefit later. After all, successful trust management isn’t about rigid accounting—it’s about fulfilling the human intentions behind the legal document.
Preventing & Resolving Conflicts Between Beneficiaries
Family harmony shouldn’t be a casualty of trust administration. Yet at Sudden Wealth Protection Law, I’ve seen how the tension between income beneficiary vs principal beneficiary interests can strain even the closest family bonds. The good news? Most conflicts can be prevented before they ever start.
Communication is the cornerstone of conflict prevention. When families understand the trust’s purpose and structure from the beginning, misunderstandings are less likely to fester into disputes. One client told me after implementing regular family meetings: “The transparency has completely changed our dynamic. My children now understand why certain decisions are made—it’s eliminated the suspicion that used to exist.”
Transparency extends beyond just talking—it requires consistent documentation. Trustees who provide regular accounting to all beneficiaries, clearly explain investment decisions, and document their reasoning for allocations build trust with both income and principal beneficiaries. This paper trail not only satisfies legal obligations but also prevents the “what are they hiding?” suspicions that often trigger litigation.
A formal investment policy statement can work wonders by establishing clear expectations about the balance between current income and long-term growth. This document creates guardrails for trustee decisions and helps both classes of beneficiaries understand the trade-offs being made on their behalf.
When conflicts do arise despite prevention efforts, having mediation provisions already in the trust document can save thousands in legal fees and preserve relationships. These provisions might require attempts at mediation before litigation, designate a trusted family advisor as mediator, or create a structured process for resolving disputes without court intervention.
For more comprehensive strategies on managing family trusts effectively, visit our Family Trust Management resource page.
Common Disputes Over Allocations
Certain issues consistently spark conflict between income beneficiary vs principal beneficiary interests:
Capital gain retention frequently becomes contentious when trust assets are sold at a profit. Income beneficiaries often argue they should receive a portion of the gain, especially if assets were sold to increase income production. Yet Arizona law generally classifies capital gains as principal, creating an inherent tension.
Underproductive assets like vacant land or growth stocks that generate minimal current income can frustrate income beneficiaries who depend on regular distributions. Some trusts wisely include provisions requiring minimum income production or conversion of underproductive assets after a specified period.
Expense allocations regularly trigger disagreements. Should property taxes on undeveloped land be paid from income (reducing current distributions) or principal (reducing future value)? The answer depends on both the trust document and state law, but the competing interests are obvious.
Extraordinary dividends present a classification challenge. When a company issues an unusually large one-time dividend, income beneficiaries naturally want it treated as income, while principal beneficiaries argue it should be principal since such dividends often reduce the underlying share value.
I once mediated a case where a family business held in trust made an enormous distribution after selling a major asset. The surviving spouse (income beneficiary) claimed it was ordinary income, while the children (principal beneficiaries) argued it was effectively a liquidating distribution that should be allocated to principal. Without clear trust language addressing such scenarios, the dispute required court intervention—something the grantor never would have wanted.
Proactive Drafting Tips
As I often tell clients, “An ounce of prevention in drafting is worth a pound of cure in litigation.” Thoughtful trust drafting can prevent most conflicts between income and principal beneficiaries.
Priority clauses eliminate ambiguity by explicitly stating whether income or principal beneficiaries should be prioritized when conflicts arise. Simple language like “The Trustee shall prioritize maintaining the purchasing power of principal, even if doing so reduces income distributions” provides crucial guidance.
Independent trustee provisions are especially valuable when a beneficiary also serves as trustee. Designating an unrelated decision-maker for situations involving conflicts between beneficiary classes removes both actual bias and the appearance of favoritism.
Arbitration clauses requiring disputes to be resolved outside court can save tens of thousands in litigation costs while keeping family matters private. These provisions can specify the arbitration process, selection of arbitrators, and even the standards to be applied.
Specific allocation rules that override statutory defaults provide clarity for common scenarios. For example: “All dividends, regardless of size or source, shall be allocated to income” leaves no room for interpretation or dispute.
Discretionary reallocation power grants the trustee explicit authority to reallocate between principal and income to achieve fairness, especially useful in changing economic environments. This flexibility, when paired with specific guidelines for exercising this discretion, can prevent rigid rules from producing unfair outcomes.
Taking time to address these potential conflict points in your trust document can save your family significant heartache, preserve relationships, and ensure your assets support your loved ones rather than expensive legal battles.
Investment Strategy & Asset Protection Considerations
The balancing act between income beneficiary vs principal beneficiary needs directly shapes how trustees invest trust assets. This isn’t just an accounting exercise—it’s about making real-world investment decisions that satisfy both those needing income now and those counting on growth for the future.
Modern trust management has largely acceptd what we call a “total return” approach. Rather than rigidly separating investments into “income producers” and “growth assets,” this strategy looks at overall portfolio performance. This approach makes tremendous sense in today’s investment landscape because:
It allows trustees to build truly diversified portfolios without feeling pressured to chase yield in dangerous ways. This is especially valuable in low-interest environments where income-focused investments might not generate sufficient returns without taking excessive risks.
Many families find that combining this investment philosophy with a “unitrust” distribution method works wonderfully. Instead of distributing only traditional income, the trust distributes a fixed percentage of the total trust value annually. This aligns everyone’s interests toward overall growth while providing predictable distributions.
Frequently Asked Questions about Income and Principal Beneficiaries
Can one person be both an income and a principal beneficiary?
Yes, absolutely! This arrangement is quite common in family trusts. Many of our clients choose to designate the same person as both an income and principal beneficiary, just with different timing and conditions attached.
For example, a typical trust might provide that:
- Your daughter receives all income generated quarterly
- She can access principal when needed for health, education, maintenance and support
- At age 45, she receives the remaining principal outright
I remember one client who explained their thinking perfectly: “I want my son to have the steady stream of income now while he’s establishing his career, but I don’t want him to have unfettered access to the principal until he’s demonstrated financial maturity. The income keeps him comfortable while the principal restriction keeps him motivated.”
The beauty of this approach is its flexibility. Even when distributions go to the same person, having different rules for income versus principal helps achieve your specific planning goals – whether that’s providing immediate support while encouraging long-term financial responsibility, or balancing current needs with future security.
Who decides whether a receipt is income or principal?
When it comes to classifying receipts as income or principal, there’s a clear hierarchy that trustees must follow:
- The trust document comes first – Any specific provisions you include override everything else
- Trustee discretion applies next – But only if your trust explicitly grants this power
- Arizona state law fills the gaps – Specifically A.R.S. 14-11001 through 14-11031
- Courts intervene as a last resort – When disputes can’t otherwise be resolved
At Sudden Wealth Protection Law, we typically include language stating that the trustee’s reasonable determination of what constitutes income versus principal is binding. This provision helps prevent family disputes and provides much-needed clarity for everyone involved.
That said, trustees can’t just classify receipts however they want. They must exercise this discretion in good faith and in accordance with the trust’s purposes. A trustee who deliberately misclassifies receipts to favor one beneficiary over another would be breaching their fiduciary duty – something courts take very seriously.
What happens if the trustee misclassifies a receipt?
Misclassification mistakes can lead to serious consequences. I’ve seen situations where seemingly small accounting errors snowballed into major family conflicts.
If a trustee incorrectly classifies a receipt as income when it should be principal (or vice versa), several things might happen:
The affected beneficiaries may bring a breach of fiduciary duty claim against the trustee. This is particularly likely if the misclassification appears intentional or repeatedly favors one beneficiary class.
The trustee might need to make accounting adjustments to correct past allocations, which can be complex if distributions have already been made based on incorrect classifications.
In serious cases, beneficiaries might file a removal action seeking to replace the trustee with someone more competent or impartial.
Courts can surcharge the trustee, meaning they become personally liable for damages caused by their misclassification. This can quickly become expensive!
Incorrect classifications can also create unexpected tax consequences for beneficiaries, potentially triggering audits or penalties.
In Arizona, beneficiaries generally have two years after receiving an adequate trust disclosure to bring claims, or four years after a breach of trust occurs. This gives beneficiaries reasonable time to find and address problems.
As I often tell trustees who come to me worried about making the right calls: “When in doubt about classification, invest in professional advice. The few hundred dollars you might spend on consulting with an attorney or accountant is nothing compared to the potential liability and family strife that can result from misclassification.”
The best approach is always prevention – clear trust language, good record-keeping, transparent communication with beneficiaries, and professional guidance when needed.
Conclusion
The distinction between income beneficiary vs principal beneficiary designations isn’t just legal terminology—it’s the foundation that makes many trusts work. Understanding these roles makes all the difference whether you’re creating a trust, managing one as a trustee, or receiving distributions as a beneficiary.
At Sudden Wealth Protection Law, we help Arizona families design trusts that truly honor the grantor’s wishes while carefully balancing the needs of both income and principal beneficiaries. Our approach is both practical and personal:
We focus on clear drafting that leaves no room for confusion about who gets what and when. Many family disputes arise simply because the trust language was ambiguous or contradictory—something we work diligently to avoid.
We create customized solutions like the Asset Vault Trust that provide both robust protection and necessary flexibility. These specialized structures allow us to address your family’s unique circumstances rather than forcing you into a one-size-fits-all approach.
Our proactive conflict prevention strategies are built into every trust we design. By anticipating potential areas of disagreement between beneficiary classes, we can address them before they become problems.
We provide practical administration guidance for trustees facing the often difficult task of balancing competing interests. This includes helping them understand when and how to exercise discretion appropriately.
When conflicts do arise, our dispute resolution expertise helps families find solutions without destroying relationships or depleting trust assets through costly litigation.
I’ve seen how proper planning can successfully serve both income and principal beneficiaries while preserving family harmony. The key is understanding Arizona’s legal framework, clearly communicating intentions, and implementing structures that truly align with your family’s unique situation.
If you need help creating a trust that balances the needs of different beneficiary classes—or if you’re dealing with disputes between income and principal beneficiaries—we’re here to help. Our experienced team provides compassionate, expert guidance custom specifically to your circumstances.
For families already experiencing disputes regarding trust distributions or classifications, we offer specialized support. Visit our Trust Estate Contests Disputes and Litigation page to learn more about how we can help resolve these challenging situations.
The right trust structure does more than just transfer assets—it provides for your loved ones’ immediate needs while preserving your legacy for generations to come. When properly designed, the distinction between income and principal beneficiaries becomes a powerful tool for achieving your most important estate planning goals.

