

Why Irrevocable Trust Benefits Make Losing Control Worth It
Irrevocable trust benefits include removing assets from your taxable estate, protecting wealth from creditors and lawsuits, qualifying for government benefits like Medicaid, avoiding probate, and maintaining privacy. Here’s what you get when you give up control:
Top 5 Irrevocable Trust Benefits:
- Asset Protection – Shields wealth from creditors, lawsuits, and divorce claims
- Estate Tax Savings – Removes assets from your taxable estate (40% federal rate above $13.61M)
- Medicaid Eligibility – Helps qualify for long-term care benefits after 5-year look-back
- Probate Avoidance – Keeps your affairs private and speeds up distribution
- Controlled Distributions – Protects beneficiaries from their own poor decisions
Look, I get it. The idea of putting your hard-earned assets into a trust you can’t touch feels like financial suicide. But here’s the reality I’ve seen after 25 years of practice: the families who refuse to give up control today often lose everything tomorrow.
The brutal truth? Your revocable trust won’t protect you from a lawsuit. Your will won’t save your heirs from estate taxes. And your good intentions won’t stop a creditor from seizing assets you thought were safe.
As someone who inherited $14 million in 2009 and watched most of it disappear, I’ve learned that irrevocable trust benefits aren’t just theoretical – they’re the difference between leaving a legacy and leaving your family to fight over scraps. I’m Paul E. Deloughery, founder of Sudden Wealth Protection Law, and I’ve spent my career helping Arizona families avoid the mistakes that cost me everything.

Irrevocable trust benefits terms made easy:
- advantages of irrevocable trust
- benefits irrevocable funeral trust
- irrevocable trust for medicaid planning
Irrevocable Trust Benefits: Why Give Up Control Now to Win Later?
I’ve watched too many families learn this lesson the hard way. The moment you need asset protection is exactly when it’s too late to get it. That’s why irrevocable trust benefits require you to act before the storm hits – not after you’re already drowning.
Here’s what I tell clients who hesitate: you’re not losing control, you’re trading temporary control for permanent peace of mind. The irrevocable trust benefits I’ve witnessed include bulletproof lawsuit shields, Medicaid eligibility that saves families hundreds of thousands, estate tax savings that preserve 40% of your wealth, and probate avoidance that keeps your business out of the courthouse.
Top 5 Irrevocable Trust Benefits
Asset protection that actually works – Unlike revocable trusts, which offer zero creditor protection, irrevocable trusts create a legal firewall. Once you transfer assets, they’re no longer “yours” in the eyes of the law. I’ve seen doctors shield their investment portfolios from malpractice claims and business owners protect their homes from corporate liabilities.
Estate tax strategy that saves millions – With the federal estate tax exemption at $13.61 million per person in 2024, you might think you’re safe. Here’s the catch: that exemption drops to about $6 million in 2026. For families with appreciating assets, irrevocable trust benefits include locking in today’s values and removing future growth from your taxable estate.
Government benefits without going broke – The five-year Medicaid look-back period means you need to plan ahead. But done right, irrevocable trusts can help you qualify for benefits while preserving assets for your family.
Controlled distributions that protect beneficiaries – Some of the biggest irrevocable trust benefits involve protecting your heirs from themselves. Spendthrift provisions prevent creditors from accessing trust assets before distribution, while discretionary language lets trustees withhold funds from beneficiaries making poor choices.
Privacy that keeps your business private – Probate court records are public. Trust distributions aren’t. If you value privacy – and most wealthy families do – avoiding probate through irrevocable trusts keeps your financial affairs out of the newspaper.
How an Irrevocable Trust Protects Against Creditors and Lawsuits
For high-risk professions like medicine, law, or business ownership, asset protection isn’t optional – it’s survival. Arizona’s spendthrift statutes provide strong protection for properly structured trusts, but the language must be precise.
Here’s how it works: when you transfer assets to an irrevocable trust, you’re no longer the legal owner. Creditors can’t seize assets you don’t own. The key is ensuring the trust includes proper spendthrift language and that you don’t retain any prohibited powers.
The reality is harsh but simple: if you can still control the assets, so can your creditors. That’s why irrevocable trust benefits require genuine separation. It’s uncomfortable, but it works.
Irrevocable vs. Revocable Trusts: The Cold Hard Facts
Here’s the truth that most attorneys won’t tell you straight: the difference between revocable and irrevocable trusts isn’t just about flexibility – it’s about whether you want real protection or just paperwork that makes you feel better.
Revocable trusts let you keep complete control. You can modify them, revoke them, or change beneficiaries whenever you want. But here’s the brutal reality: because you maintain control, the law treats those assets as if they’re still yours. That means zero creditor protection, full inclusion in your taxable estate, and complete vulnerability to lawsuits.
Irrevocable trusts flip that equation. You give up control, but you gain genuine protection. The assets are no longer legally yours, which means creditors can’t touch them, they’re removed from your taxable estate, and lawsuits can’t reach them. The irrevocable trust benefits are real because the separation is real.
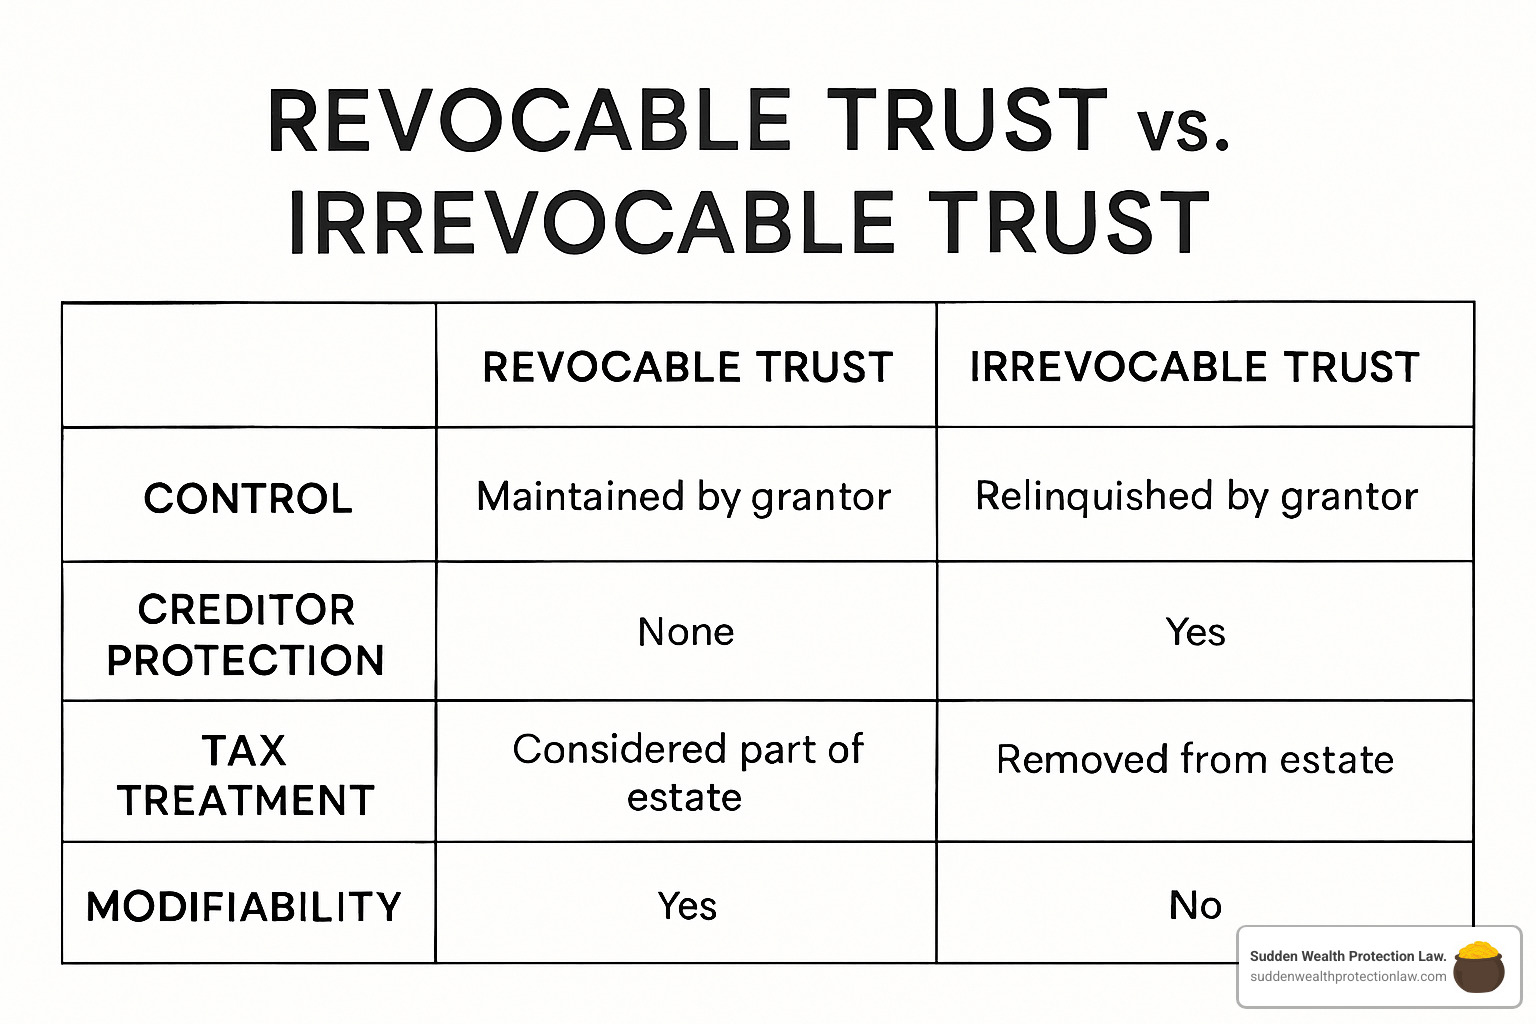
Think of it this way: a revocable trust is like keeping your valuables in a glass safe. You can see them, access them easily, and rearrange them anytime. But when trouble comes, that glass shatters instantly. An irrevocable trust is like a bank vault – harder to access, but it actually protects what’s inside.
When a Revocable Trust Isn’t Enough
I’ve had clients come to me after their revocable trust failed them completely. The business owner who thought his trust would protect his home from corporate liabilities. The doctor who assumed her revocable trust would shield assets from malpractice claims. They all learned the same hard lesson: when you need protection most, revocable trusts provide none.
But here’s what hasn’t changed: if you’re facing creditor risks, estate tax exposure, or need to qualify for government benefits, a revocable trust won’t help you. The irrevocable trust benefits of genuine asset protection and estate tax savings still require giving up control to gain protection.
Types of Irrevocable Trusts and When to Use Each
Choosing the right irrevocable trust is like picking the right tool for the job – use a hammer when you need a screwdriver, and you’ll make a mess of things. Let me walk you through the main players and when to use each one.
Irrevocable Life Insurance Trusts (ILITs) solve a specific problem: keeping life insurance proceeds out of your taxable estate. If you own a $2 million life insurance policy when you die, that’s $2 million added to your estate tax bill. Move that policy into an ILIT, and it disappears from your taxable estate entirely.
Grantor Retained Annuity Trusts (GRATs) are perfect when you have assets that are about to explode in value. You transfer the asset to the trust, keep an income stream for a set period, and any appreciation above a certain rate goes to your heirs tax-free.
Qualified Personal Residence Trusts (QPRTs) let you transfer your home to your children at a reduced gift tax value but keep living there for a set period. It’s brilliant for families with valuable homes who want to pass them on without using up their entire gift tax exemption.
Charitable trusts serve double duty – they support causes you care about while providing immediate tax deductions. Charitable remainder trusts even let you keep an income stream while getting the tax benefits.
Special needs trusts protect disabled beneficiaries without destroying their government benefits. These trusts provide supplemental support while preserving eligibility for programs like SSI and Medicaid.
Medicaid Asset Protection Trusts (MAPTs) help you qualify for long-term care benefits after the five-year look-back period. The key is planning ahead – these trusts only work if you fund them before you need care.

Asset Vault Trusts: Arizona’s Answer to Bulletproof Planning
For clients who need maximum protection but worry about the permanence of traditional irrevocable trusts, we developed something special: the Asset Vault Trust. This isn’t your grandfather’s irrevocable trust – it’s designed for the modern world where flexibility matters as much as protection.
The Asset Vault Trust incorporates a special power of appointment that allows future modifications without going to court. Think of it as an irrevocable trust with a safety valve. You get all the irrevocable trust benefits – creditor protection, estate tax savings, lawsuit immunity – but with the ability to adapt to changing circumstances.
This trust is particularly powerful for business owners and professionals who face ongoing liability risks. A surgeon worried about malpractice claims can protect their assets while maintaining some flexibility for future needs.
The secret to maximizing irrevocable trust benefits is matching the trust type to your specific situation. It’s not about picking the most sophisticated option – it’s about picking the right option.
Tax & Compliance Mechanics You Can’t Ignore
The tax world of irrevocable trusts feels like navigating a minefield blindfolded. One wrong step, and you’re facing unexpected tax bills that can wipe out years of careful planning.
Gift Tax Considerations hit you the moment you fund an irrevocable trust. Every dollar you transfer is generally a taxable gift, but here’s your lifeline: the annual exclusion lets you give $17,000 per beneficiary in 2023 without touching your lifetime exemption. Your lifetime exemption of $12.92 million in 2023 covers the rest, but remember – these numbers change, and the lifetime exemption drops significantly in 2026.
The real shock comes with trust income taxes. Unlike your personal tax return where you need substantial income to hit the top bracket, irrevocable trusts slam into the highest rate of 37% at just $14,450 of income in 2023. It’s brutal math that catches families off guard every tax season.
Then there’s the grantor vs. non-grantor maze. If you retain certain powers over the trust, the IRS treats it as a “grantor trust,” meaning you personally pay taxes on all trust income. Sometimes this works in your favor – you’re essentially making additional tax-free gifts by paying the trust’s tax bill.

Estate Tax Planning with Irrevocable Trusts
Here’s what keeps me up at night: families who think the $13.61 million federal estate tax exemption in 2024 means they’re safe. They’re not. That exemption drops to approximately $6 million in 2026, and if you live in a state with its own estate tax, the threshold could be much lower.
The irrevocable trust benefits for estate tax planning go beyond just removing assets from your taxable estate. When you transfer assets to an irrevocable trust, you’re freezing their value at today’s numbers. All future appreciation happens outside your estate, which can save millions for families with rapidly growing businesses or investment portfolios.
At the top federal rate of 40%, we’re talking about real money. A $20 million estate could face $8 million in taxes without proper planning. The strategies we use can eliminate most of that tax burden, but only if you act before the assets appreciate.
Navigating Trust Income Taxes
Trust income taxation is where families get their financial teeth kicked in. Those compressed tax brackets mean your trust hits the highest rates faster than a speeding ticket in a school zone. But here’s where smart planning pays off.
Distributable Net Income (DNI) becomes your friend when structured correctly. Income distributed to beneficiaries gets taxed at their individual rates, not the trust’s punitive brackets. For beneficiaries in lower tax brackets, this can save thousands annually.
The bottom line? Irrevocable trust benefits are real, but the tax mechanics require careful attention.
Setting Up & Maintaining an Irrevocable Trust in Arizona
Creating an irrevocable trust isn’t a DIY project. The drafting must be precise, the funding must be complete, and the ongoing administration must be flawless. Here’s what’s involved:
Drafting Precision: Every word matters in an irrevocable trust. Ambiguous language can undermine the entire structure.
Trustee Selection: Your trustee has enormous power and responsibility. They must be competent, trustworthy, and willing to serve.
Funding Process: The trust is worthless until it’s funded. This means retitling assets, updating beneficiary designations, and ensuring proper documentation.
Ongoing Administration: Irrevocable trusts require annual tax filings, regular distributions, and careful record-keeping.
Step-by-Step Formation Checklist
- Define Your Goals – What are you trying to accomplish? Asset protection? Tax savings? Medicaid planning?
- Choose Your Trust Type – Match the trust structure to your objectives
- Select Your Trustee – Professional or family member? Local or institutional?
- Draft the Documents – Work with experienced counsel to ensure proper language
- Fund the Trust – Transfer assets and update all relevant documentation
- Communicate with Beneficiaries – Make sure everyone understands their rights and responsibilities
- Establish Administration Procedures – Set up record-keeping and tax filing systems
- Plan for Reviews – Schedule regular reviews to ensure the trust continues to meet your needs
Can an Irrevocable Trust Be Changed or Terminated?
Despite the name, irrevocable trusts can sometimes be modified. Options include:
Court Reformation: If circumstances have changed substantially or there were mistakes in the original drafting, courts may approve modifications.
Beneficiary Consent: In some cases, all beneficiaries can agree to modify or terminate the trust.
Decanting: Arizona’s decanting statute allows trustees to move assets to a new trust with different terms.
The key is building flexibility into the original structure while preserving the irrevocable trust benefits that made the trust worthwhile in the first place.
Frequently Asked Questions about Irrevocable Trust Benefits
What assets can (and can’t) go into an irrevocable trust?
Here’s the reality – almost everything you own can go into an irrevocable trust, but some assets require special handling. Real estate, investment accounts, business interests, life insurance policies, cash, and personal property all transfer smoothly into irrevocable trusts.
The tricky ones? Retirement accounts come with complex rules that can trigger immediate taxation if handled incorrectly. S-corporation stock has restrictions on the number and type of trust beneficiaries allowed. And if you’re thinking about transferring your personal residence, you’ll want to consider a QPRT structure instead of a standard irrevocable trust.
I’ve seen families make costly mistakes by assuming all assets transfer the same way. A $2 million IRA transferred incorrectly can trigger immediate income taxes that wipe out years of irrevocable trust benefits.
How does the five-year Medicaid look-back period work?
Think of Medicaid as a detective with a five-year memory. When you apply for benefits, they examine every asset transfer you made during the previous five years. Any transfers to irrevocable trusts during this period can result in penalties that delay your eligibility for months or even years.
But here’s where the irrevocable trust benefits really shine – assets transferred more than five years before you need Medicaid are generally protected. I’ve helped families save their homes and life savings by planning ahead with properly structured Medicaid Asset Protection Trusts.
The math is brutal if you wait too long. Long-term care can cost $8,000 to $15,000 per month in Arizona. Without proper planning, families often spend down their entire life savings before qualifying for help.
Can my beneficiaries keep receiving SSI after they inherit through the trust?
Yes, but only if the trust is structured as a special needs trust with very specific language. These trusts provide what I call “supplemental support” – they can pay for things that improve your beneficiary’s quality of life without replacing government benefits.
The trust language must explicitly prohibit distributions that would affect benefit eligibility. It can pay for vacations, entertainment, and comfort items, but not food, shelter, or medical care that SSI or Medicaid already covers. Get this wrong, and your beneficiary could lose thousands in monthly benefits.
Conclusion
The irrevocable trust benefits we’ve discussed aren’t theoretical – they’re real advantages that can save your family millions in taxes, protect your assets from creditors, and ensure your legacy survives whatever challenges the future brings.
Yes, you give up some control. But in exchange, you gain something far more valuable: certainty. Certainty that your assets will be protected. Certainty that your family will be provided for. Certainty that your hard work won’t be lost to taxes, lawsuits, or poor decisions.
At Sudden Wealth Protection Law, we’ve helped hundreds of Arizona families steer these complex decisions. We understand that every family’s situation is unique, and we tailor our strategies to your specific needs and goals.
The question isn’t whether you can afford to set up an irrevocable trust – it’s whether you can afford not to. The families who wait until it’s too late often find that the cost of inaction far exceeds the cost of proper planning.
If you’re ready to explore how irrevocable trust benefits can protect your family’s future, contact us today. We’ll review your situation, explain your options, and help you make the decisions that will secure your legacy for generations to come.
Don’t wait until it’s too late. The best time to plan was yesterday. The second best time is today.

