

Why Irrevocable Trusts Feel Like Legal Gibberish (But Don’t Have To)
Irrevocable trusts for dummies can be explained simply: it’s a legal arrangement where you permanently transfer assets to a trustee who manages them for your beneficiaries, and once you sign, you can’t change your mind or take the assets back. (Except that a well-drafted trust will still have ways that you can amend or unwind it if needed.)
Quick Answer for Irrevocable Trusts:
- What it is: A permanent trust you can’t modify or revoke (except as specified in the trust document)
- Key parties: Grantor (you), Trustee (manager), Beneficiaries (recipients)
- Main benefits: Asset protection, estate tax reduction, Medicaid planning
- Main drawback: You lose control forever
- Common types: Life insurance trusts, charitable trusts, Asset Vault Trusts
I’ve watched too many Arizona families get blindsided by estate planning disasters. One day you’re planning your legacy, the next you’re staring at a probate mess that’s eating your kids’ inheritance alive.
The problem isn’t that irrevocable trusts are rocket science. The problem is that most explanations sound like they were written by aliens who speak only in tax code.
Here’s the truth: an irrevocable trust is like putting your assets in a vault and throwing away the key. (Except that there are ways to get a new key if needed.) You can’t easily get them back, but neither can creditors, lawsuits, or the IRS (in most cases). It’s a calculated sacrifice of control for protection.
I’m Paul E. Deloughery, and I’ve spent over 25 years helping Arizona families steer these exact decisions – including learning the hard way when I inherited $14 million in 2009 and lost most of it because I didn’t understand irrevocable trusts for dummies concepts myself.

Key terms for irrevocable trusts for dummies:
What Is an Irrevocable Trust?
Picture this: you’re building a vault for your most precious assets. But here’s the catch – once you seal that vault and hand over the keys, you can never open it again. That’s exactly what an irrevocable trust does to your property.
(However, in reality, it is not as dramatic as this. There are various ways of amending the trust or getting assets back. For example, you can appoint a trust protector. You can exercise a special power of appointment to transfer assets back to you. Or you can borrow from the trust.)
An irrevocable trust is a legal arrangement where you permanently transfer ownership of your assets to a trustee who manages them for your beneficiaries. The word “irrevocable” isn’t just legal decoration – it means you’ve burned the bridge behind you. No changing your mind, no taking assets back, no “oops, I need that million dollars for a new yacht.”
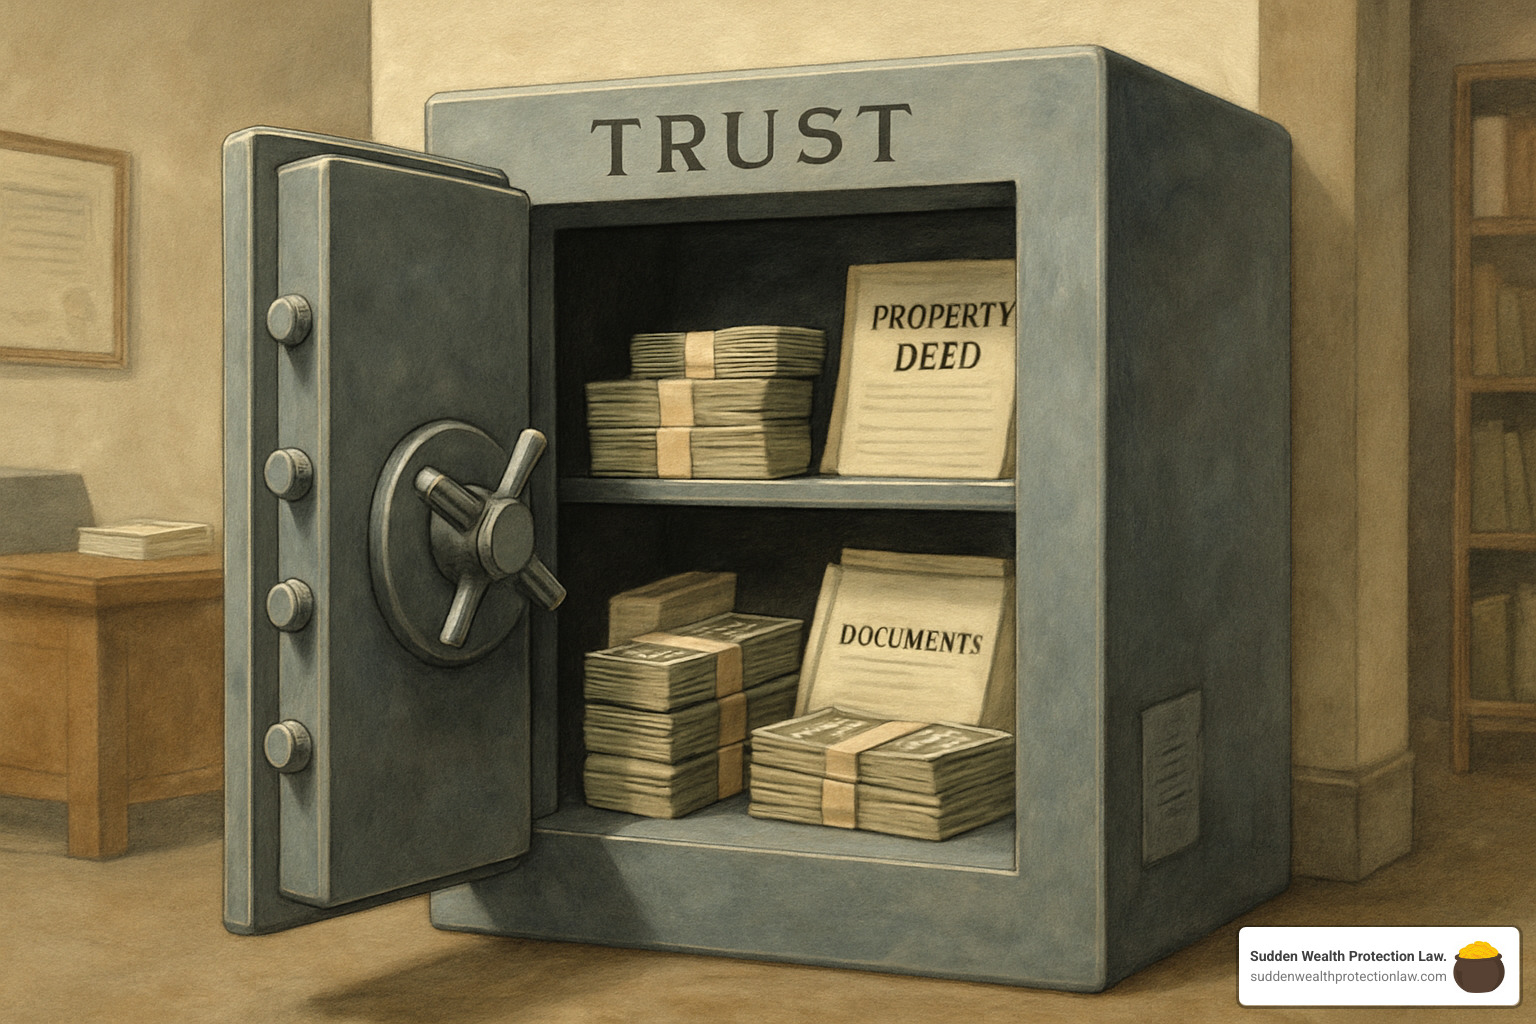
The trust operates through three key players: you (the grantor who creates and funds it), the trustee (who manages the assets), and the beneficiaries (who eventually receive distributions). It’s like hiring a professional manager for a business you can never own again.
Under Arizona law, once you transfer assets into an irrevocable trust, you’ve made what’s called a “completed gift.” You’re giving up all “incidents of ownership” – the legal term for your rights to control, modify, or benefit from those assets.
This complete surrender of control triggers gift tax consequences but also provides the protection benefits that make irrevocable trusts so powerful for estate planning, asset protection, and Medicaid planning.
Parties & Terminology for Dummies
The Grantor is you – the person who creates and funds the trust. Once you hand over those keys, your role is essentially over. You can’t fire the trustee, change the beneficiaries, or raid the trust fund for a spontaneous trip to Vegas.
The Trustee becomes the new owner and manager of your assets. They have what’s called a fiduciary duty – the highest legal standard of care. If they mess up or act selfishly, they can be sued and held personally liable.
The Beneficiaries are the people who will eventually receive distributions from the trust. They might get income annually, principal at certain ages, or funds for specific purposes like education or medical expenses.
A spendthrift clause is your protection against beneficiaries who might blow their inheritance on cryptocurrency or designer shoes. It prevents beneficiaries from pledging their future trust distributions as collateral and stops creditors from garnishing trust assets.
For more details on the grantor’s role and responsibilities, check out our guide on what is a trust grantor.
Irrevocable Trusts for Dummies: Key Differences & Types
Revocable trusts are like keeping your assets in your back pocket. You maintain complete control but get zero asset protection. Since you control everything, the law treats those assets as if they’re still yours. Creditors can reach them, they count toward estate taxes, and you get no protection.
Irrevocable trusts flip the script entirely. Once you transfer assets, you’ve essentially performed legal magic – those assets disappear from your estate for tax purposes. The trade-off? You can’t change your mind or get the assets back.
| Feature | Revocable Trust | Irrevocable Trust |
|---|---|---|
| Control | You keep it | You lose it |
| Flexibility | High | Low to none |
| Estate tax protection | None | Yes |
| Creditor protection | None | Strong |
| Gift tax consequences | None | It depends on how the trust is written |
“Irrevocable Trusts for Dummies” Type Cheat-Sheet
Irrevocable Life Insurance Trusts (ILITs) keep life insurance death benefits out of your taxable estate. The trust owns the policy, pays the premiums, and your estate never sees a dime.
Grantor Retained Annuity Trusts (GRATs) work with volatile assets. You transfer stock but keep receiving payments. If the assets appreciate beyond what you’re receiving, that extra growth passes to beneficiaries without additional gift taxes.
Special Needs Trusts solve how to provide for a disabled child without disqualifying them from government benefits.
Charitable Remainder Trusts let you transfer assets, receive income for life, get an immediate tax deduction, and the remainder goes to charity.
Asset Vault Trusts represent our proprietary approach to maximum protection with maximum flexibility. These incorporate a special power of appointment, giving you more options than traditional irrevocable trusts while maintaining strong creditor protection.
“Irrevocable Trusts for Dummies” vs Revocable Trusts
If you’re a surgeon worried about malpractice claims, a business owner staring down potential lawsuits, or someone with a hefty estate, “Irrevocable Trusts for Dummies” isn’t just a book title—it should be your battle plan. This kind of trust isn’t a luxury. It’s how smart people stay protected when life (or litigation) comes knocking.
Revocable trusts make sense when your primary concerns are avoiding probate and maintaining privacy. But they’re useless against creditors and provide zero estate tax benefits.
Consider your profession, net worth, and family situation. High-risk professionals often need the creditor protection that only irrevocable trusts provide. Families with estates exceeding the federal exemption need the estate tax benefits.
For a comprehensive comparison, review our detailed analysis of revocable trust vs irrevocable trust.
Why Set Up an Irrevocable Trust?
Let’s cut through the legal jargon and talk about why anyone would voluntarily give up control of their hard-earned assets. It’s not masochism – it’s strategic planning.
The biggest motivator is usually estate tax reduction. Right now, the federal estate tax exemption sits at $12.92 million per person in 2023. Sounds like a lot, right? But if you’re a successful business owner in Arizona, that number can sneak up on you faster than you’d think. Everything above that threshold gets hammered with estate taxes up to 40%.
Here’s where irrevocable trusts for dummies strategy comes in handy: when you transfer assets to an irrevocable trust, you’re essentially removing them from your taxable estate. It’s like taking money out of one pocket and putting it in a vault that doesn’t count toward your estate tax calculation.
You can fund these trusts gradually using the annual gift tax exclusion of $17,000 per recipient. Got three kids? That’s $51,000 per year you can move into trust without triggering gift taxes. Your spouse can do the same, doubling your annual capacity.
Lawsuit protection is another huge driver, especially if you’re in what I call the “lawsuit lottery” professions. Doctors, attorneys, business owners – anyone who wakes up knowing they could be sued before lunch. Once assets are properly transferred to an irrevocable trust, they’re generally beyond the reach of your personal creditors.
I’ve seen too many Arizona professionals lose everything because they thought their malpractice insurance would cover them. It doesn’t always work that way. An irrevocable trust creates a legal firewall between you and your assets.
Medicaid planning requires serious forethought. Arizona Medicaid has a five-year look-back period for asset transfers. If you transfer assets to an irrevocable trust more than five years before applying for Medicaid, those assets won’t count toward the eligibility limits. This isn’t a last-minute strategy – it’s a long-term play.
Privacy matters more than people realize. Trust assets and distributions remain private, unlike probate proceedings which become public record. Your family’s financial affairs stay out of the courthouse and away from nosy neighbors or opportunistic relatives.
Sometimes you’re not protecting assets from creditors – you’re protecting them from the beneficiaries themselves. An irrevocable trust can shield inheritances from a beneficiary’s poor judgment, creditors, or divorce proceedings. The spendthrift provisions prevent beneficiaries from pledging future distributions and keep trust assets safe from their personal financial disasters.
For a comprehensive look at all the benefits, check out our detailed guide on advantages of irrevocable trust planning.
Arizona-Specific Asset Protection & Asset Vault Trust
Arizona has specific statutes governing asset protection trusts, but the real innovation comes from how we structure these arrangements. Our Asset Vault Trust incorporates a special power of appointment that provides flexibility while maintaining maximum asset protection.
Think of it this way: most irrevocable trusts are like concrete – once they’re set, they’re permanent. The Asset Vault Trust is more like reinforced steel with flexible joints. It bends without breaking.
The trust includes provisions that allow the trustee or a trust protector to modify certain terms without court approval. This special power of appointment lets you adapt to changing circumstances while keeping the core asset protection intact. It’s flexibility within structure.
The Asset Vault Trust creates multiple layers of protection that discourage litigation and settlement demands. Under tax law, it’s classified as a 541 trust, which provides specific tax advantages while maintaining strong creditor barriers.
Here’s what makes it particularly effective: it provides strong creditor protection, allows for some flexibility through the special power of appointment, maintains estate tax benefits, and can be structured for multi-generational wealth transfer.
This isn’t about hiding assets – it’s about creating legal barriers that make it expensive and difficult for creditors to reach your wealth. The Asset Vault Trust makes pursuing your assets such a hassle that most creditors look for easier targets.
For more details on how this strategy works, visit our comprehensive guide on Asset Vault Trust services.
Setting Up an Irrevocable Trust: Step-by-Step
Creating an irrevocable trust for dummies isn’t something you tackle on a Saturday afternoon with a generic form from the internet. This is sophisticated legal work that requires precision.
Drafting the trust instrument is where the magic happens. This is a custom legal document that will govern your assets for decades. We specify exactly who gets what, when they get it, and under what circumstances.
Choosing your trustee is critical – you’re picking someone to manage your wealth according to your instructions, potentially for generations.
Funding the trust is where many people stumble. Real estate requires new deeds. Financial accounts need to be retitled. Business interests require formal assignment documents. If you don’t actually transfer the assets, you have expensive paperwork, not a functioning trust.
The trust needs its own tax identification number (EIN) from the IRS to file tax returns and open bank accounts as a separate legal entity.
Gift tax issues require careful attention. If you’re transferring more than $17,000 per beneficiary in 2023, you’ll need to file Form 709 with the IRS.
Picking the Right Trustee
Family member trustees know your family dynamics and won’t charge fees, but they may lack expertise to handle complex investments or tax issues.
Professional trustees like banks bring expertise and continuity, but they’re expensive and often impersonal.
Co-trustees can balance personal knowledge with professional expertise. You might name your daughter and a bank as co-trustees.
The key is matching the trustee to your specific needs and family situation. For more insights on the different roles, check out our guide on trust beneficiary vs trustee dynamics.
Funding Dos & Don’ts
Do transfer real estate with properly drafted deeds that clearly identify the trust as the new owner. Make sure the deed is recorded with the county recorder’s office.
Do retitle financial accounts in the trust’s name. Your bank will need a copy of the trust document and the EIN.
Do assign business interests with formal assignment documents. Review your operating agreements before making any transfers.
Don’t transfer retirement accounts directly to the trust – this creates immediate tax consequences. Instead, name the trust as the beneficiary.
Don’t forget about life insurance policies. These can be transferred to the trust, but there’s a three-year rule – if you die within three years of the transfer, the death benefit gets included in your estate anyway.
For detailed guidance on retirement account beneficiary rules, review the IRS guidance on retirement topics.
Managing, Modifying & Taxing an Irrevocable Trust
Once your irrevocable trust is funded, the trustee has ongoing duties that continue for the life of the trust.
Trustee Duties Include:
- Investing trust assets prudently
- Making distributions according to trust terms
- Keeping detailed records and accounts
- Filing annual tax returns
- Communicating with beneficiaries
- Protecting trust assets from creditors
Tax Complexity:
Irrevocable trusts face compressed tax brackets, meaning they hit the highest tax rates quickly. For 2023, trusts pay the top 37% rate on income over $14,450.
Grantor vs. Non-Grantor Trusts:
- Grantor Trust: You pay the income taxes (often preferred)
- Non-Grantor Trust: Trust pays its own taxes (higher rates)
Can You Ever Change an “Irrevocable”?
Despite the name, irrevocable trusts can sometimes be modified:
Decanting: Arizona allows trustees to “decant” trust assets from one trust to another with more favorable terms. It’s like pouring wine from one bottle to another.
Court Reformation: Courts can modify trusts if circumstances have changed substantially since creation.
Beneficiary Consent: If all beneficiaries agree and the modification doesn’t violate the trust’s material purpose, changes may be possible.
Trust Protector Powers: Some trusts include a “trust protector” with limited powers to modify trust terms without court approval.
Our Asset Vault Trust incorporates special powers of appointment that provide more flexibility than traditional irrevocable trusts.
What Happens When the Grantor Dies?
Distribution Requirements: The trust terms dictate how and when assets are distributed to beneficiaries. Some trusts terminate immediately, others continue for decades.
SECURE Act Rules: For retirement accounts in trust, the 10-year distribution rule typically applies, requiring complete distribution within 10 years of the grantor’s death.
Ongoing Administration: If the trust continues after death, the trustee’s duties continue until all assets are distributed.

Frequently Asked Questions about Irrevocable Trusts for Dummies
How is an irrevocable trust taxed each year?
Here’s where irrevocable trusts for dummies gets tricky – the tax situation depends entirely on how your trust is structured.
Grantor trusts mean you’re still on the hook for all income taxes, even though you can’t touch the assets anymore. Sounds unfair, right? Actually, it’s often a blessing in disguise. You’re essentially making additional tax-free gifts to your beneficiaries by paying their taxes for them. The trust grows without being nibbled to death by tax payments.
Non-grantor trusts file their own tax returns using Form 1041 and pay taxes on any income they don’t distribute. Here’s the kicker – trust tax brackets are compressed tighter than a submarine hatch. In 2023, trusts hit the top 37% tax rate on income over just $14,450. Your personal return doesn’t hit that rate until you’re making serious money.
Distribution taxation works like a pipeline. When the trust distributes income to beneficiaries, they pay the taxes on their personal returns at their own tax rates. The trust gets a deduction for what it distributes, avoiding double taxation.
The bottom line? Most of our clients prefer grantor trust status because it lets the trust assets grow faster, even though they’re paying taxes on income they can’t access.
Can an irrevocable trust qualify me for Arizona Medicaid?
Yes, but timing is everything. Arizona Medicaid has a five-year look-back period for asset transfers. Think of it as a five-year statute of limitations – if you transfer assets to an irrevocable trust more than five years before applying for Medicaid, those assets generally won’t count toward the eligibility limits.
The key requirements are non-negotiable: the trust must be truly irrevocable, you cannot retain any right to trust income or principal, and the transfer must occur more than five years before applying for benefits. The trust must also be properly structured to avoid Medicaid recovery after your death.
Medicaid Asset Protection Trusts (MAPT) are specifically designed for this purpose. They remove assets from your name while potentially allowing some indirect benefits. For example, the trust might pay for things that benefit you indirectly – like paying your adult child’s mortgage on a house where you live.
But here’s the reality check: Medicaid planning with irrevocable trusts for dummies requires crystal ball accuracy. You’re betting that you’ll need long-term care more than five years from now but won’t need access to those assets in the meantime. It’s not a decision to make lightly.
Who should consider an Asset Vault Trust instead of a basic irrevocable trust?
Our Asset Vault Trust is particularly valuable for people who need maximum protection but can’t stomach the rigidity of traditional irrevocable trusts.
High-risk professionals like doctors, attorneys, and business owners facing potential lawsuits find the improved asset protection features invaluable. The Asset Vault Trust creates multiple layers of defense that make it expensive and difficult for creditors to reach your wealth.
Wealthy families with estates exceeding the federal exemption need sophisticated estate tax planning combined with asset protection. The Asset Vault Trust handles both challenges while maintaining some flexibility for changing circumstances.
Multi-generational planning families want to transfer wealth across generations while keeping options open. The special power of appointment in our Asset Vault Trust provides more flexibility than traditional irrevocable trusts.
Business owners with valuable business interests need to protect personal assets from business liabilities. The Asset Vault Trust creates a legal firewall between your business risks and family wealth.
The Asset Vault Trust incorporates a special power of appointment that provides more flexibility than traditional irrevocable trusts for dummies while maintaining strong asset protection. It’s classified as a 541 trust under tax law, which provides specific advantages for income tax planning.
The key insight? If you need asset protection but worry about losing all control forever, the Asset Vault Trust might be your solution. It’s not for everyone, but for the right situation, it’s incredibly powerful.
Conclusion
Irrevocable trusts for dummies comes down to one simple truth: you’re making a permanent trade. You give up control today to protect your wealth tomorrow. It’s like burning the bridges behind you – there’s no going back, but sometimes that’s exactly what you need to keep the enemy at bay.
I’ve watched too many families wrestle with this decision. The control freaks hate it. The forward-thinkers accept it. The procrastinators? They usually end up paying the price in probate court or to creditors who could have been stopped cold with proper planning.
Here’s what I’ve learned after 25 years: irrevocable trusts for dummies isn’t about the complexity of the legal documents. It’s about understanding your priorities. Are you more afraid of losing control, or more afraid of losing your wealth to taxes, lawsuits, or nursing home costs?
The math is often compelling. Estate taxes can hit 40% on amounts over $12.92 million. Creditor judgments can wipe out a lifetime of work in a single lawsuit. Medicaid spend-down requirements can force you to impoverish yourself to qualify for benefits. An irrevocable trust can solve all three problems – but only if you’re willing to give up the keys.
The families who succeed with irrevocable trusts understand that true wealth protection sometimes requires sacrifice. They’d rather control their assets from the grave through carefully crafted trust terms than watch those assets get devoured by taxes and creditors while they’re still alive.
Not everyone needs this level of protection. If your estate is under the federal exemption and you’re not in a high-risk profession, a revocable trust might be sufficient. But if you’re dealing with substantial wealth, lawsuit exposure, or Medicaid planning needs, an irrevocable trust can be the difference between leaving a legacy and leaving a mess.
The Asset Vault Trust we’ve developed takes this protection to the next level. It’s still irrevocable – you still give up control – but it incorporates flexibility features that let you adapt to changing circumstances without going to court.
Don’t make the expensive mistakes I made with my own inheritance. The time to plan is before you need the protection, not after the lawsuit is filed or the nursing home bill arrives.
Schedule a consultation to discuss whether an irrevocable trust makes sense for your family. We’ll review your assets, your risks, and your goals to determine if this calculated sacrifice of control is worth the peace of mind it provides.
Your family’s financial future depends on the decisions you make today. Make them count.
For more information about our Asset Vault Trust services, visit our detailed guide on Asset Vault Trust strategies.

