

The Blunt Truth About the Term “Living Estate”
Living estate isn’t a real legal term—but if you’re searching for it, you’re likely confused and trying to figure out how to control your assets while you’re alive and ensure they pass smoothly when you’re gone. Here’s what you actually need to know.
What “Living Estate” Usually Means:
- Estate Plan – The legal strategy that controls your assets during life and after death.
- Living Trust (Revocable Living Trust) – A legal tool that lets you maintain full control of your assets while avoiding probate.
- Life Estate – A property arrangement where you live in a home for life, but someone else owns it after you die (probably not what you want).
The Real Question You’re Asking:
How do I protect my assets, avoid probate, and keep control of my property while I’m alive?
The answer isn’t a vague “living estate” concept. It’s a solid estate plan, usually built around a revocable living trust. Without one, you’re gambling with your family’s future. Probate can drag on for a year or more, cost thousands, and turn your private family matters into public court records.
Worse, a poorly designed plan—like an irrevocable life estate deed or a generic DIY will—can lock you into decisions you can’t undo. You could lose the right to sell your home, refinance, or change beneficiaries. And if you’re worried about Medicaid or nursing homes, one wrong move can trigger a five-year penalty that leaves your family holding the bag.
I’m Paul E. Deloughery, founder of Sudden Wealth Protection Law. I’ve spent over 25 years helping Arizona families steer these exact problems—including after I personally inherited $14 million and watched most of it disappear due to poor planning. Whether you’re dealing with a blended family, potential lawsuits, or just trying to avoid the probate nightmare, understanding the right tools for your living estate plan is the first step to taking control.
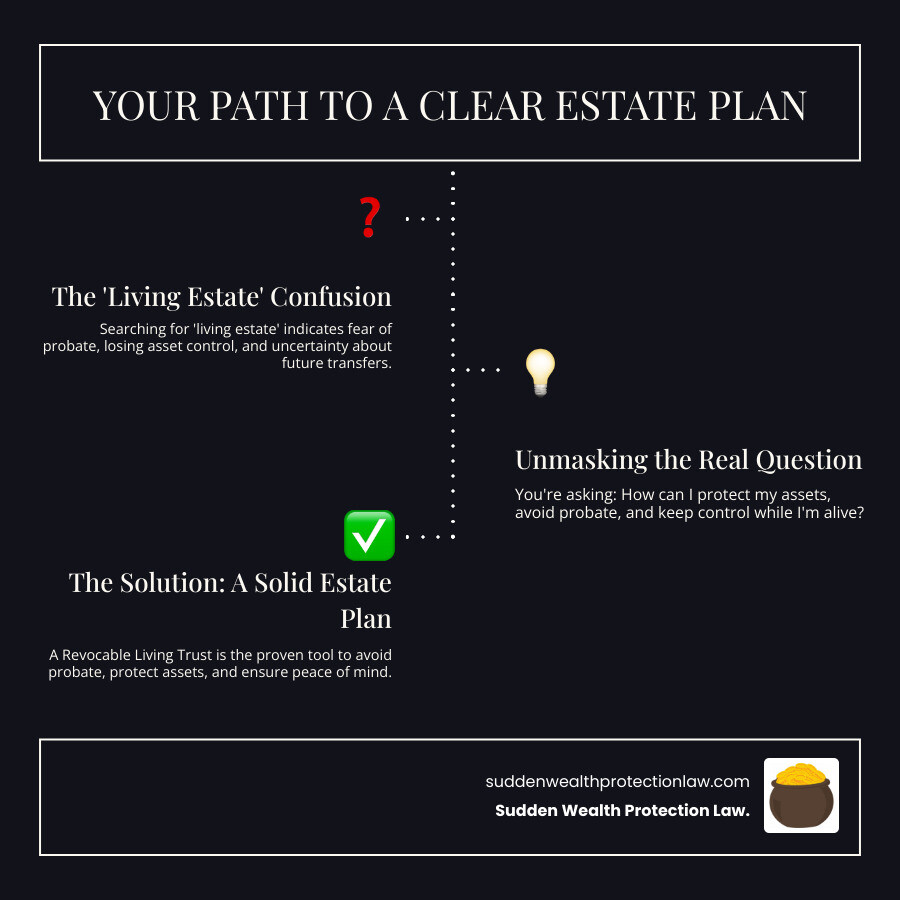
Quick look at living estate:
The Common Estate Planning Traps: What You Don’t Know Can Hurt You
Most people don’t wake up excited to talk about estate planning. It feels complicated and like something for “other people.” But the hard truth is that what you don’t know can devastate your family’s financial future.
The Probate Nightmare
The biggest monster in estate planning is Probate. It’s the court process for paying a deceased person’s debts and distributing their assets. In Arizona, without a proper plan, your family could be stuck in this system for months or years, facing thousands in legal fees while they’re grieving. And it’s all public record. Anyone can see what you owned, who got what, and how much your family is fighting over it. Probate is public, expensive, and painfully slow.
The DIY Plan Danger
Many people try to dodge probate with a simple will or a DIY plan. That’s like bringing a butter knife to a gunfight. A will still has to go through probate to be validated. You haven’t avoided anything—you’ve just created a roadmap for the court to follow. Those generic online forms don’t account for Arizona-specific laws and can lead to accidentally disinheriting someone, creating tax problems, or leaving loved ones vulnerable. That’s not protection—it’s a mistake waiting to explode.
The Control Problem
Fear of losing control often leads to inaction or using tools that strip away your flexibility. Some deeds, once signed, can’t be undone. You might think you’re securing your kids’ future, but you’re actually tying your own hands—unable to sell, refinance, or adapt. A simple will or poorly structured deed also leaves your family’s inheritance vulnerable to lawsuits or creditors.
To understand the difference between effective planning and just hoping for the best, you need to know which tools work. Learn more about the nuances of Wills and Trusts to ensure your wishes are legally sound.
The Problem with a Traditional Life Estate
Let’s clear up some confusion about the traditional life estate, because while it sounds like what people mean by “living estate,” it’s usually not what you want. It splits property ownership: you (the “life tenant”) can live in the property for life, and someone else (the “remainderman”) gets it when you die.
Here’s where it falls apart: Once you create a life estate, you lose control. You can’t sell or mortgage the property without the remainderman’s consent. Need to downsize or tap into home equity for medical bills? You have to ask your kids for permission. What if they say no?
The Creditor Risk
It gets worse. Because the remainderman is a partial owner, their financial trouble puts your home at risk. Their creditors can come after their interest in the property. Your house could get dragged into their bankruptcy, divorce, or lawsuit. You’ve made your assets vulnerable to your remainderman’s creditors.
Family Conflicts
Life estates can also spark family conflicts over maintenance or repairs. You’re stuck in an inflexible arrangement that doesn’t adapt to life changes like remarriage, family fallouts, or simply changing your mind. It’s a binding decision that strips away your flexibility. For more on how these work, see What Is a Life Estate?: Estate Planning Basics.
Medicaid and Your Assets: A Five-Year Minefield
Many Arizona families worry about Medicaid eligibility and long-term care costs, which can wipe out a lifetime of savings. Medicaid has strict asset limits and a brutal five-year look-back period.
The Transfer Penalty
If you transfer assets—like creating a life estate deed—within five years of applying for Medicaid, you could face massive penalties and be disqualified from benefits. For example, deeding your home to your kids while retaining a life estate is a transfer. If you need nursing home care within five years, that transfer could trigger a penalty period, leaving your family to pay out of pocket.
Why Planning Ahead Is Critical
A life estate can be useful for avoiding probate and protecting a home from Medicaid Estate Recovery after death, but only if done correctly and well in advance. The transfer can still be considered a gift during the five-year look-back period, triggering penalties. It’s a tightrope walk where one misstep can be costly. This is why planning ahead is critical. Waiting for a crisis leaves you with few options and maximum risk.
Getting It Right: The Tools That Actually Work for Your Estate Plan

Enough about what can go wrong. You came here for answers about living estate planning, and the goal of proper Estate Planning is simple: keep control of your assets, protect your family, and ensure your wishes are followed without court interference. Using the wrong tool can cost your family dearly.
The Revocable Living Trust: What You Probably Mean by “Living Estate”
When most people search for living estate, what they’re really looking for is a revocable living trust. This is the workhorse of modern estate planning.
A living trust is a legal document that holds your assets. During your lifetime, you are the grantor (creator), trustee (manager), and beneficiary, so you maintain complete control. When you pass away, a successor trustee you’ve named distributes everything according to your instructions—no court, no delays, no drama.
The beauty of a revocable living trust is that it’s revocable. You can change, update, or cancel it anytime. Life changes? Your trust changes with it. Unlike a traditional life estate where you give up control, a living trust lets you keep the keys to the kingdom. You can buy, sell, or refinance property without asking anyone’s permission.
Best of all, a properly funded living trust helps you avoid probate entirely. Your assets bypass the court system, saving your family time and money while keeping your financial affairs private. If you become incapacitated, your successor trustee can step in immediately to manage your affairs without a court-ordered conservatorship.
A living trust can also protect your kids’ inheritance from their own bad decisions, creditors, or divorce. Instead of a lump-sum payout, the trust can manage and distribute assets according to your instructions over time. If you’re ready to do this right, here’s How to Create a Living Trust in Arizona with proper legal guidance.
The Life Estate: A Niche Tool for Specific Situations
While not right for most, the traditional life estate has its place. Think of it as a specialty tool. It splits property ownership: you’re the life tenant (you live there for life), and you designate a remainderman (who inherits it automatically). The transfer happens outside of probate.
When does this make sense? Blended families and second marriages are the most common scenarios. For example, you can ensure your current spouse can live in the house for life, while guaranteeing your children from a prior marriage ultimately inherit it. A life estate locks that plan in.
However, the biggest problem is inflexibility. Once recorded, you can’t sell or refinance the property without the remainderman’s permission. You’re stuck. This is also treacherous territory for Medicaid planning due to the five-year look-back period and potential penalties.
The bottom line: A revocable living trust gives you flexibility and control. A life estate gives you neither. For most people, the trust is the clear winner. The life estate is for specific situations where its limitations are an accepted part of the plan. Proper Estate Planning means choosing the right strategy for your unique situation.
Advanced Protection: The Asset Vault Trust

Look, if you’ve made it this far, you’re not just worried about dodging probate. You’re thinking bigger. You’re a business owner, a professional, or someone who’s built real wealth and knows that the world is full of people who’d love to take a piece of it. Lawsuits. Creditors. Bad business deals. Even your own kids’ future divorces or bankruptcies. A basic living estate plan—even a solid revocable living trust—won’t shield you from all of that.
This is where we move beyond the basics and into serious asset protection territory. And here’s the problem with most irrevocable trusts: they’re inflexible as hell. Once you put assets in, you’re locked in. No changes, no adjustments, no “oops, I changed my mind.” That might sound great for protecting assets from creditors, and it is—because legally, you no longer own them. But it’s also terrifying for most people. Life changes. Kids grow up. Family dynamics shift. What if you need to redirect assets or adjust your plan?
Enter the Asset Vault Trust. Think of it as that bank vault in the image—secure, impenetrable, but with a hidden mechanism that gives you access when you need it. This isn’t some off-the-shelf product. It’s a strategy we’ve refined specifically for Arizona families who need maximum protection without sacrificing all control.
The Asset Vault Trust is an irrevocable trust, which is the gold standard for asset protection. Once assets are in, they’re generally considered outside your ownership, making them untouchable by future creditors or lawsuits against you. If someone sues you, they can’t get to what’s in the vault. If you’re facing financial trouble, those assets are shielded. This is the fortress you need if you’re in a high-risk profession, own a business, or have accumulated significant wealth.
But here’s our secret weapon: the Asset Vault Trust incorporates a special power of appointment. This means that while the assets are locked away and protected, you or a trusted person you designate can still redirect where those assets ultimately go among a class of beneficiaries. You maintain a degree of flexibility that most irrevocable trusts simply don’t offer. It’s protection with a pressure release valve. You’re not giving up everything; you’re just putting it somewhere safe while keeping the keys in the right hands.
This isn’t a tool for everyone. If your primary concern is just avoiding probate and keeping things simple, a revocable living trust is your answer. But if you’ve seen the bloodshed of litigation, if you know what it’s like to be on the wrong end of a lawsuit, or if you’re building generational wealth that needs to survive not just your lifetime but your kids’ and grandkids’ lives, this is the shield you need. It’s the difference between hoping your assets stay safe and knowing they’re protected.
This strategy fits seamlessly into comprehensive Family Trust planning, especially when you’re thinking beyond just one generation. It’s about building a legacy that can’t be picked apart by creditors, lawsuits, or bad decisions down the line.
Your Top Questions Answered
Let’s get practical. After years of helping Arizona families steer their living estate planning, I’ve heard the same questions come up again and again. The confusion usually stems from not understanding what you’re actually signing up for—or what happens when life throws you a curveball. So here are straight answers to the concerns I hear most often.
What are the responsibilities of a life tenant?
If you’re the life tenant in a traditional life estate, you’ve got real responsibilities, not just rights. You’re living in the home, sure, but you’re also holding that property in trust for the future owners. Think of yourself as a caretaker with a lifetime pass, not the absolute owner.
Property taxes are on you—every year, no exceptions. You’re also responsible for keeping the property insured, because letting coverage lapse puts everyone’s interest at risk. Then there’s maintenance and upkeep. You can’t let the place fall apart. Routine repairs, keeping the lawn from turning into a jungle, fixing that leaky roof—all of that falls on your shoulders.
If there’s a mortgage on the property, you’re typically responsible for making those payments, at least the interest portion. And here’s where it gets legal: there’s something called the doctrine of waste. It’s an old legal principle that basically means you cannot damage or devalue the property. If you let it deteriorate, strip out valuable fixtures, or otherwise trash the place, the remaindermen can actually sue you for damages. You have to act like a responsible owner, even though you can’t sell or mortgage the place without permission. It’s a weird position to be in, honestly—all the responsibility, but not all the control.
Can a will override a trust or a living estate?
This is one of the most persistent myths in estate planning, and I need to shut it down hard: No, a will does not override a trust. If you’ve properly funded your revocable living trust—meaning you’ve actually retitled your assets into the trust’s name—then the trust document controls what happens to those assets, period. Your will doesn’t get a say. In fact, most people with a living trust also have what’s called a “pour-over will,” which basically says, “Hey, if I forgot to put something in my trust, dump it in there now.” But that still requires probate for those forgotten assets, which is exactly what you were trying to avoid.
A will cannot override a life estate deed either. A life estate is created by a recorded deed, a legal document that fundamentally changes the ownership structure of your property. Once that deed is filed with the county recorder, the property’s fate is sealed. Your interest as the life tenant simply evaporates when you die, and the remaindermen automatically become full owners. Your will has no power over that transfer—it’s already been decided by the deed itself.
The order of precedence is clear: deeds and trusts trump wills when it comes to the specific property they govern. Your will is the catch-all for anything that doesn’t have another mechanism for transfer, but it’s not the boss of your properly planned assets.
How is a life estate terminated or valued?
A traditional life estate typically ends in the most natural way possible: when the life tenant dies. At that point, the remaindermen simply present a death certificate, and boom—they’re the full owners. No probate, no court involvement, no hassle. That’s actually the main appeal of a life estate for some folks.
But what if circumstances change? What if the life tenant wants to sell, or everyone decides this arrangement isn’t working? Mutual agreement to terminate is possible, but here’s the catch: everyone has to agree. The life tenant and every single remainderman must be on board. You’ll typically need to work with an attorney to draft and record a new deed that unwinds the life estate arrangement. If even one remainderman digs in their heels—maybe they’re going through a divorce, or they’re broke and counting on that future inheritance, or they’re just being difficult—you’re stuck. This is that inflexibility I keep warning you about.
Valuing a life estate gets a bit technical, especially if you’re dealing with taxes or trying to sell the property before the life tenant passes. The IRS has actuarial tables that calculate the present value of both the life tenant’s interest and the remaindermen’s interest. These tables factor in the life tenant’s age and current interest rates to determine what each party’s share is worth today. The older the life tenant, the less their interest is worth, and the more valuable the remaindermen’s future ownership becomes. This valuation matters for capital gains taxes, gift tax implications, and even Medicaid calculations. It’s not guesswork—it’s math, and it can have real financial consequences.
Conclusion: Stop Guessing and Start Planning
Here’s the thing: if you’ve been searching for “living estate,” you’re not lost—you’re actually exactly where you need to be. You’ve reached that point where you know hoping for the best isn’t a plan, and you’re ready to stop guessing and start protecting what matters.
Let’s recap the blunt truth: “living estate” isn’t a real legal term. But what it tells me is that you’re asking the right questions. You want clarity. You want control. You want to know your family won’t be dragged through probate court, fighting over assets while lawyers rack up billable hours. You want to ensure that if something happens to you—whether that’s tomorrow or thirty years from now—your wishes are followed, your assets are protected, and your loved ones are taken care of.
For most Arizona families, the answer is a revocable living trust. It’s the workhorse that gives you complete control during your lifetime, keeps your family out of the probate nightmare, and provides the flexibility to adapt as life throws its inevitable curveballs. It’s not sexy, but it’s solid. It’s the difference between leaving your family a roadmap and leaving them a mess.
For those facing bigger risks—business owners, professionals, anyone who’s seen what a lawsuit can do to a lifetime of hard work—we go deeper. Our Asset Vault Trust offers maximum protection from creditors and lawsuits while maintaining the flexibility that standard irrevocable trusts simply can’t match. It’s the vault door with a hidden key, and it’s designed specifically for Arizona families who refuse to leave their legacy vulnerable.
I’ve spent over 25 years in this field, and I’ve personally watched $14 million disappear because of poor planning. I’ve seen families torn apart over estates that should have brought them together. I’ve seen hardworking people lose everything because they made one wrong move or trusted the wrong advice. That’s why we do this work differently at Sudden Wealth Protection Law. We don’t do cookie-cutter plans. We don’t hand you a binder and wish you luck. We build defenses that actually work, custom to your unique situation, your family dynamics, and your Arizona-specific needs.
The first step is always the hardest, but it’s also the most important. Stop second-guessing. Stop putting it off. Stop letting confusion or fear dictate your family’s future. Get a real plan, built by someone who’s seen the bloodshed and knows how to prevent it. Whether you need help setting up a trust, navigating probate, or protecting assets you’ve spent a lifetime building, we’re here to provide the compassionate, expert guidance you deserve. Get help with probate and trust administration and take control of your legacy today.

