

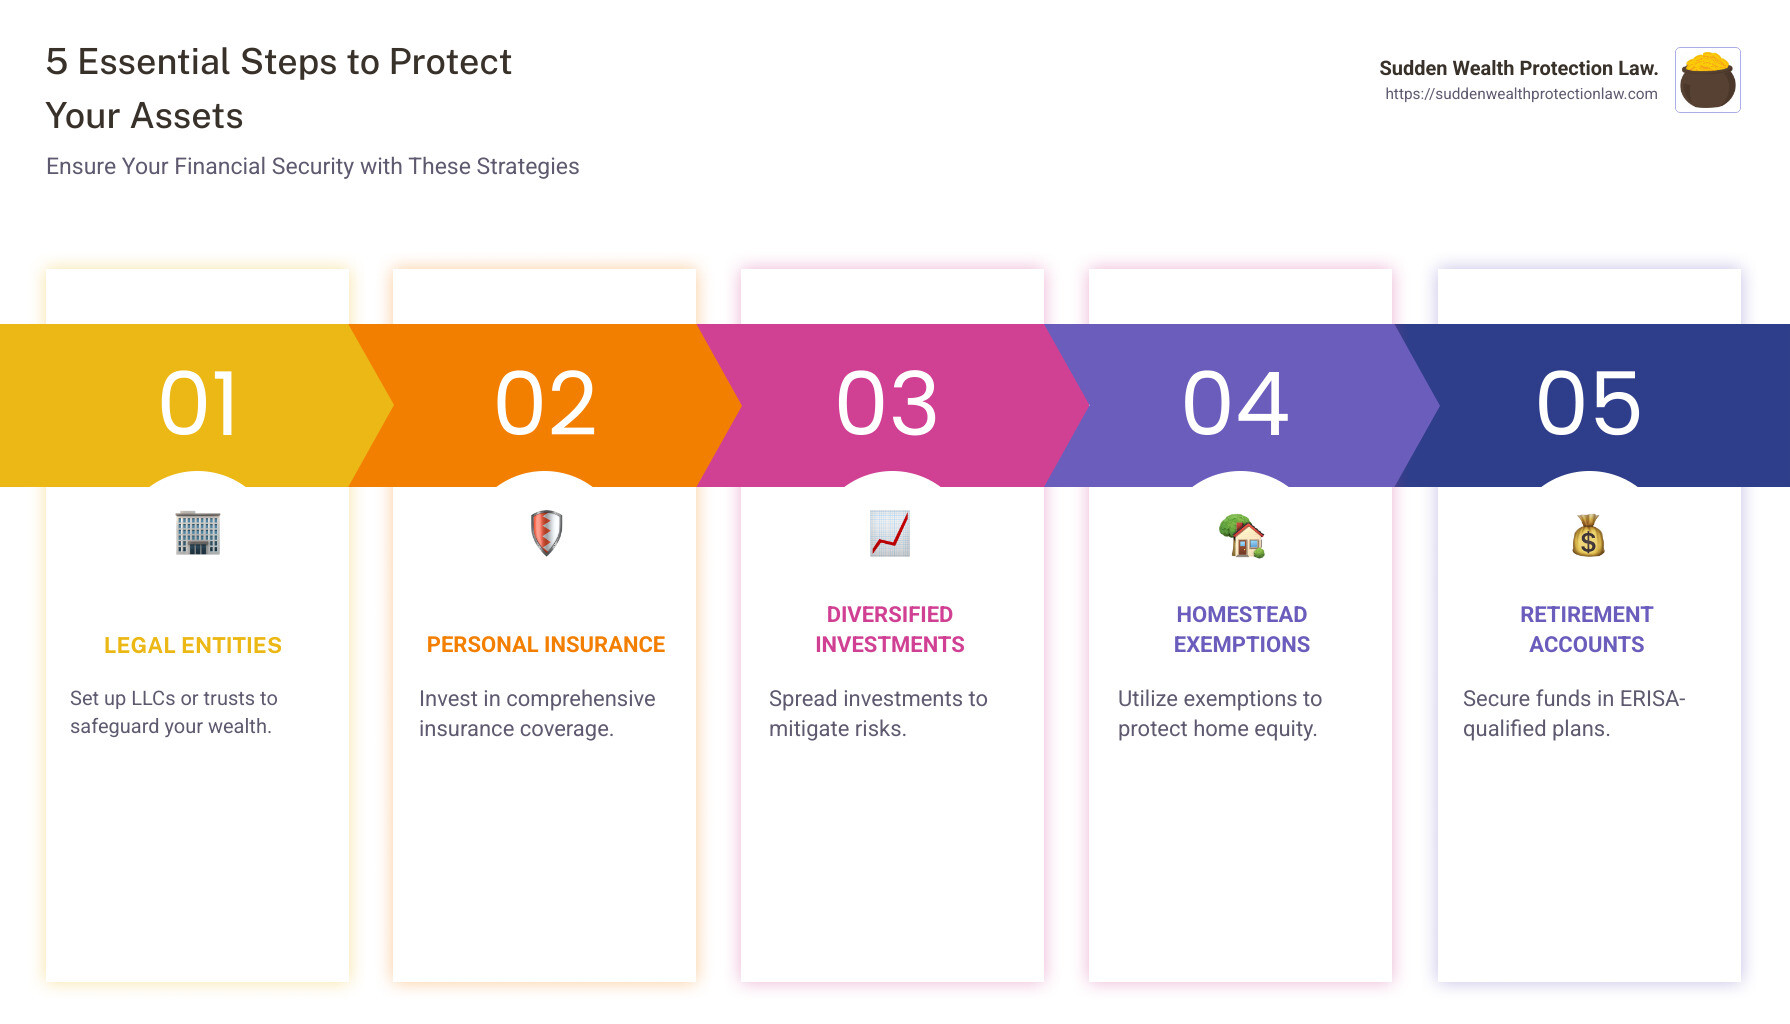
Protect your assets with proactive strategies to safeguard your net worth and ensure financial security. For those concerned about potential creditor claims or life’s uncertainties, here are essential steps:
- Use legal entities like LLCs or trusts for protection.
- Invest in personal insurance coverage.
- Diversify your portfolio through smart investments.
- Shield significant assets with homestead exemptions or retirement accounts.
Navigating personal and financial vulnerabilities can be daunting, yet asset protection is crucial for peace of mind.
My name is Paul E. Deloughery, and I’ve spent over 25 years guiding individuals through asset protection, helping them secure their family’s future and manage wealth effectively. This introduction sets the stage to dig deeper into these protective strategies.
Protect your assets terms explained:
– asset protection definition
– strategic asset protection
– tax strategies and asset protection
Understanding Asset Protection
Asset protection is about creating a safety net for your wealth. It’s like building a fortress around your assets to keep them safe from unexpected threats, such as lawsuits or creditors.
Asset Protection Trust
An asset protection trust is a powerful tool. Imagine it as a secure vault where you place your valuables. These trusts are designed to hold your assets away from creditors while still allowing you to benefit from them. They are legal arrangements that put a trustee in charge of your assets, meaning that you technically do not own them anymore. This makes it hard for creditors to claim them.
For example, if someone sues you, the assets in your trust are typically out of reach. This can give you peace of mind knowing that your wealth is protected.
Legal Entities
Using legal entities like limited liability companies (LLCs) or corporations can also protect your assets. These structures separate your personal finances from your business. If your business faces a lawsuit, your personal assets are usually not at risk.
Imagine your business as a separate person. If that “person” gets into trouble, your personal savings and property are safe. This separation is crucial for anyone running a business, big or small.
Financial Plan
A financial plan is your roadmap to security. It includes strategies to grow and protect your wealth over time. Think of it as a blueprint that outlines how you will manage your money, invest wisely, and prepare for the unexpected.
A good financial plan considers all aspects of your financial life. It should include insurance, investment strategies, and estate planning. By having a solid plan, you can be ready for whatever life throws your way.
Asset protection is not just for the wealthy. It’s for anyone who wants to ensure their hard-earned money is safe. By understanding and utilizing tools like asset protection trusts, legal entities, and comprehensive financial plans, you can build a strong defense around your wealth.
Strategies to Protect Your Assets
Protecting your assets is like building a sturdy shield around your financial life. Here are some strategies to keep your wealth safe:
Business Entities
Setting up a business entity can be a smart move. Think of it as creating a new “person” for your business. This separates your personal assets from your business liabilities.
- Limited Liability Companies (LLCs): Offer flexibility and protection. Your personal assets are usually safe if your LLC faces legal trouble.
- Corporations: Provide strong protection, but with more rules to follow. They are ideal for larger businesses with complex structures.
- Limited Partnerships: Good for investors who want to limit their liability. Only your investment in the partnership is at risk, not your personal assets.
Personal Insurance
Insurance acts as a safety net. Here are some types to consider:
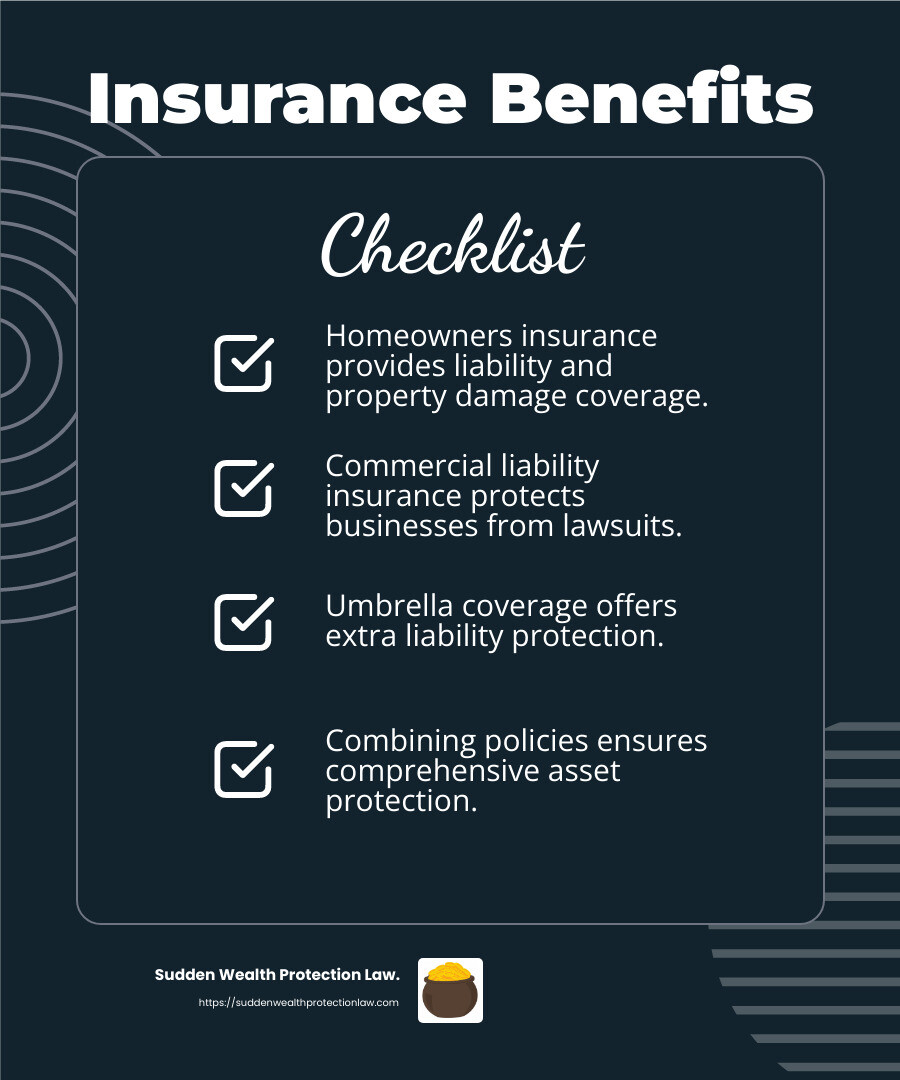
- Homeowners Insurance: Protects your home from damage and liability claims.
- Commercial Liability Insurance: Shields your business from lawsuits.
- Umbrella Coverage: Provides extra protection beyond your standard insurance policies.
Retirement Accounts
Retirement accounts offer special protection under federal laws. They not only help you save for the future but also protect your savings from creditors.
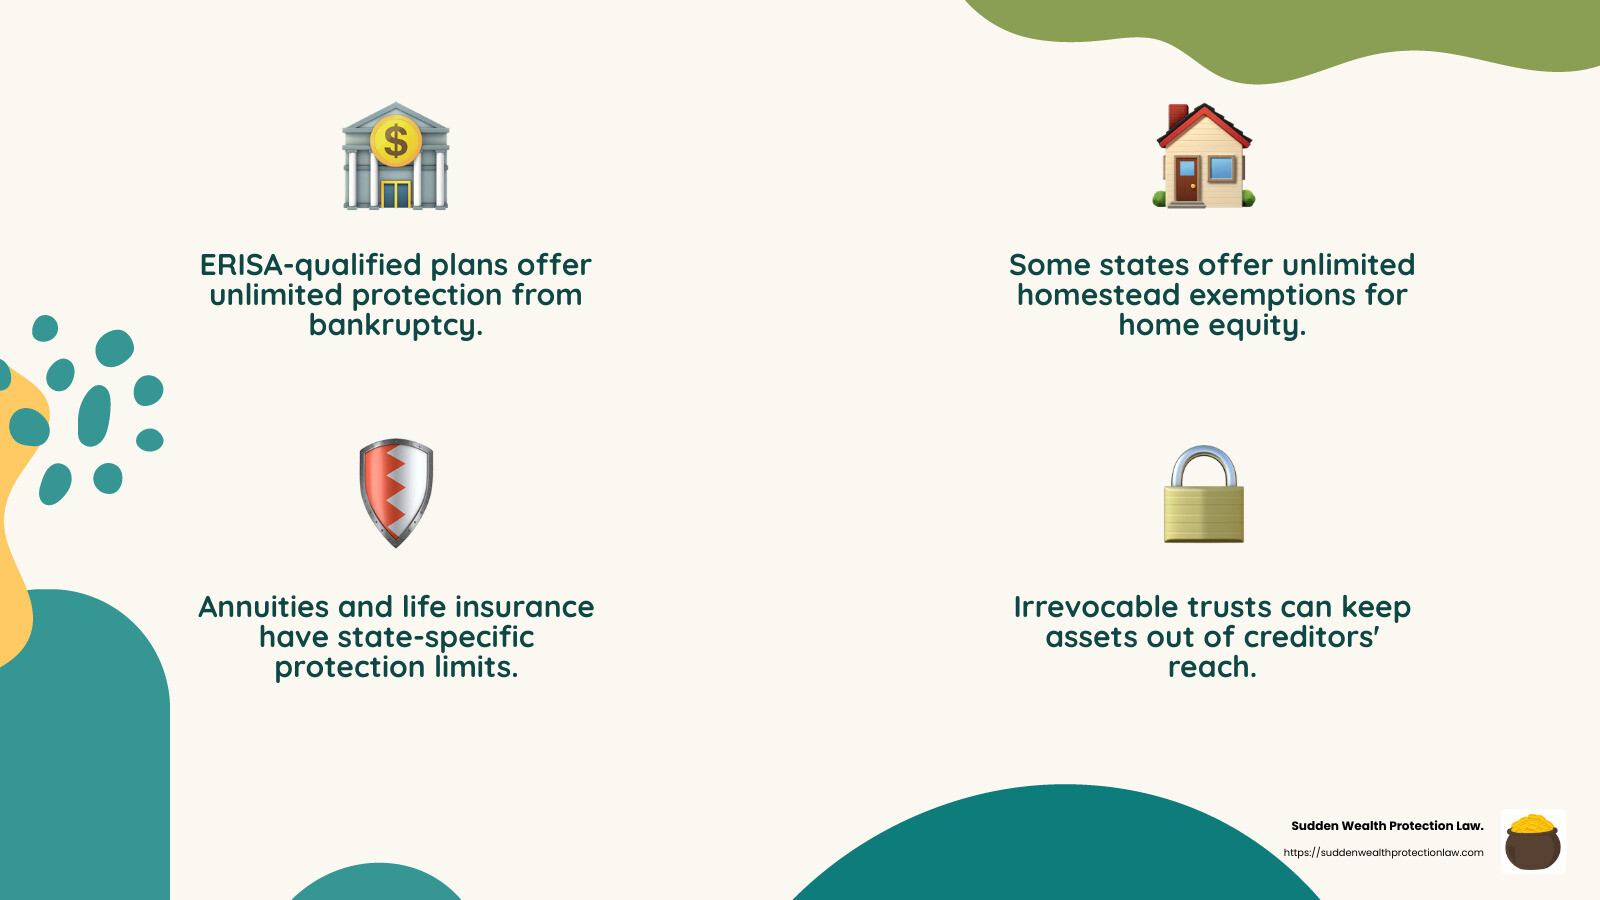
- ERISA-Qualified Plans: These include 401(k)s and offer unlimited protection from bankruptcy.
- IRAs: Have a protection cap, but still offer a layer of security against creditors.
Homestead Exemptions and Titling
Your home can be a safe haven with the right protections.
- Homestead Exemptions: Some states offer unlimited protection for your home equity. Check your state’s laws to see what applies to you.
- Titling: How you title your property matters. Options like tenancy by the entirety can protect your home from creditors of one spouse.
Annuities and Life Insurance
These can be secure financial tools, providing both peace of mind and asset protection.
- State Protection: States vary in how they protect annuities and life insurance. Some offer unlimited protection, while others have limits.
Asset Transfer
Transferring assets can safeguard them from creditors.
- Irrevocable Trusts: Once assets are placed here, they are generally out of reach from creditors.
- Gifting: Carefully giving assets to loved ones can protect them, but should be done with planning to avoid insolvency.
With these strategies, you can protect your assets and secure your financial future. Each method has its own benefits and considerations, so it’s wise to consult with professionals to tailor a plan that suits your needs.
Protect Your Assets with Business Entities
When it comes to safeguarding your wealth, setting up a business entity is a powerful strategy. It acts like a protective barrier between your personal assets and business liabilities. Let’s explore how different entities can help you protect your assets.
Limited Liability Companies (LLCs)
LLCs are popular for a reason. They offer flexibility and robust protection. If your LLC faces legal issues or debts, your personal assets—like your house or savings—are usually off-limits to creditors. This separation is key to keeping your personal wealth secure.
Here’s why LLCs are favored:
- Flexibility: LLCs can be custom to fit small businesses or large enterprises.
- Tax Options: Enjoy the tax benefits of a partnership while protecting your personal assets like a corporation.
- Simplicity: Easier to set up and maintain compared to corporations.
Corporations
Corporations provide strong asset protection but come with more regulations.
- Structure: Ideal for larger businesses with complex operations.
- Liability Shield: Like LLCs, corporations protect personal assets from business liabilities.
- Types: Choose between S Corporations and C Corporations. Each has unique tax implications and ownership rules.
While corporations offer excellent protection, they require strict adherence to formalities and paperwork.
Limited Partnerships (LPs)
A Limited Partnership is another way to protect your assets, especially for investors.
- Limited Liability: As a limited partner, your liability is capped at your investment in the partnership.
- Role Flexibility: General partners manage the business and bear more liability, while limited partners are passive investors.
LPs are great for those who want to invest without taking on full business risks.
By choosing the right business entity, you can effectively protect your assets from potential business risks. Each type—LLC, corporation, or limited partnership—offers unique benefits. It’s essential to weigh these options carefully and consult with professionals to find the best fit for your financial goals.
In the next section, we’ll explore how personal insurance plays a crucial role in asset protection.
Personal Insurance for Asset Protection
Insurance is a cornerstone of any solid asset protection plan. It acts as a safety net, catching you when unexpected events threaten your financial security. Let’s explore three key types of insurance that can protect your assets: homeowners insurance, commercial liability insurance, and umbrella coverage.
Homeowners Insurance
Homeowners insurance is essential for protecting one of your most valuable assets—your home. It covers damage to your property from events like fires, storms, or theft. But it doesn’t stop there. This insurance also protects you if someone is injured on your property and decides to sue.
- Liability Coverage: Ensures you’re protected if someone gets hurt in your home.
- Property Damage: Covers repairs or replacement of your home and belongings.
- Peace of Mind: Gives you confidence that you’re protected against common risks.
Commercial Liability Insurance
For business owners, commercial liability insurance is a must-have. It shields your business from financial losses due to injuries or damages caused by your operations, products, or employees.
- Protection Against Lawsuits: Covers legal fees and settlements if your business is sued.
- Employee Coverage: Protects your business if an employee causes damage or injury.
- Essential for All Businesses: Whether you run a small shop or a large corporation, this insurance is crucial.
Umbrella Coverage
Umbrella insurance is like a backup plan for your existing policies. It kicks in when your other insurance limits are maxed out, providing additional protection.
- Extra Liability Coverage: Offers protection beyond your home or auto insurance limits.
- Cost-Effective: Provides substantial coverage at a reasonable cost.
- Wide-Ranging Protection: Covers a variety of scenarios, from personal injury claims to property damage.
By integrating these insurance types into your asset protection strategy, you can safeguard your wealth against unforeseen events. Homeowners insurance, commercial liability insurance, and umbrella coverage work together to ensure that your assets remain secure, no matter what life throws your way.
In the next section, we’ll dig into how retirement accounts can be a powerful tool for asset protection.
Utilizing Retirement Accounts
Retirement accounts are not just for saving money for your golden years—they also offer a powerful way to protect your assets. Let’s explore how ERISA-qualified plans and IRA protection can help shield your wealth.
ERISA-Qualified Plans
ERISA, or the Employee Retirement Income Security Act, provides strong protections for certain retirement plans. These include 401(k)s, 403(b)s, and defined-benefit plans.
- Unlimited Bankruptcy Protection: Assets in these plans are shielded from creditors in bankruptcy cases.
- Employee and Employer Contributions: Both are protected, offering peace of mind for your retirement savings.
- Exceptions: These protections do not apply to tax levies from the IRS or in cases involving qualified domestic relations orders (QDROs).
IRA Protection
Individual Retirement Accounts (IRAs) also offer asset protection, although the rules differ slightly from ERISA plans.
- Bankruptcy Protection Cap: IRAs have a federal protection cap of $1 million against bankruptcy proceedings. This amount adjusts for inflation, ensuring continued relevance.
- State Variations: Some states may offer additional protections, so check your local laws to understand the full extent of IRA protection available to you.
- Rollovers: Funds rolled over from ERISA-qualified plans to an IRA enjoy unlimited protection in bankruptcy, making rollovers a strategic move for some.
Key Considerations
While retirement accounts offer significant protection, it’s important to be aware of some limitations:
- Non-Bankruptcy Cases: These protections primarily apply to bankruptcy. In cases like lawsuits or divorce, state laws will dictate the level of protection available.
- Inherited IRAs: These do not receive the same level of protection as your own IRAs. Consider strategies like a Standalone Retirement Trust (SRT) to protect inherited accounts.
By leveraging ERISA-qualified plans and understanding IRA protections, you can build a strong defense for your retirement savings. This strategic use of retirement accounts not only ensures financial security for the future but also fortifies your assets against potential threats today.
Next, we’ll explore how homestead exemptions and titling can further improve your asset protection strategy.
Homestead Exemptions and Titling
When it comes to protecting your assets, especially your home, homestead exemptions and titling strategies play a crucial role. Understanding these can help safeguard your home equity and provide peace of mind.
Home Equity Protection
In certain states, homestead exemptions offer a powerful way to protect the value of your home from creditors. Here’s how it works:
- Unlimited Exemptions: States like Texas and Florida provide unlimited homestead exemptions. This means all of your home equity can be protected in the event of bankruptcy.
- State-Specific Rules: Not all states offer such generous protections. It’s essential to check your state’s specific rules to know how much of your home equity is shielded.
- Bankruptcy Protection: A homestead exemption can prevent creditors from forcing the sale of your home to satisfy debts, providing a vital layer of security.
Tenancy by the Entirety
This form of property ownership is another effective tool for asset protection, especially for married couples:
- Joint Ownership: Tenancy by the entirety allows married couples to own property as a single legal entity. This means if one spouse is sued, creditors cannot claim the property.
- State Availability: Not all states recognize tenancy by the entirety. States like Florida, New York, and Virginia do, offering married couples an added layer of protection.
- Limitations: If both spouses are liable for a debt, this form of ownership doesn’t offer protection. Additionally, if the non-debtor spouse passes away, the property may become vulnerable.
Combining homestead exemptions with strategic titling like tenancy by the entirety can significantly improve your asset protection strategy. These methods not only protect your home equity but also offer a sense of security in uncertain times.
In the next section, we’ll dig into how annuities and life insurance can further bolster your financial security and asset protection plan.
Annuities and Life Insurance
Annuities and life insurance are more than just financial products; they are essential tools for securing your financial future and safeguarding your assets. Let’s explore how these can protect your wealth.
State Protection
The level of protection for annuities and life insurance varies by state. This means where you live can significantly impact how well these assets are shielded from creditors.
- Unlimited Protection: Some states, like Florida, offer unlimited protection for annuities and life insurance. This means these assets can’t be touched by creditors, no matter their value.
- Limited Protection: Other states may offer limited protection. For example, Oregon provides up to $500 per month in annuity income protection. It’s crucial to check your state’s laws to understand the level of protection available.
- Legal Advice: Before making decisions, consult with a licensed attorney in your state. They can provide specific guidance based on local laws and your financial situation.
Financial Security
Annuities and life insurance are not just about protection; they also offer financial security for you and your loved ones.
- Income Stream: Annuities can provide a steady income stream during retirement, ensuring you have funds to cover living expenses.
- Life Insurance Benefits: Life insurance can cover funeral expenses, pay off debts, and provide ongoing income for your family. It acts as a financial safety net in the event of your untimely demise.
- Long-Term Care: Some life insurance products offer long-term care options. This means if you need support in your later years, your policy can help cover those costs, reducing the financial burden on your family.
By understanding the protection and benefits offered by annuities and life insurance, you can make informed decisions that bolster your overall asset protection strategy. These tools not only protect your assets but also ensure financial stability for you and your loved ones.
Next, we’ll tackle some frequently asked questions about asset protection to further clarify how you can protect your assets effectively.
Frequently Asked Questions about Asset Protection
What does protect your assets mean?
Protect your assets means using strategies to keep your wealth safe from creditors, lawsuits, and other claims. It’s about creating a shield around your money, property, and other valuable items so they can’t be easily taken away. Asset protection involves legal tools like trusts, insurance, and business entities to safeguard what you own.
How do I protect my assets from being seized?
To protect your assets from being seized, consider these steps:
- Legal Entities: Set up structures like Limited Liability Companies (LLCs) or corporations. These can separate your personal assets from your business, making it harder for creditors to reach your personal wealth.
- Insurance Coverage: Get personal insurance, such as homeowners or umbrella insurance. These policies can cover unexpected liabilities and help protect your assets from claims.
- Asset Protection Trusts: These trusts can hold your assets securely, keeping them out of reach from creditors. They are designed to provide a legal barrier while allowing you to control your assets.
- Retirement Accounts: Use ERISA-qualified plans and IRAs. Federal laws offer significant protection to these accounts, especially in bankruptcy cases.
What is the best asset protection?
The best asset protection strategy often combines multiple methods to create a robust defense. Here’s a look at some effective options:
- LLC: An LLC is a flexible business structure that offers liability protection. It separates your personal assets from business liabilities, which can be crucial if your business faces legal challenges.
- Asset Protection Trust: This is a powerful tool for keeping assets safe from creditors. By transferring assets into a trust, you can maintain control while shielding them from legal claims.
- Insurance: Comprehensive insurance coverage is essential. It acts as the first line of defense against unexpected events that could threaten your assets.
Each person’s situation is unique, so it’s wise to consult with an asset protection attorney to tailor a strategy that fits your needs. By understanding these concepts and tools, you can take proactive steps to protect your assets and ensure financial security.
Conclusion
At Sudden Wealth Protection Law, we understand that safeguarding your wealth is crucial for your family’s future. Our mission is to provide personalized legal solutions that cater to your unique needs. Our services are designed to give you peace of mind and ensure that your assets are secure from potential threats.
One of our key strategies is the Asset Vault Trust. This is an innovative tool that offers robust asset protection by removing your assets from personal ownership. The trust is private and cannot be found through public records, making it an ideal choice for those seeking privacy and security. Unlike other trusts, the Asset Vault Trust allows you to modify its terms and conditions and even return assets to yourself without cost or tax implications. This flexibility ensures that your wealth remains protected while still being accessible when needed.
We pride ourselves on offering compassionate and expert guidance. Our team, led by founding attorney Paul Deloughery, specializes in Arizona estate planning and is dedicated to teaching families and business owners how to protect their assets effectively. We aim to empower the next generation to be responsible stewards of their inherited wealth.
If you’re ready to take the next step in securing your financial future, we invite you to explore our asset protection services. Let us help you create a comprehensive plan to protect your assets and achieve your financial goals.

