

What Is a Settlor of a Trust?
The key player you’ll encounter when you’re first exploring trusts, you’ll quickly encounter a key player: the settlor of a trust. Simply put, this is the person who breathes life into a trust by creating it, funding it with assets, and establishing all the rules for how it will work.
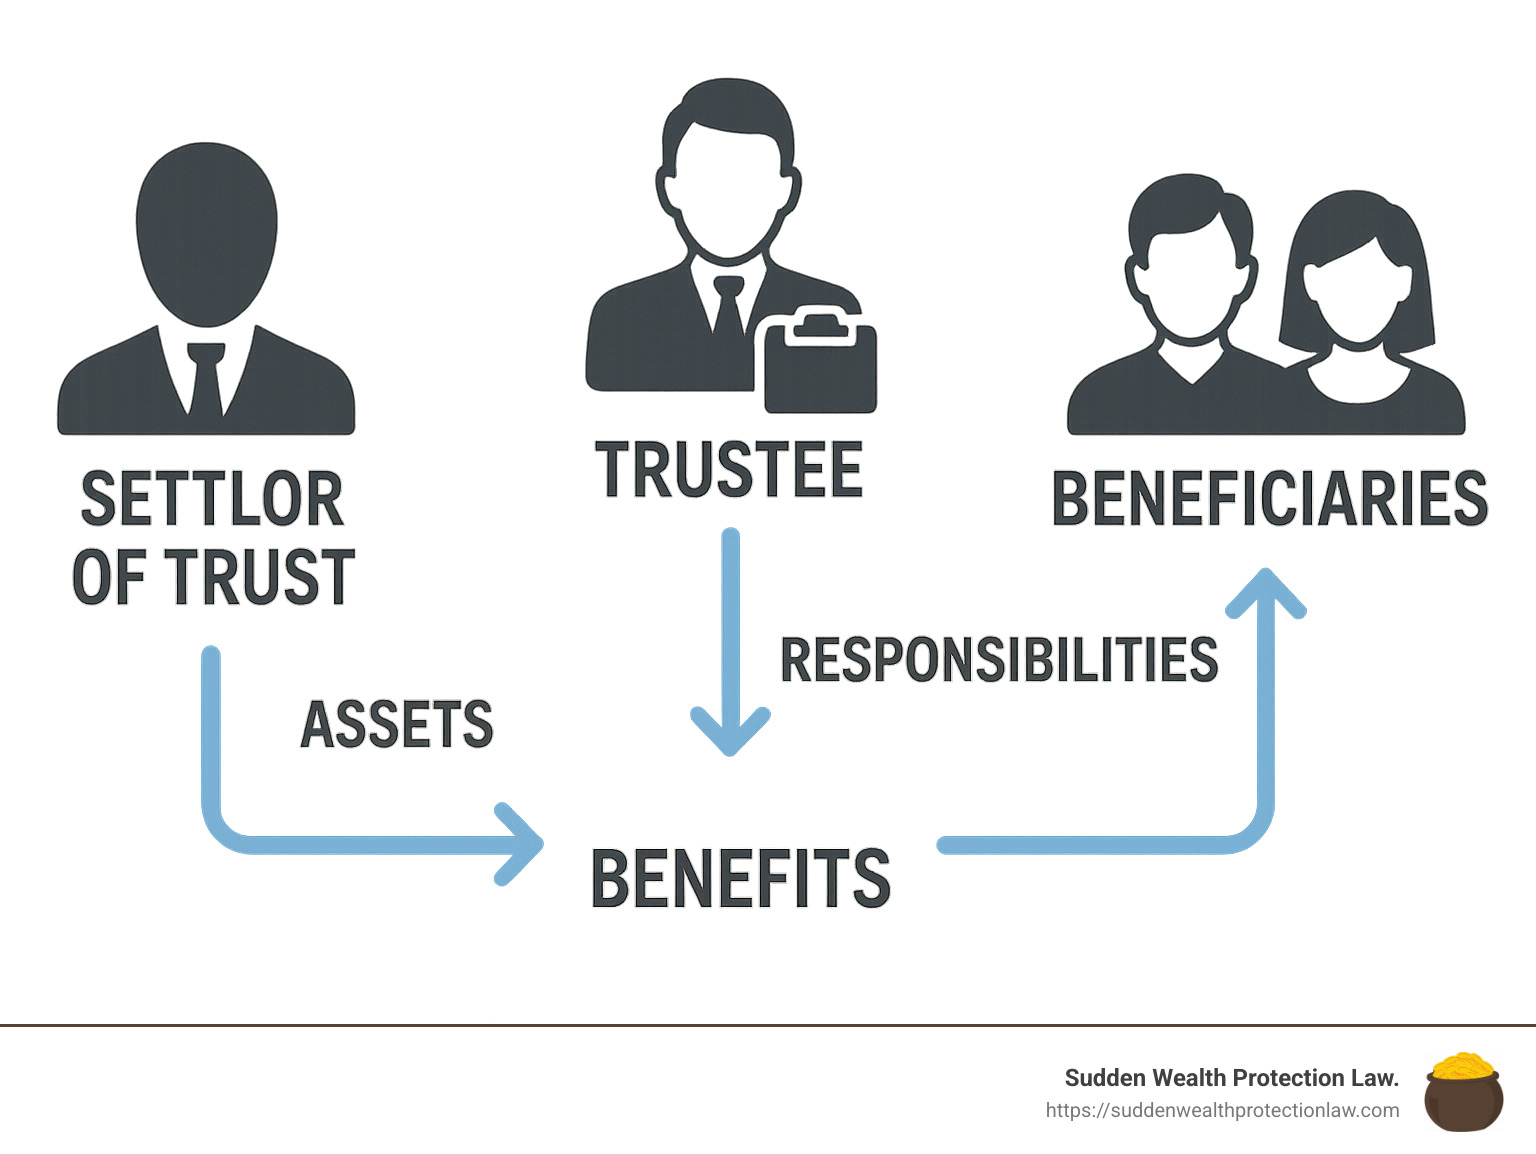
Think of the settlor of a trust as the architect of the entire trust arrangement. Without someone stepping into this role, a trust simply cannot exist. The settlor decides what property goes into the trust, who will manage those assets (the trustee), and who will ultimately benefit from them (the beneficiaries).
Settlor of a Trust: Quick Definition
- Definition: The person who creates and funds a trust
- Alternative Names: Grantor, trustor, trustmaker, donor
- Legal Requirements: Must be at least 18 years old and of sound mind
- Primary Function: Transfers property to trustee for benefit of beneficiaries
- Role After Creation: Depends on trust type (retains control in revocable trusts, relinquishes control in irrevocable trusts)
I’ve seen many clients surprised to learn that about 34% of trust creators (according to a recent LegalZoom survey) name themselves as both settlor of a trust and trustee. This approach makes perfect sense for many families, as it allows you to maintain control of your assets during your lifetime while still planning thoughtfully for the future.
While the settlor’s role might seem straightforward at first glance, it carries significant legal weight and responsibilities. The decisions you make as a settlor will determine how your assets are protected, managed, and distributed—sometimes affecting generations of your family to come.
If you’d like a concise overview of how the concept of a settlor developed in common-law jurisdictions, the Settlor article on Wikipedia provides helpful historical background and additional context.
As someone who has guided families through this process for over 25 years, I’ve seen how a well-designed trust can provide incredible peace of mind. When you serve as the settlor of a trust, you’re not just filling out paperwork—you’re creating a legacy that honors your wishes long after you’re gone.
Need to understand related terms? Check out these helpful resources:
– trustee versus trustor
– trustor vs trustee in deed of trust
– grantor trustee
Why Understanding the Settlor Matters
Getting clear about the settlor of a trust role isn’t just a legal technicality—it’s essential for effective estate planning. As the foundation of any trust arrangement, your decisions as settlor directly shape your family’s financial future in several important ways.
First, the choices you make determine how well your assets are protected from potential creditors and unexpected lawsuits. A properly structured trust can create a significant shield around your family’s wealth.
Second, understanding the settlor role helps you steer whether your estate will avoid probate—that time-consuming, often expensive, and very public court process that many families prefer to skip. In Arizona, a well-crafted trust can help your loved ones bypass this entirely.
The timing and conditions of how your beneficiaries receive their inheritance also stems directly from your decisions as settlor of a trust. Whether you want to provide immediate access or create thoughtful age-based distributions, this all flows from your initial trust design.
Tax implications matter too. The American College of Trust and Estate Counsel notes that over 20% of Americans aged 55 and older have established living trusts, with the settlor often serving as the initial trustee. This growing trend reflects how many families are recognizing the power of trusts for both tax efficiency and smooth wealth transfer.
Perhaps most valuable of all is the peace of mind that comes from knowing your assets will be managed exactly according to your wishes—even after you’re gone. By fully understanding the settlor’s role, you can make confident decisions about your estate plan and ensure your legacy remains protected for generations to come.
Who Is the Settler of a Trust?
When you hear the term settlor of a trust, we’re talking about the person who brings a trust to life. This is the individual who creates the trust by transferring their assets into it and establishing all the rules for how it will operate.
Think of the settlor as the architect of the entire trust arrangement. As the Wex Definitions Team puts it so clearly, “The settlor is the party that creates a trust, usually the donor.” Without the settlor’s vision and assets, there simply would be no trust.

For someone to legally become a settlor of a trust, they need to meet some basic requirements. They must be at least 18 years old in most places, be of sound mind when creating the trust, actually own the assets they’re putting into the trust, and have the legal right to transfer those assets.
The settlor makes all the important decisions that shape how the trust will work, including:
- Picking the trustee(s) who will manage the trust assets
- Naming the beneficiaries who will receive benefits from the trust
- Setting the terms for how assets will be managed and distributed
- Deciding whether the trust can be changed later (revocable) or not (irrevocable)
One thing many people don’t realize is that creating a trust isn’t complete until the settlor actually transfers assets into it. Legal experts often say, “A trust does not exist until the settlor expresses an intention for the trust to exist and transfers the settled sum to the trustee.” This process of “funding the trust” is what truly brings the trust arrangement to life.
Alternate Names for the Settlor of a Trust
If you’re diving into trusts, you might feel like you’ve stumbled into a linguistic maze. The person who creates a trust goes by several different names, which can be confusing at first!
Here in Arizona, you’ll often hear the term trustor being used, especially in real estate transactions. If you’re reading IRS documents or tax regulations, you’ll probably see grantor instead. When a trust is created mainly as a gift, the creator might be called a donor. Some modern estate planners prefer the straightforward term trustmaker.
As one legal expert explains, “In estate planning law, Settlor, Trustor, and Trustmaker are interchangeable terms.” Some lawyers also use Transferor, Donor, or Grantor to mean the same thing.
Why so many names for the same role? It often comes down to regional preferences and legal traditions. The California Probate Code tends to use “settlor,” while IRS regulations favor “grantor.” But regardless of what term you encounter, remember they all refer to the same person – the one who establishes the trust and transfers assets into it.
Core Duties of a Settlor of a Trust
Creating a trust isn’t just about signing a document – it involves several important responsibilities that the settlor of a trust must fulfill.
First, the settlor needs to clearly express their intentions through a properly drafted trust document. This isn’t the place for vague language or ambiguity. The document must clearly outline the trust’s purpose, the powers of the trustee, the rights of the beneficiaries, and the rules for managing and distributing assets.
Second, the settlor must actually fund the trust. As I often tell my clients at Sudden Wealth Protection Law, a trust without assets is like a car without gas – it might look nice, but it won’t get you anywhere! The settlor needs to identify which assets will go into the trust, complete the legal transfers, ensure proper documentation, and make sure the trustee acknowledges receipt of the assets.
Third, selecting trustees is perhaps one of the most crucial decisions a settlor makes. This person (or persons) will be responsible for managing the trust assets according to the settlor’s wishes. The choice between family members and professional trustees often depends on the complexity of the assets and family dynamics. It’s also wise to name successor trustees who can step in if the original trustee can’t serve.
Finally, the settlor must clearly define who will benefit from the trust. Beneficiaries might be named individuals like family members, classes of people such as “my descendants,” organizations like charities, or even the settlor themselves in certain trust arrangements.
As Patricia Louise Nelson eloquently put it, “The Settlor is the ‘king of the world’ in the context of a trust.” This captures the settlor’s ultimate authority in establishing how their trust will operate. While this power comes with significant responsibility, it also provides the settlor with the peace of mind that comes from knowing their wishes will be honored and their loved ones will be cared for.
Legal Requirements to Become a Settlor of a Trust
Creating a trust isn’t something just anyone can do. To be a valid settlor of a trust, you need to meet specific legal requirements that ensure your trust will stand strong if ever challenged.
Think of these requirements as the foundation of your trust – without them, the entire structure could collapse. Here’s what you need to know:
First, you must be an adult. In Arizona and most other states, this means you need to be at least 18 years old. A minor simply can’t create a legally binding trust.
You also need to have what lawyers call “sound mind.” This doesn’t mean you need to be a genius! It simply means you understand what property you own, who your family members are, what you’re doing with your property, and how these pieces fit together into your plan.
I’ve seen cases where trusts were challenged because family members claimed the settlor wasn’t thinking clearly when they signed the documents. That’s why we often document capacity when creating trusts, especially for older clients.
Settlor of a trust requirements also include actually owning the assets you’re placing in trust. This might seem obvious, but it’s a crucial legal point – you can’t put your neighbor’s house in your trust, no matter how much you might want to!
You must also clearly intend to create a trust. Saying “I hope someone takes care of my children with this money” isn’t enough. You need to demonstrate a clear intention to create a legally binding arrangement.
The paperwork requirements vary depending on what you’re putting in your trust:
For personal property like bank accounts or investments, a written document isn’t always legally required, but it’s strongly recommended. Without written documentation, proving the existence of your trust could become a nightmare.
For real estate, you’ll definitely need proper documentation. In Arizona, transferring property to your trust requires a properly executed deed. Skip this step, and your real estate might end up in probate despite your trust.
If you’re creating a trust through your will (called a testamentary trust), you’ll need to follow all will requirements, including proper signing and witnessing.
The Three Certainties Every Settlor of a Trust Must Satisfy
Every settlor of a trust must satisfy what legal scholars call “the three certainties” – fundamental principles established in the landmark case Knight v Knight that form the backbone of trust law.
The first certainty is intention. You must clearly show you intend to create a trust, not just express a hope or wish. In the fascinating case of Paul v Constance (1977), the court found that even informal statements like “the money is as much yours as mine” established a trust relationship. But generally, you’ll want to be much more explicit!
The second certainty is subject matter. You need to clearly identify what property you’re placing in the trust. Vague descriptions won’t work. In Palmer v Simmonds (1854), a trust for “the bulk of my estate” was deemed invalid because it wasn’t specific enough. Your trustee needs to know exactly what they’re responsible for managing.
The third certainty is objects – meaning your beneficiaries must be clearly defined. As Lord Denning stated in Re Vandervell’s Trusts (No 2), “It is clear law that a trust (other than a charitable trust) must be for ascertainable beneficiaries.” You need to either name specific people or define a class of beneficiaries that can be clearly identified.
There’s a Latin phrase that captures this concept perfectly: “Certum est quod certum reddi potest” – it is certain if it can be made certain. Your trust terms must provide enough clarity that your trustee can do their job with confidence.
Special Needs & Public Benefits Exceptions
Creating trusts for loved ones who receive public benefits like Medicaid or SSI requires special consideration about who can serve as a settlor of a trust. These rules exist to ensure the trust doesn’t disqualify your loved one from receiving their benefits.
For special needs trusts that won’t count against Medicaid and SSI resource limits, the settlor must be one of these people:
– The beneficiary themselves
– A parent or grandparent of the beneficiary
– A guardian or conservator of the beneficiary’s estate
– A court
Age matters too. Individual special needs trusts are only available to beneficiaries age 64 or younger, while pooled trusts have no age limit. This is a critical distinction that can make or break your planning strategy.
When someone acts under a Durable Power of Attorney to establish a trust, that document must specifically authorize them to do so. The same goes for guardians and conservators – the court appointment must explicitly grant them the authority to create a trust.
I’ve seen heartbreaking situations where well-meaning families created trusts that accidentally disqualified their loved ones from benefits because they didn’t follow these specific rules. That’s why working with an attorney who understands public benefits planning is so important.
At Sudden Wealth Protection Law, we help Arizona families steer these complex requirements every day. We ensure that your loved ones can maintain their essential benefits while still receiving the supplemental support they need through a properly structured trust.
Creating a Trust: Step-by-Step Workflow
Creating a trust isn’t as complicated as it might seem, though it does require attention to detail. As the settlor of a trust, you’ll follow a clear path from idea to implementation, ensuring your wishes are legally protected for years to come.
Think of creating a trust like building a custom home. First, you need a vision of what you want, then detailed blueprints, and finally the actual construction. Let’s walk through this process together:
Start by clarifying exactly what you’re trying to accomplish. Are you hoping to avoid probate? Protect assets from creditors? Provide for a loved one with special needs? Maybe you’re planning for business succession or want to leave a charitable legacy. Your goals will shape every decision that follows.
Based on these objectives, you’ll choose the most appropriate trust structure. A revocable living trust offers flexibility and control during your lifetime. An irrevocable trust provides stronger asset protection. Our Asset Vault Trust combines protection with flexibility through a special power of appointment. Special needs trusts help beneficiaries maintain government benefits, while charitable trusts support causes you care about.
The heart of your trust is the trust document itself. Working with an experienced attorney (like our team at Sudden Wealth Protection Law), you’ll create a document that includes a clear statement of your intent, identifies all parties involved, describes the trust property, outlines the trustee’s powers and duties, and establishes distribution terms. Don’t forget to include provisions for amending or terminating the trust and naming successor trustees.
Once drafted, you’ll formally execute the trust document according to Arizona law. This typically requires your signature as the settlor of a trust and notarization. Some trusts may also require witnesses.
The #1 Mistake Settlors Make: Forgetting to Fund the Trust
You can hire the best estate planning lawyer in Arizona, sign a perfectly drafted trust document, and still blow it. Why? Because you didn’t actually put anything into the trust.
Your trust is like an empty vault until you place assets inside it. That means executing new deeds for real estate, changing account titles for financial assets, assigning business interests, updating beneficiary designations, and transferring personal property through proper assignment documents.
A trust that isn’t funded is just paper. If you don’t transfer ownership, your assets may still end up in probate—the very mess your trust was supposed to avoid.
Your trustee must formally accept their role, usually by signing an acceptance document. And don’t forget to document the initial “settled sum”—often a nominal amount like $10—which officially activates the trust.
As one estate planning expert puts it, “A trust is not legally created until the settled sum is handed over and a receipt is issued by the trustee.” This formal acknowledgment is the final piece that brings your trust to life.
It’s no surprise trust creation is up 25% over the past decade. People are finally learning that a properly funded trust saves their families enormous time, expense, and heartache.
At Sudden Wealth Protection Law, we walk you through every step—from setup to funding—so your trust works exactly how you intended. This ensures that your Inter Vivos Trust is properly established to protect what matters most to you.
Can the Settlor of a Trust Also Be Trustee or Beneficiary?
“Can I wear multiple hats in my own trust?” This is one of the most common questions we hear at Sudden Wealth Protection Law. The short answer is yes – and understanding these dual roles can help you create a more effective estate plan.
Many people are surprised to learn they can serve as their own trustee. In fact, this arrangement is incredibly common with revocable living trusts. As the settlor of a trust, you create the document, but then you also step into the role of trustee, managing your own assets during your lifetime. When you’re no longer able to serve – due to incapacity or death – your named successor trustee seamlessly takes over.
A 2023 LegalZoom survey found that 34% of trust creators name themselves as both settlor and trustee. This makes perfect sense – why hand over control of your assets while you’re still perfectly capable of managing them yourself?
That said, serving as your own trustee comes with responsibilities. You’ll need to:
- Keep trust assets clearly separated from personal assets
- Follow your own trust instructions (yes, even when you wrote them!)
- Act in all beneficiaries’ best interests, not just your own
- Maintain proper records of trust transactions
As Patricia Louise Nelson colorfully describes it, the settlor is the “king of the world” in the trust context, while the trustee is the “worker bee.” When you combine these roles, you must respect the distinct legal responsibilities of each position.
You can also be a beneficiary of your own trust. In revocable living trusts, this is standard – you’ll typically remain the primary beneficiary during your lifetime, with assets passing to others after your death. Even with irrevocable trusts, you might retain some beneficial interest, though this requires careful planning.
One important note: a settlor of a trust generally cannot be the sole beneficiary of their trust. This would merge the legal and beneficial interests, potentially invalidating the entire arrangement. There must be at least one other beneficiary (even if that person only receives benefits after your lifetime).
When a settlor retains beneficial interests in an irrevocable trust, this affects both asset protection and tax treatment. As one legal expert explains, “A settlor-interested trust carries specific Income Tax, Capital Gains Tax, and Inheritance Tax consequences.”
I’ve helped hundreds of clients steer these overlapping roles, designing trust structures that balance control, protection, and tax efficiency based on each family’s unique circumstances. With proper planning, you can maintain appropriate control while still achieving your long-term estate planning goals.
Post-Creation Limits on the Settlor of a Trust
Once your trust is signed and funded, what control do you retain? The answer depends largely on whether you’ve created a revocable or irrevocable trust.
With revocable trusts, you maintain tremendous flexibility as the settlor of a trust. Think of it as keeping a set of master keys to your own creation. You can amend the terms whenever you wish, add or remove assets freely, change beneficiaries, replace trustees, or even revoke the entire trust if it no longer serves your needs. You’ll also typically continue receiving income and principal from the trust assets.
This ongoing control explains why revocable trusts offer no asset protection from your creditors – the assets remain effectively yours in the eyes of the law. It’s also why these assets are still considered part of your taxable estate when you pass away.
Irrevocable trusts present a very different scenario. Creating an irrevocable trust is more like sending your assets on a one-way journey. Once established, your control becomes significantly limited. You generally cannot change the trust terms, remove assets, easily modify beneficiaries, or directly control the trustee’s actions.
However, even with irrevocable trusts, you aren’t necessarily locked into a completely rigid arrangement. You might retain certain limited powers, such as:
- The right to replace trustees (as a non-fiduciary power)
- A limited power of appointment to redirect assets among a defined group of beneficiaries
- The right to receive income in some specialized trust arrangements
- The ability to veto certain trustee decisions in limited circumstances
In Arizona, we often incorporate special powers of appointment in our Asset Vault Trust to provide flexibility while maintaining asset protection benefits. This approach gives you some indirect influence without compromising the trust’s protective features – the best of both worlds.
As one legal expert wisely observed, “To avoid the perception that the settlor’s declaration of trust is revocable, the settlor should be unrelated to the trustee and the beneficiaries of the trust.” This independence is particularly important for irrevocable trusts designed for asset protection or tax benefits.
A recent survey by the National Association of Estate Planners & Councils found that 60% of estate planning professionals recommend appointing a professional trustee rather than a family member for irrevocable trusts. This separation helps establish the trust’s independence and strengthens its protective features.
Understanding these post-creation limitations helps you set realistic expectations about your ongoing relationship with your trust. When properly structured, your trust will continue working exactly as you intended – providing for your loved ones and protecting your legacy for generations to come.
Settlor, Trustee, Beneficiary: Roles Compared
Understanding how the settlor of a trust fits into the larger trust picture means recognizing the distinct roles each party plays. Think of a trust as a carefully choreographed dance with three main performers, each with their own unique moves and responsibilities.
The trust relationship creates what legal experts call a “split ownership” arrangement. This three-way relationship can be understood by comparing their core functions:
| Role | Primary Function | Legal Relationship to Assets | Fiduciary Duty | Time of Involvement |
|---|---|---|---|---|
| Settlor | Creates and funds the trust | Original owner who transfers ownership | None (unless also serving as trustee) | Primarily at creation, ongoing in revocable trusts |
| Trustee | Manages trust assets according to trust terms | Legal title holder with management responsibility | Yes, to all beneficiaries | Throughout trust’s existence |
| Beneficiary | Receives benefits from trust assets | Holds equitable title/beneficial interest | None | Throughout trust’s existence |
I often explain to my clients that the settlor of a trust is like the architect who designs the building. They create the blueprint (trust document), gather the materials (assets), then hand everything over to the contractor (trustee) who builds and maintains the structure for the eventual occupants (beneficiaries).
As Bridie O’Shannessy aptly notes, “The settlor has a limited but fundamental role in creating a trust.” While the settlor’s job might be front-loaded—establishing terms and transferring assets—their vision shapes everything that follows, especially with irrevocable trusts where they step away after creation.
The trustee, meanwhile, carries the ongoing responsibility of implementation. As one colorful legal expert described it, “The Trustee is the ‘worker bee’ of the trust.” Trustees must manage assets prudently, follow the trust’s terms precisely, treat all beneficiaries fairly, maintain meticulous records, communicate as required, and make distributions according to the trust’s provisions.
Beneficiaries occupy yet another distinct position. They’re entitled to receive benefits according to the trust terms, but typically have limited control over how the trust is managed. Their rights generally include receiving information about the trust, requesting accountings from the trustee, enforcing the terms if necessary, and receiving distributions as specified.
This separation of roles creates a system of checks and balances that helps ensure the settlor’s intentions are carried out while protecting everyone’s interests. It’s a bit like the branches of government—each with different powers and responsibilities that, when working properly, create a balanced system.
For a deeper dive into the distinction between trustees and trustors, check out our article on Trustee Versus Trustor.
Choosing the Right Trustee
For the settlor of a trust, selecting the right trustee might be the most important casting decision they’ll make. The trustee will be the one carrying out their wishes, possibly for decades after they’re gone.
When my clients face this decision, I encourage them to weigh several key considerations before making their choice. Think of this as finding the right person (or institution) to care for something precious to you.
The first big decision is usually whether to choose a professional trustee or a family member. According to a 2022 survey by the National Association of Estate Planners & Councils, 60% of estate planning professionals recommend appointing a professional trustee rather than a family member. This preference stems from the complexity of trust administration and the potential for family tensions.
Professional trustees—like banks, trust companies, or professional fiduciaries—bring expertise in investment management, deep knowledge of trust law and tax regulations, objectivity, continuity (they don’t die or become incapacitated), and professional liability insurance. But they come with higher costs and may lack the personal touch.
Family member trustees, on the other hand, offer personal knowledge of family dynamics, lower or no fees, greater flexibility, and an understanding of the settlor’s values. But they may lack expertise and objectivity, and family relationships can complicate their role.
Regardless of which direction you lean, good trustees should possess several essential qualities: trustworthiness (it’s right there in the name!), financial acumen, organizational skills, impartiality, availability, and the firmness to say “no” when necessary.
As one of my colleagues wisely advises, “Appoint a trustee who will preserve the assets and not commingle them with personal holdings.”
Many of our clients at Sudden Wealth Protection Law choose a middle path by appointing co-trustees (perhaps a financial institution paired with a family member) or different trustees for different types of assets. Some opt for an institutional trustee with a family member serving as a “trust protector” with limited oversight powers.
The right trustee arrangement should balance expertise, cost, and family dynamics to fulfill your objectives as settlor. This isn’t a one-size-fits-all decision—it should reflect your unique family situation and the nature of your assets.
Removing or Replacing a Trustee
Even the most carefully chosen trustee might not work out in the long run. That’s why a forward-thinking settlor of a trust will include provisions for removing or replacing trustees if circumstances change. These provisions become especially crucial for trusts that might continue for generations.
Life happens—trustees move away, relationships sour, or skills become outdated. Common grounds for trustee removal include breach of fiduciary duty, mismanagement of trust assets, conflicts of interest, incapacity, resignation, relocation to a distant jurisdiction, or breakdown in communication with beneficiaries.
When drafting trusts for my clients, I suggest several approaches to trustee removal that provide flexibility while maintaining the trust’s integrity:
In revocable trusts, the settlor typically reserves the right to remove and replace trustees at will during their lifetime. This provides maximum control while the settlor is alive and capable.
For long-term planning, appointing a “trust protector” with specific power to remove and replace trustees based on defined criteria can be invaluable. This creates ongoing oversight without court involvement.
Some trusts allow adult beneficiaries to remove a trustee through majority or unanimous consent. This empowers beneficiaries but requires careful drafting to prevent abuse.
The trust can also specify objective circumstances—like conviction of a crime, bankruptcy, or incapacity—that automatically trigger trustee removal, removing any ambiguity about when removal is appropriate.
As a last resort, beneficiaries can petition a court to remove a trustee for cause, even if the trust document doesn’t specifically address removal. However, this can be costly and contentious.
To ensure smooth transitions between trustees, I advise my clients to name at least one successor trustee in their trust document, consider institutional successor trustees for long-term trusts, include detailed provisions for determining trustee incapacity, specify the process for trustee resignation, address compensation for successor trustees, and require outgoing trustees to provide accounting and promptly transfer assets.
Here in Arizona, we help settlors design comprehensive trustee succession plans that provide flexibility while protecting the trust’s purpose and the beneficiaries’ interests. With proper planning, even if your first-choice trustee doesn’t work out, your trust can continue to function smoothly through transitions.
Tax Implications & Asset Protection for Settlors
When you create a trust as a settlor of a trust, you’re not just planning for the future—you’re making decisions that have real tax and asset protection consequences today. Let’s break down what you need to know in simple terms.
Think of trusts as coming in two basic tax flavors: grantor trusts and non-grantor trusts. The difference matters a lot for your tax return.
With grantor trusts, you’re still the “owner” in the IRS’s eyes. All the income, deductions, and credits flow directly to your personal tax return—even if the money actually went to your beneficiaries. Most revocable living trusts fall into this category. It’s like you’re still holding the assets, just in a different pocket.
Non-grantor trusts, on the other hand, file their own tax returns using Form 1041. They’re separate taxpayers. When the trust keeps income, it pays its own taxes. When it distributes income to beneficiaries, those beneficiaries generally pay the taxes instead.
As one tax expert puts it, “In a grantor trust, the grantor retains power over trust assets and reports all gains and losses on their tax return; in a non-grantor trust, the grantor gives up control, cannot serve as beneficiary or trustee, and the trust itself is responsible for taxes.”
When it comes to estate taxes, the rules get even more interesting:
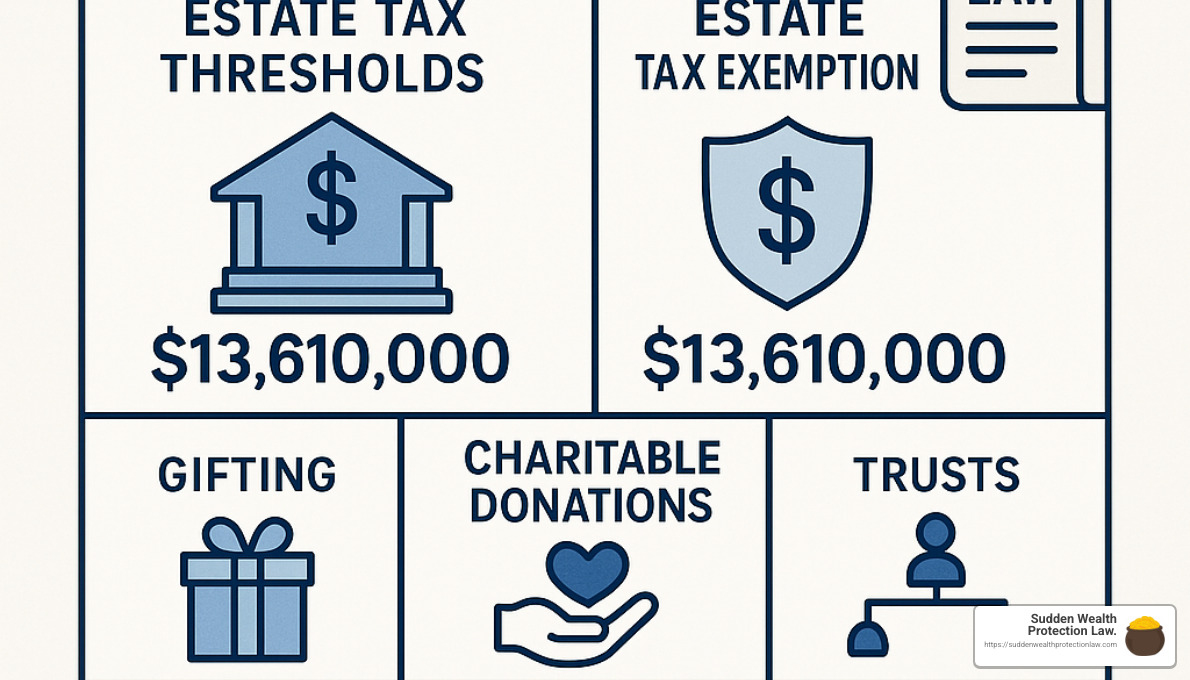
- Assets in your revocable trust are still part of your taxable estate (no surprise there, since you can take them back anytime).
- Assets in irrevocable trusts might escape estate taxes—but only if you don’t keep any prohibited powers or interests.
- When you transfer assets to an irrevocable trust, you might need to file a gift tax return, even if no tax is due.
A smart strategy I often recommend to clients worried about estate taxes is to “make gifts to beneficiaries or charities to reduce potential estate tax liability before death.” This approach can work wonderfully for the right family situation.
Now let’s talk about protecting your assets—which is probably why many of you are considering trusts in the first place.
The level of protection you get depends largely on your relationship to the trust after you create it:
Revocable trusts offer virtually no asset protection for you as the settlor. Since you can change or revoke the trust anytime, courts view these assets as still essentially yours—and therefore available to your creditors.
Irrevocable trusts where you’re not a beneficiary can provide strong asset protection. Once you’ve given assets away completely, your creditors generally can’t reach them.
Irrevocable trusts where you remain a beneficiary (sometimes called “self-settled trusts”) offer varying protection depending on state law. Some states accept these structures, while others reject them entirely.
Here in Arizona, I’ve developed the Asset Vault Trust, which incorporates a special power of appointment to give you maximum flexibility and asset protection. This irrevocable trust structure provides significant protection while maintaining some degree of indirect control—giving you the best of both worlds.
For a detailed comparison of revocable and irrevocable trusts, check out our analysis: Revocable Trust vs Irrevocable Trust.
It’s worth noting that asset protection has become one of the top three reasons people establish trusts, according to the American College of Trust and Estate Counsel. As the world becomes more litigious, this trend makes perfect sense.
When the Settlor of a Trust Is Also a Beneficiary
“Can I create a trust, protect my assets, and still benefit from them?” This is one of the most common questions I hear from clients. The answer isn’t simple, but it’s important to understand.
When you’re both the settlor of a trust and a beneficiary of your irrevocable trust (sometimes called a “settlor-interested trust”), special tax rules come into play:
For income taxes, these arrangements typically count as grantor trusts. This means all trust income gets reported on your personal tax return, regardless of who actually receives distributions.
For estate taxes, the assets might remain in your taxable estate despite the trust being irrevocable. This can defeat one of the primary purposes of creating the trust in the first place.
For gift taxes, depending on how the trust is structured, transfers to the trust might be considered “incomplete gifts” for tax purposes—which means no immediate gift tax, but also no removal from your estate.
The asset protection picture gets even more complex. Traditionally, common law followed a simple principle: you can’t create a trust for your own benefit and shield those assets from creditors. This is called the “self-settled trust doctrine.”
However, several states have changed this rule:
States with Domestic Asset Protection Trust (DAPT) laws allow you to create self-settled trusts with varying degrees of creditor protection. States like Nevada, Wyoming, and South Dakota lead the pack here.
In non-DAPT states like Arizona, the traditional rule generally applies—creditors can reach trust assets to the maximum extent the trustee could distribute them to you.
At Sudden Wealth Protection Law, I’ve developed hybrid approaches for clients who want to maintain some access to trust assets while achieving meaningful protection:
- Spousal Lifetime Access Trusts (SLATs), where you and your spouse create trusts for each other
- Trusts with carefully limited beneficial interests for you as the settlor
- Trusts with loan provisions rather than outright distribution rights
- Trusts with discretionary distribution standards that include you in a broader class of permissible beneficiaries

As one legal expert notes, “It can be useful in certain tax and asset protection circumstances for the settlor to assume trusteeship,” but this must be done carefully to avoid undermining the trust’s protective features.
The key is finding the right balance between maintaining access and achieving protection, all while navigating the relevant tax rules. This is definitely an area where working with an experienced trust attorney makes all the difference.
International & State Variations
Trust law isn’t uniform—not across the U.S., and certainly not around the world. As a settlor of a trust, these variations can significantly impact your planning options.
Within the United States, state trust laws differ in several important ways:
About 19 states, including Nevada, Wyoming, and South Dakota, have enacted laws allowing self-settled asset protection trusts. These DAPT (Domestic Asset Protection Trust) states let you be both settlor and beneficiary while still achieving some creditor protection—a powerful combination.
States also vary widely in how long they allow trusts to last. Some states have abolished or significantly extended the rule against perpetuities, allowing “dynasty trusts” to continue for multiple generations. Others still limit trust duration to a period tied to human lives.
Trustee powers and duties differ from state to state as well. Some states impose stricter fiduciary standards, while others give trustees more flexibility and discretion.
States also take different approaches to “virtual representation”—the rules for representing the interests of minor, unborn, or unascertainable beneficiaries in trust proceedings. This might seem like a technical detail, but it can become extremely important if trust disputes arise.
Here in Arizona, where I practice, our trust law has several distinctive features:
Arizona hasn’t adopted DAPT legislation, but we offer other effective asset protection strategies.
Arizona allows trusts to last up to 500 years—essentially abolishing the rule against perpetuities for practical purposes.
We’ve adopted the Uniform Trust Code with some Arizona-specific modifications that make our trust law both modern and flexible.
Arizona provides particularly strong protection for discretionary trusts, making them valuable tools in our planning arsenal.
Looking beyond U.S. borders, offshore trust jurisdictions offer different features that might appeal to certain settlors:
The Cook Islands, Nevis, and Belize are renowned for their strong asset protection laws and short statutes of limitation for creditor claims. These jurisdictions have built their financial services industries around trust protection.
The Cayman Islands and Bahamas offer financial privacy and sophisticated trust structures that appeal to high-net-worth individuals with international holdings.
The United Kingdom and Commonwealth Nations follow traditional trust law principles with varying modernizations, often providing a comfortable middle ground between U.S. and pure offshore options.
Even civil law countries, which historically didn’t recognize trusts, have adopted trust-like structures to compete in the global financial landscape.
Australian trust law offers a particularly interesting case study. In Australia, the role of the settlor is intentionally minimized:
The settlor typically makes only a nominal contribution to establish the trust.
The settlor is usually unrelated to the trustee and beneficiaries.
The trust deed often expressly prohibits the settlor from benefiting from the trust.
This structure helps avoid adverse tax consequences under Section 102 of the Income Tax Assessment Act 1936.
These international variations highlight why jurisdiction selection matters so much in trust planning. At Sudden Wealth Protection Law, I help clients understand how Arizona trust law applies to their situation and when more specialized domestic or international structures might better serve their needs.
Types of Trusts a Settlor Can Create
As a settlor of a trust, you have a wealth of options when it comes to creating a trust that meets your specific needs. Think of these different trust types as tools in a toolbox – each designed to solve particular planning challenges.
When I meet with clients at Sudden Wealth Protection Law, I often begin by asking about their goals. Are you primarily concerned with avoiding probate? Protecting assets from creditors? Minimizing taxes? Providing for a loved one with special needs? Your answers guide us toward the right trust structure.
The most common trust types include:
Revocable Living Trusts allow you to maintain complete control during your lifetime. You can change the terms, add or remove assets, or even cancel the trust entirely. While they don’t offer asset protection for you as the settlor, they do provide seamless management if you become incapacitated and help your loved ones avoid the time and expense of probate.
Irrevocable Trusts represent a more permanent arrangement. Once established, these trusts can’t be easily changed or revoked. This permanence creates separation between you and your assets, which can provide significant tax benefits and asset protection. Many specialized trusts, like charitable trusts and special needs trusts, are structured as irrevocable trusts.
Testamentary Trusts take effect only after your death, as they’re created through your will. While they don’t help you avoid probate, they can provide long-term management for beneficiaries who might not be ready to handle an inheritance directly.
Our signature Asset Vault Trust combines strong asset protection with flexibility through a special power of appointment. This innovative structure helps shield your assets while still allowing adjustments as family circumstances change.
Special Needs Trusts serve a crucial purpose for beneficiaries with disabilities. These trusts provide supplemental benefits without jeopardizing eligibility for government assistance programs like Medicaid or SSI.
Charitable Trusts allow you to support the causes you care about while potentially creating income for yourself or other beneficiaries. Options include Charitable Remainder Trusts and Charitable Lead Trusts, each offering different benefits and structures.
Dynasty Trusts look beyond your immediate family to benefit multiple generations. These long-term trusts can help protect family wealth from taxes, creditors, and poor financial decisions for decades or even centuries.
Qualified Personal Residence Trusts (QPRTs) offer a tax-efficient way to transfer your home to your beneficiaries while allowing you to continue living there for a specified period.
Trust use has grown significantly in recent years. The American College of Trust and Estate Counsel reports that over 20% of Americans aged 55 and older have established a living trust, with probate avoidance and asset protection cited as the top reasons. In fact, trust use in estate planning has increased by 25% over the past decade.
When choosing a trust structure, consider your full financial picture and family situation. At Sudden Wealth Protection Law, we take time to understand your unique circumstances before recommending specific trust strategies. The right trust can provide peace of mind today while creating a lasting legacy for tomorrow.
Spotlight on the Revocable Living Trust
The revocable living trust is the Swiss Army knife of estate planning tools. As a settlor of a trust, it gives you remarkable flexibility while still providing significant benefits for you and your loved ones.
When I explain revocable living trusts to clients, I often describe them as “you-centered” planning tools. That’s because they allow you to maintain complete control during your lifetime while setting up a seamless transition for the future.
With a revocable living trust, you typically wear three hats simultaneously: you create the trust as the settlor, manage the assets as the trustee, and benefit from the assets as the primary beneficiary. This arrangement gives you the same access and control you had before creating the trust.
The real magic of a revocable living trust appears when life throws curveballs. If you become incapacitated, your carefully chosen successor trustee steps in to manage your affairs without the need for a court-supervised guardianship. When you pass away, your assets transfer to your beneficiaries without going through the public, often lengthy probate process.
Privacy is another significant advantage. Unlike wills, which become public documents during probate, your trust terms remain private. This means your financial affairs and beneficiary information stay out of public view.
According to a 2023 LegalZoom survey, about 34% of people who create trusts name themselves as both settlor and trustee. This reflects how these trusts are designed to work during your lifetime – providing planning benefits without disrupting your normal financial activities.
It’s important to understand the limitations of revocable living trusts too. They don’t provide asset protection during your lifetime because you maintain control of the assets. For tax purposes, the trust assets are still considered part of your estate. If asset protection or tax planning is your primary goal, we might need to explore other trust options.
Perhaps the biggest pitfall with revocable living trusts is failing to fund them properly. As one client learned the hard way, “A trust is not merely a document—it must hold assets to function.” We’ve seen many situations where families thought everything was taken care of, only to find after a loved one’s death that key assets weren’t properly transferred to the trust.
At Sudden Wealth Protection Law, we don’t just help you create your trust document. We guide you through the funding process and provide periodic reviews to ensure your trust continues to work as intended as your life changes.
For more information about living trusts, check out our detailed article on Inter Vivos Trust.
Spotlight on the Irrevocable Asset Vault Trust
When clients ask me about serious asset protection, I often introduce them to our signature offering at Sudden Wealth Protection Law: the Irrevocable Asset Vault Trust. This sophisticated planning tool balances strong asset protection with the flexibility families need as circumstances change.
As a settlor of a trust using the Asset Vault approach, you’re creating a legal fortress around your assets while maintaining indirect influence through carefully designed trust provisions.
The Asset Vault Trust differs from standard irrevocable trusts in several important ways. At its core is the special power of appointment – a feature that allows a designated individual (not you as the settlor) to redirect trust assets among a defined class of beneficiaries. This creates a dynamic trust that can adapt to changing family circumstances without court involvement.
“The special power of appointment is what gives this trust its unique strength,” I often explain to clients. “It maintains the protective irrevocable structure while allowing adjustments as family needs evolve.”
The trust requires an independent trustee – someone other than you as the settlor – which reinforces the separation needed for asset protection. This trustee has discretion over distributions rather than being obligated to make specific payments, which further improves the protection from potential creditors.
Another key feature is the spendthrift protection, which prevents beneficiaries from assigning their interests to creditors. This means your hard-earned assets remain protected not just from your potential creditors, but also from those who might have claims against your beneficiaries.
The Asset Vault Trust offers significant protection from:
– Future creditors (after applicable fraudulent transfer periods)
– Divorcing spouses of beneficiaries
– Beneficiaries who might make poor financial decisions
– Professional creditors targeting wealthy individuals
I find this structure particularly valuable for business owners, medical professionals, and others with heightened liability concerns. One physician client told me, “I sleep better knowing there’s a barrier between my personal assets and potential malpractice claims.”
The Asset Vault Trust represents an advanced planning strategy that requires careful consideration and proper implementation. It’s not right for everyone, but for those with significant assets and legitimate liability concerns, it can provide remarkable peace of mind.
If you’re interested in comparing different trust options, our article on Revocable Trust vs Irrevocable Trust offers a detailed analysis of the key differences.
At Sudden Wealth Protection Law, we take time to understand your specific situation before recommending the Asset Vault Trust or any other planning strategy. Our goal is always to provide the right level of protection for your unique circumstances.
Frequently Asked Questions about Settlors
What happens to settlor control after funding the trust?
After a settlor of a trust funds a trust, the level of control they retain depends entirely on the type of trust they’ve created.
With revocable living trusts, you’re still very much in the driver’s seat. You can change beneficiaries whenever you want, swap out trustees if they’re not performing to your standards, or modify the trust terms as your life circumstances change. You can even withdraw assets or completely terminate the trust if you decide it no longer serves your needs. This control continues until you become incapacitated or pass away.
As Patricia Louise Nelson colorfully described it, with a revocable trust “The Settlor is the ‘king of the world’ in the context of a trust.” That’s a pretty accurate description of the power you maintain!
The story changes dramatically with irrevocable trusts. Once you establish this type of trust, you’ve essentially handed over the keys. You can’t easily change beneficiaries or trust terms, and you can’t withdraw assets for your personal use. The trustee now has legal control, though they must manage the trust according to the fiduciary duties you’ve outlined.
That said, even with irrevocable trusts, you might retain some limited powers—like the right to replace the trustee with another independent trustee, limited power to direct investments, or the ability to change administrative provisions.
Remember this important principle: the more control you keep as a settlor, the fewer asset protection and tax benefits your trust provides. As one expert notes, “To avoid the perception that the settlor’s declaration of trust is revocable, the settlor should be unrelated to the trustee and the beneficiaries of the trust.”
Can multiple people act as settlors of the same trust?
Yes, multiple people can absolutely serve as settlors of the same trust. This arrangement is quite common in several everyday scenarios.
Married couples frequently create joint trusts with both spouses serving as settlors. Both contribute assets to the trust and typically serve as co-trustees during their lifetimes. The trust can then continue for the benefit of the surviving spouse after the first spouse passes away.
Business partners might create a trust for succession planning purposes. Each partner contributes their ownership interest to the trust, which then provides for management and eventual distribution of the business when they retire or pass away.
Extended family members sometimes create a trust for a common purpose. For instance, siblings might establish a trust for their parents’ care, or several family members might contribute to a trust that funds education for younger generations.
When multiple settlors create a trust together, you’ll need to address several important considerations:
First, be clear about decision-making authority. Your trust document should specify how decisions are made during the settlors’ lifetimes—unanimously, by majority vote, or some other arrangement.
Second, address separate property concerns. Will contributed assets remain separate or become jointly owned within the trust? This distinction can have significant implications later.
Third, spell out amendment provisions. Can one settlor amend the entire trust, or only their portion? Do all settlors need to consent to changes?
Fourth, clarify revocation rights. Can one settlor revoke the entire trust or only withdraw their contributed assets?
Finally, understand the tax implications, which can become quite complex with multiple settlors.
At Sudden Wealth Protection Law, we help multiple settlors steer these issues to create trusts that serve their shared goals while respecting their individual rights and interests.
What risks should a settlor watch out for?
When creating and funding a trust, a settlor of a trust should keep their eyes open for several potential pitfalls that could undermine their careful planning.
Incomplete funding is perhaps the most common mistake we see. Assets that aren’t properly transferred to your trust won’t avoid probate—which might be one of your main reasons for creating the trust in the first place. Many people sign their trust documents with great ceremony, then forget the crucial step of retitling their assets. Regular review of asset ownership is essential to maintain your trust’s benefits.
Improper tax planning can lead to unwelcome surprises. Unintended tax consequences may arise from poor trust design. For example, grantor trust status might result in unexpected income tax liability, or gift tax issues could emerge when funding irrevocable trusts. If you’re planning across multiple generations, generation-skipping transfer tax complications can arise as well.
Trustee selection deserves careful thought. Choosing an unqualified or unreliable trustee can completely undermine your trust’s purpose. Family trustees might face conflicts of interest or lack necessary expertise, while professional trustees may be expensive or impersonal. Failing to name successor trustees can lead to court involvement—exactly what many people create trusts to avoid.

Inflexible trust provisions can become problematic as circumstances change. Overly rigid distribution requirements might not adapt to beneficiaries’ evolving needs. Without trust protector provisions or modification mechanisms, your trust may become outdated as laws or family situations change.
Creditor protection weaknesses might leave assets vulnerable. Revocable trusts provide no protection from your own creditors. Fraudulent transfer laws may invalidate transfers to irrevocable trusts if you’re already facing creditor claims. Self-settled trusts may not provide the protection you expect in some jurisdictions. And failing to maintain trust formalities can compromise asset protection even in well-designed trusts.
Beneficiary disputes can tear families apart. Unclear or inequitable distribution provisions often lead to conflict. Many settlors fail to communicate their intentions to family members, leading to misunderstandings and hurt feelings later. Disinherited heirs may challenge the trust’s validity, especially if they feel blindsided.
A 2022 survey by the National Association of Estate Planners & Councils found that trust disputes have increased by 25% over the past decade, with unclear settlor intentions cited as the primary cause of conflicts.
At Sudden Wealth Protection Law, we help settlors steer these potential pitfalls through careful planning, clear documentation, and ongoing trust review and maintenance. Our goal is to give you peace of mind that your trust will work exactly as you intend, both now and in the future.
Conclusion
The settlor of a trust plays the fundamental role in every trust arrangement, setting in motion a powerful legal structure that can protect assets, avoid probate, minimize taxes, and provide for loved ones across generations.
As we’ve explored throughout this guide, the settlor’s decisions shape everything about a trust’s effectiveness. From choosing the right type of trust to selecting trustees and defining how beneficiaries will receive their inheritance, these choices create the foundation for your legacy.
Trust-based planning has grown tremendously in recent years—increasing by 25% over the past decade. This isn’t surprising when you consider the peace of mind that comes from knowing your wishes will be honored and your loved ones protected. People consistently tell us they create trusts to avoid the public probate process and to shield their hard-earned assets from unexpected threats.
At Sudden Wealth Protection Law, we understand that creating a trust is more than just signing legal documents. It’s an expression of your deepest values and your hopes for the future. When you work with us, we take the time to listen to your unique story and concerns. We then craft trust solutions that reflect your specific circumstances and goals.
But remember—signing your trust document is just the beginning of your journey. The most effective trust plans include proper funding (transferring assets into the trust), periodic reviews as laws change, and occasional updates as your family circumstances evolve. Many people create beautiful trust documents but forget this critical follow-through step. We partner with our clients to ensure nothing falls through the cracks.
Whether you’re just beginning to explore trust options or reviewing arrangements you made years ago, understanding the settlor’s role gives you the foundation for making informed decisions. Your choices today can provide protection, support, and opportunity for generations to come.

I’ve helped hundreds of Arizona families create meaningful legacy plans that truly reflect their values. If you’re ready to explore how a carefully crafted trust can protect what matters most to you, I invite you to learn more about our Wills & Trusts services.
The role of settlor of a trust may be where your trust journey begins, but with thoughtful planning, the benefits will extend far beyond your lifetime—creating security and opportunity for those you love most.

