

Trust Basics: Who Controls What?
If you’re trying to understand the difference between a trust beneficiary vs trustee, here’s the quick answer:
| Trust Beneficiary | Trustee |
|---|---|
| Receives benefit from trust assets | Manages and controls trust assets |
| Has “equitable ownership” | Has legal title and authority |
| Can request information and accountings | Must keep records and provide reports |
| Can receive distributions per trust terms | Makes distribution decisions following trust terms |
| May challenge trustee actions in court | Has fiduciary duty to act in beneficiaries’ best interests |
A trust is like a relay race where the baton (your assets) gets passed from one runner to another. But understanding who does what can be confusing. The trust beneficiary vs trustee relationship is at the heart of how trusts work, yet many people struggle to grasp the fundamental differences between these roles.
Think of a trust as a three-party relationship: the grantor (who creates and funds the trust), the trustee (who manages it), and the beneficiary (who benefits from it). While the grantor sets the rules, it’s the trustee-beneficiary dynamic that determines how smoothly things will run after the grantor steps aside.
The difference matters because when these roles get confused, family conflicts erupt, assets get mismanaged, and courts get involved. I’ve seen modest estates decimated by litigation costs when trustees and beneficiaries misunderstand their positions.
I’m Paul E. Deloughery, founder of Sudden Wealth Protection Law, and I’ve spent over 25 years helping families steer the complex trust beneficiary vs trustee relationship, drawing from both my legal expertise and personal experience of inheriting and losing $14 million due to poor planning.
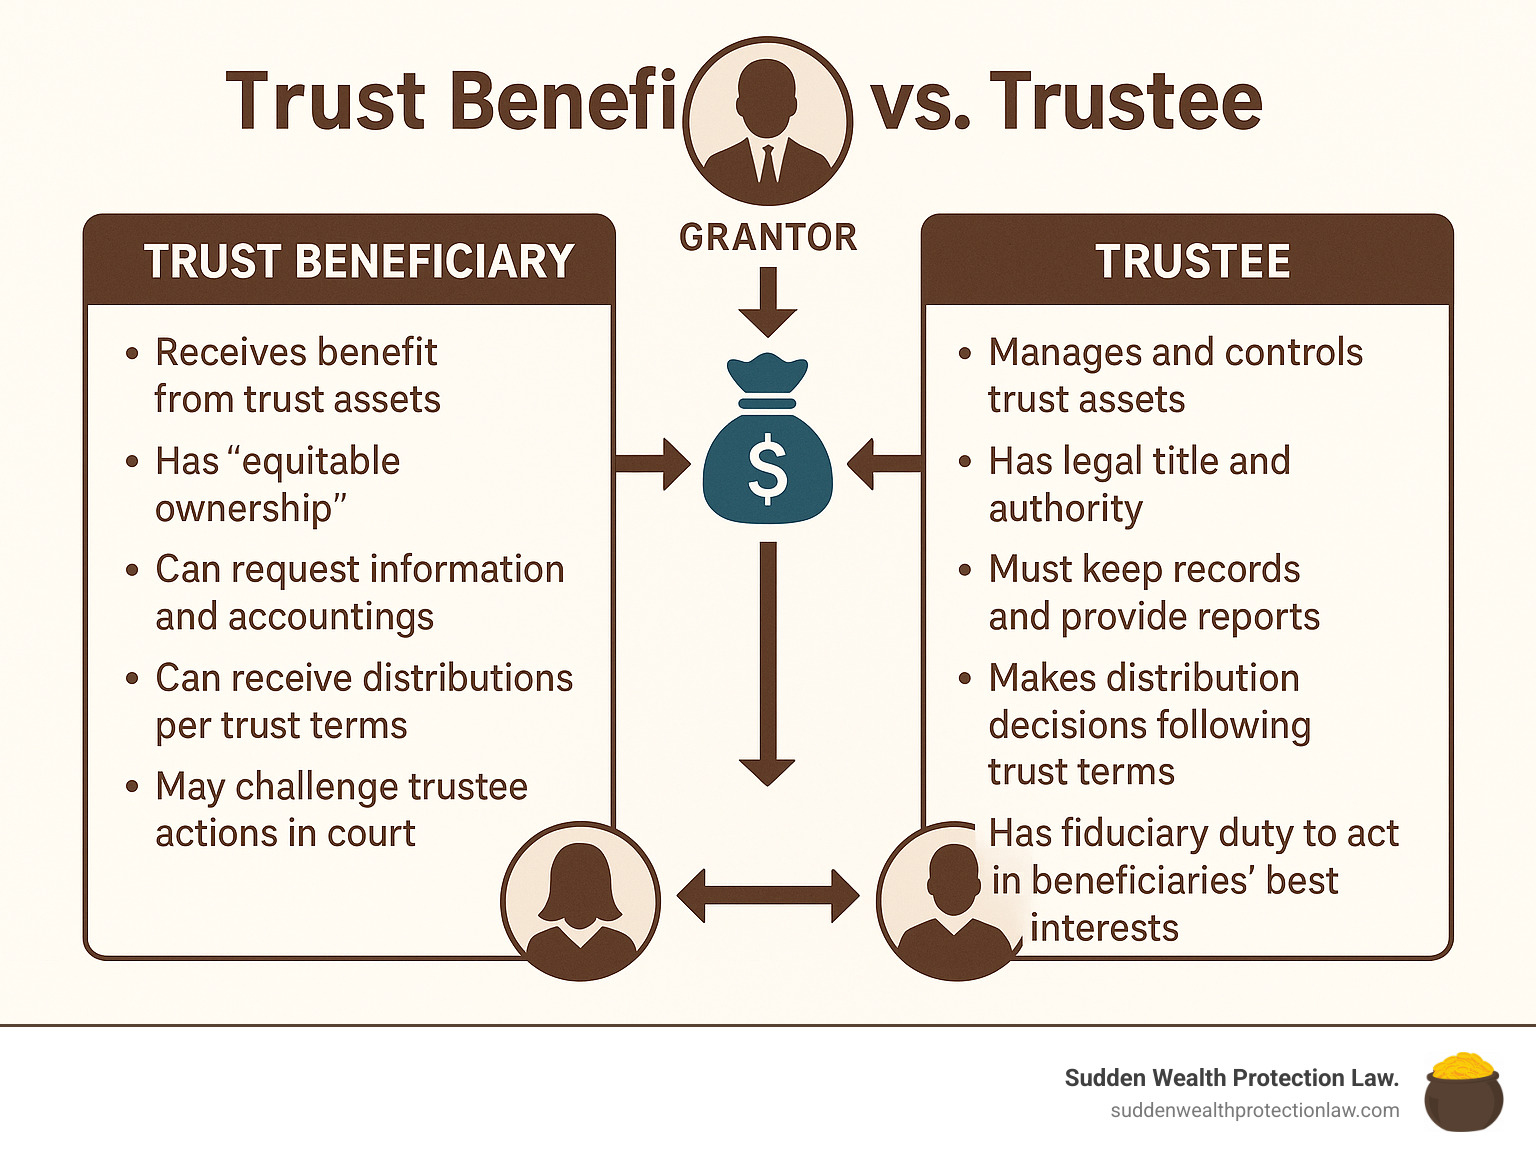
Trust beneficiary vs trustee terminology:
Introduction

I’ve seen it too many times—a family gathered around a kitchen table, staring at trust documents with confusion and growing frustration. Mom has passed away, and now Dad, who’s been named trustee, is trying to explain to his adult children why he can’t just “hand over their inheritance” as they expected. The tension builds, voices rise, and someone inevitably says, “That’s not what Mom would have wanted!”
This scene plays out in homes across Arizona every day. Why? Because most people don’t understand the fundamental differences between a trust beneficiary vs trustee until they’re thrust into one of these roles—often during a time of grief when emotions already run high.
It’s like being handed the keys to a complex machine with no instruction manual. And the stakes couldn’t be higher: family relationships, financial security, and the legacy your loved one worked a lifetime to build.
Why This Matters
The confusion between trustee and beneficiary roles isn’t just an academic problem—it has real-world consequences that can devastate families:
- According to the American College of Trust and Estate Counsel, disputes between trustees and beneficiaries account for approximately 40% of all trust-related court cases.
- Family wealth can be decimated by legal fees—I’ve seen modest $500,000 estates reduced to almost nothing after years of litigation.
- Family relationships often never recover from the bitterness of trust disputes.
As I often tell clients over a glass of whiskey after a long day in court, “The law doesn’t care about your family Thanksgiving dinner—but you should.” Understanding these roles isn’t just about legal compliance; it’s about preserving the relationships that matter most.
Trust Beneficiary vs Trustee: The Two Pillars of Any Trust
Think of a trust as a three-person dance. The grantor leads initially by setting the steps, but then steps off the floor. After that, it’s just the trustee and the beneficiary circling each other—sometimes in harmony, sometimes stepping on each other’s toes.
The trustee holds legal ownership of everything in the trust. They’re the ones with their name on the deeds, the bank accounts, and the investment portfolios. They make the decisions, sign the checks, and file the tax returns. Under the law, they have what’s called a “fiduciary duty”—the highest legal standard there is—to act solely for the benefit of the beneficiaries, not themselves.
The beneficiary, on the other hand, has what lawyers call “equitable ownership.” They don’t control the assets, but they have the right to benefit from them according to the trust’s terms. It’s like having a meal ticket to a restaurant you don’t manage—you can eat, but you can’t decide the menu or fire the chef.
This distinction matters tremendously. I once had a client storm into my office demanding to know why his sister (the trustee) wouldn’t “give him his money” from their parents’ trust. When I explained she wasn’t being difficult—she was following the terms their parents set—he sat back stunned. “You mean it’s not really mine yet?” Exactly.
| Aspect | Trustee | Beneficiary |
|---|---|---|
| Ownership Type | Legal title | Equitable interest |
| Control Over Assets | Yes | No (with rare exceptions) |
| Can Make Investment Decisions | Yes | No |
| Can Request Distributions | No (unless also a beneficiary) | Yes |
| Legal Obligations | Fiduciary duties | None to the trust |
Who Holds the Power Day-to-Day?
In the trust beneficiary vs trustee relationship, the trustee clearly holds the day-to-day power. They’re the ones with their hands on the wheel—making investment decisions, approving (or denying) distribution requests, and managing the trust property.
This power imbalance often creates tension. I’ve sat with beneficiaries who were literally in tears because they needed money for a medical procedure or college tuition, but the trustee was taking their sweet time reviewing the request. From the beneficiary’s perspective, it feels like asking permission to use what’s “already theirs.”
Can One Person Wear Both Hats?
Yes, and it happens all the time. In fact, about 60% of family trusts have someone serving as both trustee and beneficiary. The classic example is the surviving spouse who serves as trustee of a trust created by their deceased husband or wife, while also being the primary beneficiary.
This dual role creates an obvious conflict of interest. How do you fairly decide whether to distribute money to yourself versus preserving it for the kids who’ll inherit after you’re gone? It’s like being asked to fairly divide the last piece of chocolate cake between yourself and someone else.
Arizona law doesn’t prohibit this arrangement, but our courts will look much more closely at the actions of someone wearing both hats compared to an independent trustee. When disputes arise—and they often do—the trustee-beneficiary faces tougher scrutiny.
As I once told a client over whiskey after signing his documents: “Naming your oldest daughter as both trustee and beneficiary is like making her both referee and player in the same game. Don’t be surprised when her siblings cry foul.”
Rights and Responsibilities: What the Beneficiary Can Demand, What the Trustee Must Deliver
When it comes to the trust beneficiary vs trustee relationship, think of it as a dance where each partner has specific moves they must perform. Get a step wrong, and toes get stepped on—sometimes painfully.
In Arizona, trustees don’t get to make up their own rules. Arizona Revised Statutes §14-10813 lays out clear obligations: trustees must keep beneficiaries reasonably informed about how the trust is being managed and provide relevant information when asked. It’s not optional—it’s the law.
What does this look like in the real world? A trustee must provide regular accountings that show where every penny went—income, expenses, assets, and liabilities. Typically, this happens annually, though your trust document might specify different timing.
Trustees must also make distributions according to the trust’s terms—not playing Scrooge by withholding funds beneficiaries are entitled to, nor playing Santa by giving away so much that the trust becomes depleted.
The trustee’s duty of loyalty means they must put the beneficiaries’ interests above their own. I once had a case where a trustee invested trust assets in his brother-in-law’s startup company. When the company tanked, so did the trust assets—and the court held him personally liable for the loss.
Key Beneficiary Rights Checklist
If you’re a beneficiary wondering what you’re entitled to know and receive, here’s your Arizona rights checklist:
- A copy of the trust document (at minimum, the parts relevant to your interest)
- Annual reports detailing trust assets, liabilities, receipts, and disbursements
- Prompt notification (within 60 days) when a revocable trust becomes irrevocable due to the grantor’s death
- Similar notification when there’s a trustee change
- The right to petition the court if things go sideways
You also have the right to ask a court to remove a trustee who’s not fulfilling their duties. But that’s like dropping a nuclear bomb on family relationships—it should be your last resort, not your opening move.
Understanding whether you’re an income beneficiary vs principal beneficiary is crucial. It determines whether you’re entitled to the fruit (income) or the tree itself (principal). Many family feuds start because beneficiaries don’t understand this distinction.
Trustee Duties in Plain English
If you’ve been named trustee, congratulations—you now have a part-time job you didn’t apply for. Here’s what you’ve signed up for:
First, you need to be a prudent investor. This doesn’t mean you need to beat the S&P 500 every year, but it does mean you can’t just stick everything in your cousin’s bitcoin scheme or let it sit in a checking account earning nothing.
You must treat beneficiaries with impartiality. This gets especially tricky when you’re balancing the needs of current beneficiaries (often wanting income now) against remainder beneficiaries (wanting principal preserved for later). According to the American Bar Association’s guide on fiduciary duties, this balancing act is one of the most challenging aspects of trust administration.
Tax filings are non-negotiable. Trust tax returns must be filed on time, every time. The IRS doesn’t accept “I was busy” as an excuse.
Meticulous record keeping is your new hobby. Every transaction needs documentation. As I tell trustees, “If you didn’t document it, in the eyes of the court, it didn’t happen.”
Finally, communication with beneficiaries isn’t just good practice—it’s required. Many trustees get in trouble not because they did anything wrong with the money, but because they failed to keep beneficiaries informed.
Fiduciary Duties: How Arizona Law Keeps Trustees Honest
Now, let’s talk about fiduciary duties – the legal equivalent of handcuffs on a trustee. In Arizona, the law doesn’t just suggest trustees behave themselves; it demands it with the force of a parent catching a teenager sneaking in past curfew.
Under Arizona Revised Statutes §14-10801, trustees must administer the trust in good faith, following its terms and purposes while protecting beneficiaries’ interests. This isn’t optional – it’s the highest standard of conduct known in law. Why? Because the trust beneficiary vs trustee relationship has an inherent power imbalance that would make most boxing matches look fair.
The prudent investor rule (ARS §14-10901) requires trustees to manage trust assets as carefully as they would their own retirement fund – maybe even more carefully. This means diversifying investments (unless there’s a compelling reason not to), keeping costs reasonable, and making decisions that balance the needs of current and future beneficiaries.
I’ve seen trustees who treated trust funds like their personal Vegas bankroll. One memorable case involved a trustee who “invested” in his brother-in-law’s alpaca farm startup. Spoiler alert: alpacas aren’t great retirement vehicles. The court ordered him to personally replace $230,000 in losses, plus interest. That’s what we call a “surcharge” in legal speak – and it’s the hammer that keeps trustees honest.
The Court’s Hammer vs the Trustee’s Head
When the trust beneficiary vs trustee relationship deteriorates, the courtroom becomes the boxing ring – and trustees often leave with a financial concussion.
The consequences for breaching fiduciary duties aren’t theoretical – they’re painfully real:
Personal liability means trustees might be writing checks from their personal accounts to cover trust losses. I’ve seen trustees forced to take out second mortgages to make trusts whole after their investment blunders.
Removal is the court’s way of saying “you’re fired” – often with a side of public embarrassment that follows you in professional circles.
Disgorgement of fees means returning every dollar you were paid as trustee. That $50,000 in trustee fees? Hand it back, please.
Court costs and attorney fees can easily run into six figures in contested trust litigation. And yes, the trustee might be paying both sides’ legal bills.
Best Practices to Stay Out of Trouble
The best way to avoid becoming a cautionary tale at legal seminars is to follow some basic practices that keep you firmly on the right side of your fiduciary duties.
Document everything like you’re expecting an audit tomorrow. Keep detailed minutes of major decisions, including why you made them and how they benefit the beneficiaries. I tell trustees to imagine explaining their decisions to a skeptical judge who’s had a bad day.
Seek professional advice when you’re in unfamiliar territory. The modest cost of consulting with financial advisors, attorneys, or accountants is typically a legitimate trust expense – and much cheaper than litigation.
Communicate proactively with beneficiaries. Most trust litigation starts because beneficiaries feel kept in the dark. Regular updates and transparent explanations of your decisions can prevent misunderstandings from festering into lawsuits.
Common Flashpoints & How to Defuse Them Before Court Becomes the Only Option
After spending a quarter-century in the trenches of trust law, I’ve watched the same battles erupt time and again between trustees and beneficiaries. These conflicts aren’t just legal problems—they’re family earthquakes that can leave permanent fault lines in relationships that once seemed unshakable.
In my experience, five issues consistently light the fuse of family trust explosions:
Ambiguous Trust Terms create a perfect storm of disagreement. When a trust document uses fuzzy language like “reasonable support” or “education expenses,” everyone develops their own interpretation. Is a $50,000 car “reasonable” for a college student? Does “education” cover a third master’s degree in medieval poetry? Without clarity, these questions become battlegrounds.
Investment Strategy Disputes arise from competing interests. Current beneficiaries—often the surviving spouse or older generation—typically want income-producing investments that pay out now. Meanwhile, remainder beneficiaries—usually the kids or grandkids—prefer growth investments that will maximize what they’ll eventually receive. The trustee gets caught in this generational tug-of-war.
Property Occupation Issues are particularly thorny. When Mom’s trust owns the family home and one sibling is living there rent-free while others receive nothing, resentment bubbles up faster than you can say “unfair advantage.”
Compensation Disputes often blindside family trustees. “You’re charging us for managing Mom’s money?” is a question I’ve heard countless times, usually asked in an accusatory tone that suggests the trustee is somehow stealing.
Information Asymmetry might be the most preventable flashpoint. When trustees clam up or provide minimal information, beneficiaries naturally assume the worst. This information vacuum gets filled with suspicion, rumor, and eventually, legal action.
The best fire extinguisher for these potential blazes is clear, consistent communication. I recommend establishing a formal protocol that includes quarterly written updates, annual face-to-face meetings with all beneficiaries, a transparent process for requesting distributions or information, and decision-making that explicitly references trust provisions.
Drafting Tips to Prevent War
If you’re in the process of creating a trust, you have a golden opportunity to prevent future family warfare. Here are battle-tested strategies to keep peace in your family long after you’re gone:
Define Every Term with excruciating clarity. Don’t just say “support”—spell out whether that includes luxury cars, vacations, or private school tuition. Don’t just say “education”—clarify whether that means undergraduate only or includes PhDs, trade schools, or cooking classes in Paris.
Include a Detailed Removal Clause that gives beneficiaries a safety valve short of court action. Specify exactly when and how a trustee can be removed—perhaps requiring evidence of mismanagement or a super-majority vote of beneficiaries. This prevents the nuclear option of litigation from becoming the first resort.
Establish a Majority Vote Rule for trusts with multiple beneficiaries. Consider requiring 51% or even 75% agreement for challenging trustee decisions or requesting unusual distributions. This prevents a single disgruntled beneficiary from derailing the entire trust.
When a Beneficiary Is Living in the Trust Home
The family home often becomes ground zero for trust beneficiary vs trustee conflicts. When a trust owns a house and a beneficiary is living in it, several thorny questions inevitably arise:
Should the beneficiary pay rent? In most cases, absolutely—at fair market value. Otherwise, that beneficiary is essentially receiving a larger slice of the trust pie than their siblings. I’ve seen this single issue tear families apart when one sibling has lived rent-free for years while others received nothing.
Who handles maintenance and improvements? This needs crystal-clear documentation. Typically, day-to-day maintenance falls to the occupant (just as with any tenant), while structural improvements that increase property value should be the trust’s responsibility. Without this clarity, expect heated arguments over every leaky faucet and carpet stain.
Frequently Asked Questions about Trust Beneficiary vs Trustee
What if the trustee refuses to give me the trust documents?
As a beneficiary, you have the legal right to see at least the portions of the trust that affect your interests. When a trustee plays hide-and-seek with these documents, there’s a clear path forward:
First, send a formal written demand letter that specifically cites Arizona Revised Statutes §14-10813. This statute requires trustees to keep beneficiaries “reasonably informed” about trust administration. I’ve seen trustees suddenly develop remarkable cooperation skills when they receive a properly cited legal demand.
Give them 30 days to respond—this is a reasonable timeframe that also shows you mean business. If they continue the silent treatment, it’s time to petition the probate court to order document production.
Though, you’re only entitled to see the parts of the trust that directly impact your interest. If your cousin Edith has special provisions that don’t affect your share, the trustee can (and probably should) redact those sections.
How is a trustee paid and who sets the fee?
Trustee fees are governed first by the trust document itself, and then by Arizona law.
If your grandmother’s trust specifically says “Aunt Martha gets $10,000 annually as trustee,” that’s what controls. If the trust is silent on compensation (as many are), Arizona Revised Statutes §14-10708 steps in, entitling trustees to “reasonable compensation.”
But what’s “reasonable” can feel like a moving target. Courts look at several factors:
The trust’s size and complexity (managing a $20 million diverse portfolio deserves more compensation than overseeing a single checking account), the trustee’s expertise and time commitment (a corporate trustee with specialized knowledge typically commands higher fees than Uncle Bob), and local standards (what’s typical in Phoenix might differ from Tucson).
For a ballpark figure, professional trustees typically charge 1-2% of trust assets annually. Individual trustees often charge less, especially if they’re wearing the dual hat of beneficiary and trustee.
Can beneficiaries change the terms of the trust?
The short answer? Generally no. The slightly longer answer? It’s complicated.
In the trust beneficiary vs trustee relationship, neither side typically has the power to rewrite the trust’s terms. The trust document represents the grantor’s wishes—not a suggestion box for beneficiaries to modify as they please.
However, there are limited exceptions that might open the door to changes:
With unanimous consent of all beneficiaries (both current and remainder), you may petition the court under ARS §14-10411 to modify or even terminate a trust. But there’s a significant hurdle: the court must determine that your proposed changes don’t contradict a material purpose of the trust. If Grandpa created the trust specifically to protect spendthrift beneficiaries, your plan to distribute everything immediately will likely fail.
When circumstances change dramatically in ways the grantor couldn’t have anticipated, courts may consider modifications under ARS §14-10412. I’ve seen this successfully used when a beneficiary develops special needs that weren’t contemplated when the trust was created.
Conclusion
Let’s be honest—understanding the trust beneficiary vs trustee relationship isn’t just legal mumbo-jumbo. It’s about keeping your family speaking to each other at Thanksgiving dinner while ensuring your loved one’s wishes don’t get lost in a storm of confusion and conflict.
I’ve seen what happens when these roles blur: family heirlooms sold to pay attorney fees, siblings who won’t speak to each other for decades, and legacies that evaporate faster than morning dew in the Arizona desert. Trust disputes can turn even the most loving families into strangers.
At Sudden Wealth Protection Law, we’ve guided countless Arizona families through these treacherous waters. We don’t just offer cookie-cutter solutions—we provide personalized legal strategies that protect what matters most: your family’s assets and relationships.
Whether you’re the person creating a trust (wondering who on earth to name as trustee), the trustee (feeling the weight of fiduciary responsibility), or a beneficiary (concerned about how the trust is being managed), we’ve got your back.
My approach draws from both legal expertise and personal experience—remember, I’ve been on both sides of the inheritance equation. I know that behind every trust document are real people with real emotions and relationships worth preserving.
The ideal time to address potential trust beneficiary vs trustee conflicts is before the first hint of trouble appears. With thoughtful planning, transparent communication, and professional guidance, your trust can fulfill its intended purpose—providing for your loved ones and preserving your legacy without the drama.
For those already experiencing friction, our trust & estate contests, disputes, and litigation services can help defuse tensions before they explode into full-blown court battles.
Ready to gain clarity and peace of mind? Contact our Phoenix office to schedule a consultation. Let’s sit down and chart a course through these complex waters—together.

