

Why Misunderstanding One Word Can Cost Your Family Everything
The trustor definition is simpler than most people think, but getting it wrong can destroy a family’s financial future. A trustor is the person who creates a trust and transfers their assets into it – they’re the architect of the entire estate plan.
Quick Answer for “Trustor Definition”:
- Trustor = The person who creates and funds a trust
- Also called: Settlor, grantor (same meaning, different terms)
- Key role: Sets all the rules for how assets are managed and distributed
- Power level: Depends on trust type (keeps control in revocable trusts, gives up control in irrevocable trusts)
Here’s the brutal truth from 25 years in the trenches: I’ve watched families tear themselves apart because someone didn’t understand the difference between a trustor and a trustee. The trustor writes the playbook. The trustee follows it. When that distinction gets blurred, or when the trustor writes terrible rules, the whole thing collapses into expensive litigation.
The stakes are real. In 2023, trusts hit the highest federal tax bracket at just $14,450 of income – compared to $578,125 for individuals. One poorly structured trust can cost your family hundreds of thousands in unnecessary taxes. Worse, unclear instructions from the trustor often lead to beneficiary disputes that drain the trust through legal fees.
As someone who inherited $14 million and lost most of it, I’ve learned that understanding the trustor definition isn’t academic – it’s survival. My experience with sudden wealth loss drives my passion for helping Arizona families avoid the same financial devastation through proper estate planning.
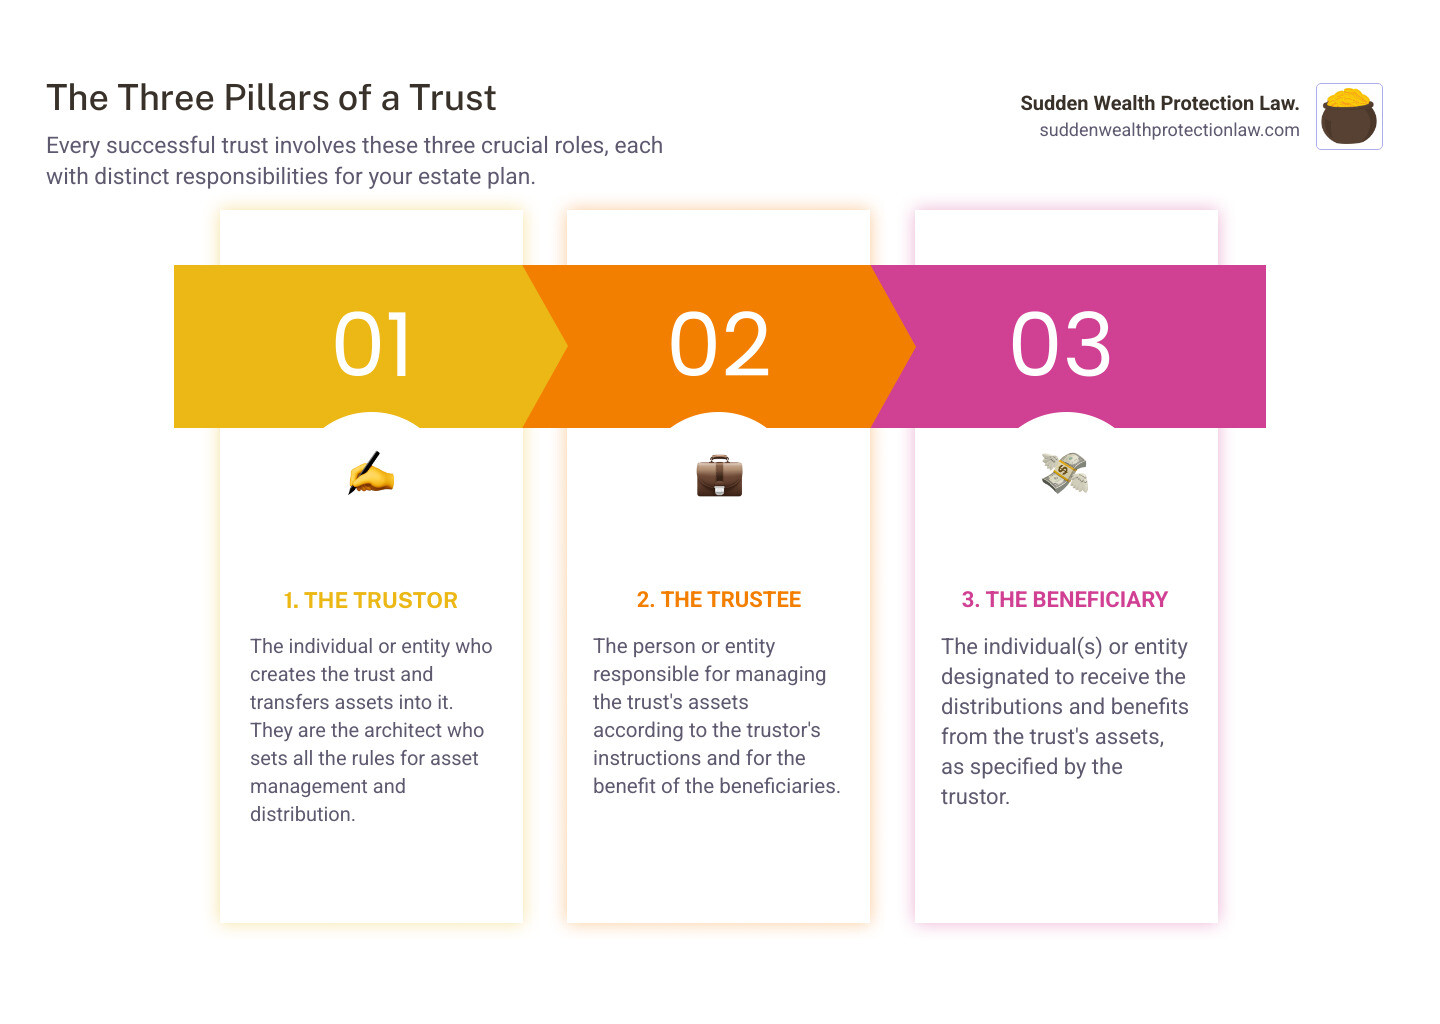
Easy trustor definition glossary:
The Core of the Matter: A Clear Trustor Definition
This is where it all begins. The trustor is the architect of the estate plan. They are the individual or entity who creates a trust, transfers assets into it, and sets the rules. It’s their vision and their legacy on the line. Without a trustor, there is no trust—period.
What’s in a Name? Trustor vs. Settlor vs. Grantor
You’ll hear a few different terms for the person who creates a trust. Let’s clear the air.
- Trustor: Widely used, especially in western states like Arizona. It’s direct and simple.
- Settlor: Often used interchangeably with trustor, referring to the person who “settles” assets into the trust.
- Grantor: Another common synonym, emphasizing that the person “grants” assets to the trust.
In practice, there is no functional difference. They all refer to the person who establishes the trust. The term you see might depend on regional preference or an attorney’s habit. Here in Arizona, we often use “trustor.”
Here’s a list of common synonyms for Trustor:
- Settlor
- Grantor
- Creator of the trust
- Donor
- Trustmaker
The Trustor’s Primary Responsibility: Writing the Rulebook
The trustor’s primary responsibility is creating the trust agreement—the legally binding rulebook for the trust. This document dictates the future of your assets and the financial well-being of your loved ones.
This rulebook includes:
- Asset Management Rules: How should assets be invested? What risks are acceptable? Are there specific assets that should never be sold?
- Beneficiary Designations: Who gets what? When do they get it? Should there be conditions, like reaching a certain age or graduating college, before they receive their inheritance?
- Distribution Instructions: Should distributions be outright or held in trust for the beneficiary’s lifetime? Should they be for specific purposes, like education or health, or for general support?
- Fiduciary Duty: While the trustor doesn’t have a fiduciary duty to the trust like a trustee does, they owe a duty to their family to create a clear, unambiguous plan. A poorly drafted trust agreement is a ticking time bomb that can explode into costly legal battles.
The trustor’s instructions are critical. Without clear guidelines, the trustee is left to guess, which can lead to disputes and a drain on the trust’s assets.
The Trustor’s Blueprint: Key Duties in Establishing a Trust
The trustor definition becomes crystal clear when you see the actual work involved. It’s a series of critical decisions that dictate how your assets are managed for decades. I’ve watched too many families find their trust was a house of cards because the trustor missed crucial steps. It’s like investing in a Ferrari but forgetting to put the engine in.
[TABLE] comparing the roles of a Trustor and a Trustee
| Role | Trustor (The Architect) | Trustee (The Manager) |
|---|---|---|
| Primary Function | Creates the trust and sets the rules. | Manages the trust according to the rules. |
| Key Action | Transfers assets into the trust. | Administers assets for beneficiaries. |
| Source of Power | The decision to create the trust. | The trust document created by the trustor. |
| Fiduciary Duty | Owes a duty to themselves to create a clear plan. | Owes a legal duty to the beneficiaries. |
The Critical Step of Funding the Trust
Here’s where the rubber meets the road. You can draft the most meticulous trust document in Arizona, but if you don’t fund it properly, it’s useless. An unfunded trust accomplishes nothing—your assets will still go through probate, defeating the entire purpose.
Funding a trust means transferring ownership of your assets from your individual name to the trust’s name. For real estate deeds, you must execute and record new deeds. Bank and investment accounts require retitling. This means contacting each financial institution to change ownership from “John Smith” to “The John Smith Family Trust.” It’s tedious, but skipping this step is like buying insurance and never paying the premiums.
The timing of funding matters for tax purposes. In 2024, the annual gift tax exclusion is $18,000 per recipient. When transferring substantial assets to an irrevocable trust where you give up control, you might bump up against gift tax considerations that count against your lifetime exemption.
I see unfunded trust problems constantly. Families come to me thinking they’re all set, only to find their trust is an empty folder. Don’t let that be your legacy.
Trust Administration for Dummies
Choosing the Players and Defining Their Roles
Creating a trust is like assembling a team, and the trustor is the general manager. Choose wisely, because these people will carry out your wishes long after you’re gone.
Appointing a trustee is your most critical decision. This person or institution manages your financial legacy. They handle investments, pay bills, make distributions, and deal with beneficiaries. I’ve seen trusts turn into nightmares because the trustor chose someone who was overwhelmed, dishonest, or simply in over their head.
Your trustee needs three key qualities: integrity, competence, and impartiality.
Naming beneficiaries is where your vision comes to life. You’re defining who gets what, when, and under what conditions. Some trustors set age requirements, educational milestones, or other benchmarks.
Don’t forget the successor trustee. Your first choice might become incapacitated or unwilling to serve. Having qualified successors named in advance prevents your trust from getting stuck in legal limbo.
The trustee you choose assumes a fiduciary duty—a legal obligation to act in the beneficiaries’ best interests, not their own. This isn’t just a moral responsibility; it’s enforceable by law. Choose someone who understands that weight.
What Does a Trustee Do?
Trustor vs Trustee
The Trustor’s Control: How Trust Type Changes the Game
Here’s what most people don’t understand about the trustor definition: your level of control isn’t fixed. It depends entirely on which type of trust you create. This single decision ripples through every aspect of your estate plan – from how much flexibility you keep to how well your assets are protected from creditors and taxes.
I’ve had clients walk into my office convinced all trusts work the same way. They couldn’t be more wrong. The choice between revocable and irrevocable trusts is like choosing between keeping the keys to your car or handing them over to someone else. Both have their place, but the consequences are dramatically different.
The Revocable Living Trust: The Trustor in the Driver’s Seat
With a revocable living trust, you’re still calling all the shots. Think of it as moving your assets into a different filing cabinet – one that happens to have some very useful legal benefits attached. But you still hold the key to that cabinet.
The beauty of revocable trusts lies in their flexibility. As the trustor, you can amend or revoke the trust whenever you want, as long as you’re mentally competent. Changed your mind about leaving money to your nephew who never calls? You can fix that. Want to add a new grandchild as a beneficiary? Done. This adaptability makes revocable trusts the Swiss Army knife of estate planning.
Most trustors in revocable living trusts serve as their own trustee initially. You manage your assets exactly as you did before, just under the trust’s legal umbrella. The transition is seamless – your daily financial life doesn’t change one bit.
But here’s where planning ahead matters: you must name a successor trustee. This person steps in if you become incapacitated or pass away. Without this backup plan, your family could face expensive guardianship proceedings or probate complications. The successor trustee provision is what makes revocable trusts so valuable for incapacity planning.
The biggest practical benefit? Avoiding probate. Assets in a properly funded revocable trust typically bypass the probate process entirely. That means faster, more private, and usually less expensive asset transfers to your beneficiaries when you’re gone.
The Irrevocable Trust: Giving Up Control for Greater Protection
Now we’re talking about a completely different animal. An irrevocable trust is like putting your assets in Fort Knox and handing someone else the combination. Once you fund it, you generally can’t change your mind or take the assets back. For many trustors, this feels terrifying. But sometimes giving up control is exactly what your family needs.
The trade-off comes with serious benefits, starting with asset protection. Because you no longer legally own assets once they’re in an irrevocable trust, they’re generally shielded from your future creditors, lawsuits, and even long-term care costs. This is where our Asset Vault Trust strategy shines – it’s specifically designed to create an impenetrable barrier around your wealth.
Creditor protection becomes crucial if you’re in a high-risk profession or business. Doctors, business owners, and anyone with significant liability exposure can use irrevocable trusts to move assets out of harm’s way before trouble strikes. The key word is “before” – you can’t wait until you’re already being sued.
The tax benefits can be substantial for larger estates. Assets transferred to an irrevocable trust are typically removed from your taxable estate, potentially saving hundreds of thousands in estate taxes. However, the trust itself becomes a separate taxpayer with compressed tax brackets – hitting the highest federal rate of 37% at just $14,450 of income in 2024.
Even with irrevocable trusts, smart planning can preserve some flexibility. Our Asset Vault Trust incorporates a special power of appointment, allowing a designated person (not you, the trustor) to modify who ultimately receives the assets. It’s like having a safety valve that maintains protection while adapting to changing family circumstances.
The 541 Trust structure offers similar benefits, creating maximum asset protection while building in strategic flexibility for unforeseen situations.
The Financial and Legal Aftermath for the Trustor
Once a trust is created, the trustor’s financial and legal landscape changes. Every choice a trustor makes—from the type of trust to the instructions left behind—ripples forward, shaping the family’s financial future for generations.
A Clearer Trustor Definition and Its Tax Implications
Understanding the tax implications of being a trustor isn’t just about compliance—it’s about keeping more of your wealth with your family. The trustor definition becomes clear when you see how the IRS treats different trust structures.
Grantor trust rules govern revocable trusts. Since the trustor can take everything back, the IRS treats you as the owner for tax purposes. All trust income—interest, dividends, capital gains—flows to your personal tax return. The trust is essentially invisible to the IRS.
Irrevocable trust tax rates tell a different story. Once you fund an irrevocable trust and give up control, it becomes its own taxpayer. The IRS is brutal here: trusts hit the highest federal tax bracket at just $14,450 of income in 2024, while individuals hit it at $609,350. This is why trust tax planning requires precision.
But the trade-off can be worth it: assets in a properly structured irrevocable trust are typically removed from your taxable estate, potentially saving millions.
The gift tax exclusion is crucial when funding irrevocable trusts. For 2024, you can gift $18,000 to each beneficiary without triggering gift tax. Anything above that counts against your lifetime exemption of $13.61 million. Smart trustors work with advisors to maximize these exclusions.
What Is a Trust?
Estate and Trust Administration Lawyer
The Trustor’s Role After Death or Incapacitation
This is when the trustor’s planning either shines or falls apart. The difference is how well the trustor understood their responsibilities while they were alive.
When death or incapacity strikes, the successor trustee takes over immediately. If you chose well, the transition is seamless. If you chose poorly—or not at all—the trust can get stuck in legal limbo.
Here’s what many don’t realize: a revocable trust becomes irrevocable the moment you die. Your flexibility is gone. Your instructions are set in stone, which is why clarity is critical. I’ve seen families spend tens of thousands arguing over what Dad “really meant.”
The trust document is final. Unlike a will, which a judge can interpret during probate, trust disputes often end up in expensive litigation. The trustor’s written words are the sole authority.
Your trust is the ultimate expression of your last wishes. A responsible trustor leaves behind not just assets, but a clear roadmap for their family’s financial future.
Probate and Trust Administration
Frequently Asked Questions About the Trustor’s Role
These are the questions that keep people up at night when they’re thinking about creating a trust. After 25 years of helping Arizona families steer estate planning, I can tell you these concerns come up in almost every consultation. Let’s cut through the confusion with straight answers.
Can a trustor also be the trustee?
Yes, absolutely. In fact, it’s not just possible—it’s incredibly common and often the smartest approach for a revocable living trust. You become a one-person show: you create the trust as the trustor, manage it as the trustee, and even benefit from it during your lifetime.
Think of it this way: you’re essentially having a conversation with yourself. “I, as the trustor, am instructing myself, as the trustee, to manage these assets according to my own rules.” It sounds a bit circular, but it works beautifully. You maintain complete control over your assets while gaining the benefits of trust ownership—like avoiding probate and planning for incapacity.
But here’s where it gets tricky. For an irrevocable trust designed for serious asset protection—like our Asset Vault Trust—the trustor absolutely cannot be the trustee. The whole point of asset protection is creating legal separation between you and your assets. If you’re still calling the shots as trustee, that separation doesn’t exist. Your creditors will see right through it, and so will the courts.
The trustee of an irrevocable trust must be truly independent. No winking and nudging allowed.
What’s the difference between a trustor, settlor, and grantor?
Here’s the truth that will save you from overthinking this: there is no functional difference whatsoever. These terms are completely interchangeable. They all refer to the same person—the one who creates the trust and funds it with assets.
The trustor definition stays exactly the same regardless of which word you use. You might encounter different terms based on where you live or which attorney drafted your documents. Here in Arizona, we commonly use “trustor.” Head east, and you might see “settlor” more often. “Grantor” pops up everywhere, especially in tax discussions.
Don’t let the terminology trip you up. Whether someone calls you the trustor, settlor, or grantor, you’re still the architect of the trust. You’re still the one making the critical decisions about your assets and your family’s future.
What are the biggest mistakes a trustor can make?
After watching families destroy themselves over poorly planned trusts, I can tell you exactly where trustors go wrong. These mistakes are like financial landmines—they might not explode immediately, but when they do, the damage is devastating.
The first disaster is writing ambiguous instructions that turn your trust into a battlefield. I’ve seen entire inheritances consumed by legal fees because a trustor used vague language like “reasonable support” or “appropriate education expenses.” What’s reasonable? A Honda Civic or a Mercedes? Community college or Harvard? When you’re gone, these fuzzy terms become weapons that beneficiaries use against each other in court.
The second catastrophe is choosing the wrong trustee. This is like handing the keys to your financial kingdom to someone who’s either incompetent, corrupt, or overwhelmed. I’ve watched trustees embezzle trust funds, make terrible investment decisions, or simply abandon their duties when things got complicated. Even well-meaning family members can accidentally destroy a trust through inexperience. Your brother might be a great guy, but can he handle complex tax filings, investment management, and family disputes while maintaining his fiduciary duties?
The third tragedy is creating an unfunded trust—essentially building a beautiful mansion and forgetting to move your furniture into it. This might be the most heartbreaking mistake because it’s completely preventable. You spend time and money creating the perfect trust document, then leave all your assets titled in your individual name. When you die, everything goes through probate anyway. The trust becomes an expensive piece of paper that accomplished nothing.
These aren’t theoretical problems; I’ve seen them tear families apart. The good news is they are all avoidable with proper planning.
Conclusion: Secure Your Legacy by Being a Smart Trustor
The trustor definition is more than legal jargon—it’s the foundation of your family’s financial future. As the trustor, you’re not just creating paperwork; you’re building a fortress around your legacy. Your decisions about trust structure, trustee selection, and asset funding will echo through generations.
I’ve watched families destroy themselves over poorly written trust documents. The trustor who thought “keep it simple” meant being vague. The trustor who picked their favorite child as trustee, ignoring the obvious conflict of interest. The trustor who spent thousands on legal fees but never bothered to retitle their house into the trust.
Here’s the brutal truth: Your trust is only as strong as the weakest decision you make as its trustor. Skip the funding step? Your family gets probate court instead of privacy. Choose an incompetent trustee? They’ll watch your life’s work evaporate through poor investments and legal fees. Write unclear distribution instructions? Your children will be fighting in court while lawyers bill by the hour.
But when you get it right—when you draft clear instructions, fund the trust properly, and choose trustees who actually understand their fiduciary duties—magic happens. Your assets flow seamlessly to your beneficiaries. Your family stays united. Your legacy becomes a source of strength, not strife.
At Sudden Wealth Protection Law, we’ve pulled families back from the brink of financial disaster. We’ve seen what works and what destroys wealth. The difference isn’t luck—it’s smart planning by trustors who understand that details matter.
Your trust document becomes your final word. Make sure it says exactly what you mean, in language so clear that even a hostile beneficiary can’t twist your intentions. Arizona families deserve estate plans that actually work when it matters most.
Don’t gamble with your legacy. To start building a rock-solid estate plan that protects your assets and your family, explore our resources on Wills and Trusts.

