

What Are Trusts For, Anyway?
If you’re here, chances are you’re looking for plain talk about trusts for dummies. You’ve heard the term, maybe seen it in movies, and now you want to know what the heck it is without needing a law degree. Good. You’ve come to the right place.
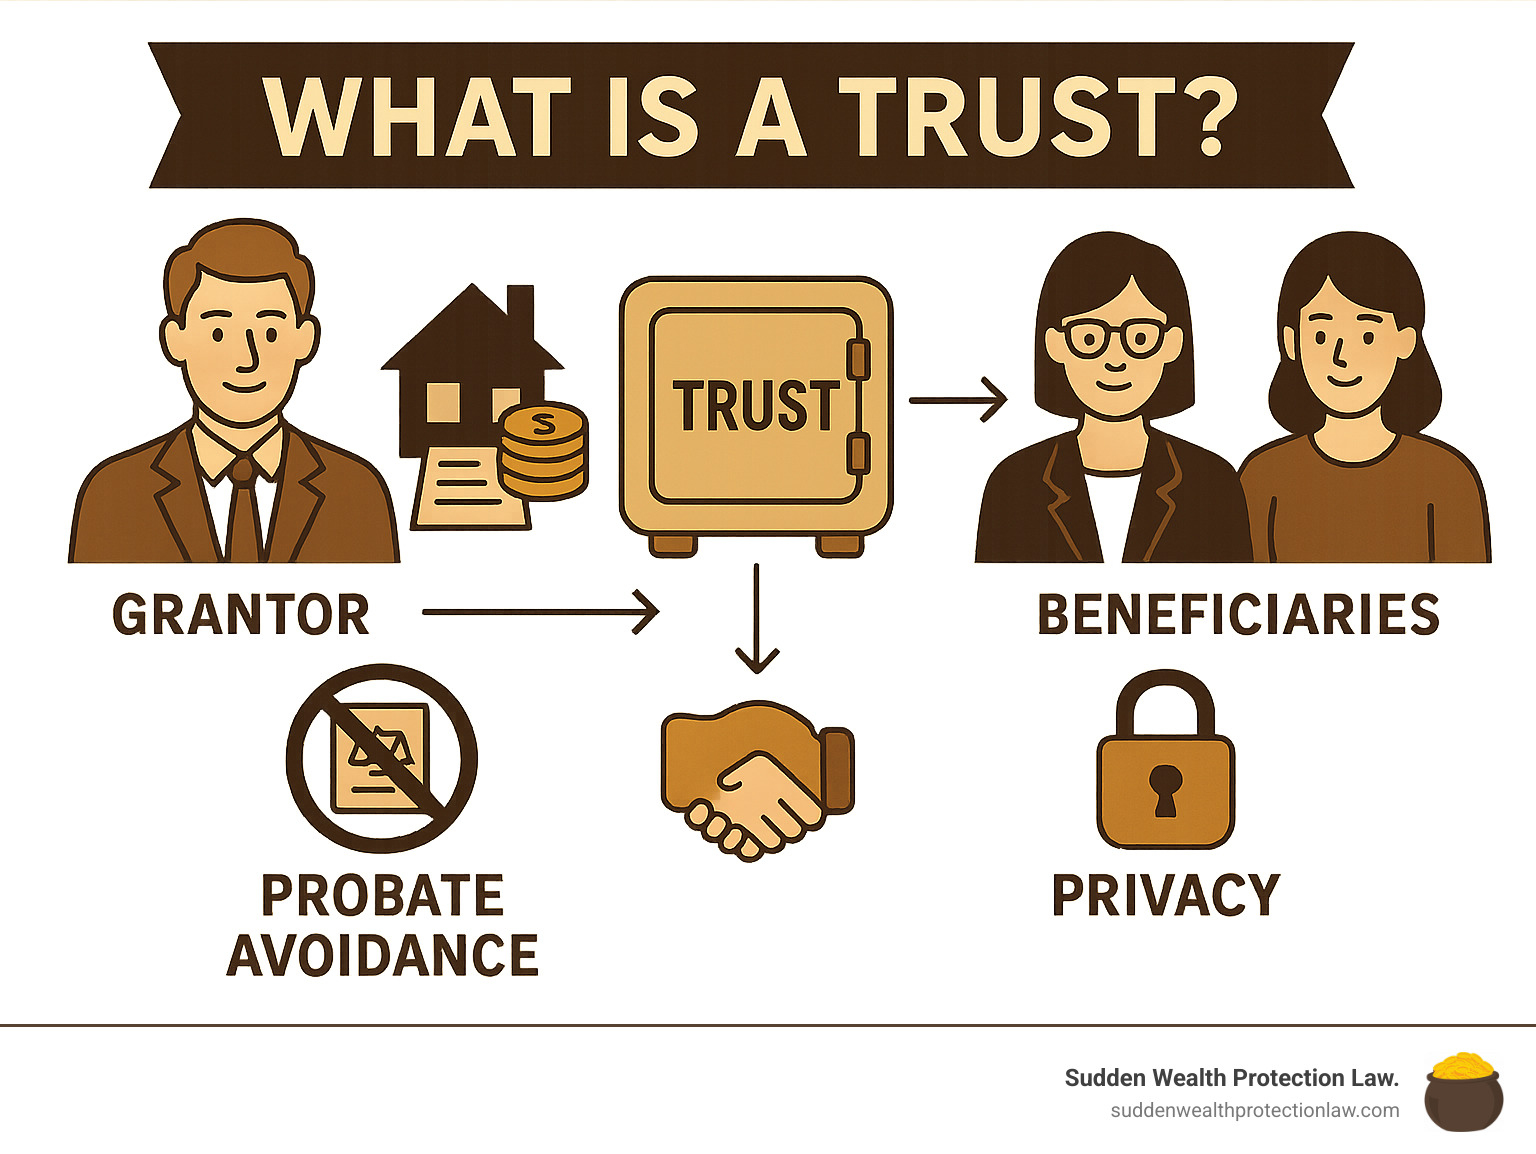
In simple terms, a trust is like a legal vault for your assets. Here’s the bare bones:
- What it is: A legal agreement where one person (the “grantor“) transfers assets to another person or entity (the “trustee“) to hold and manage for the benefit of specific people (the “beneficiaries“).
- Main Goal: To control your assets both during your life and after you’re gone. It’s often used to bypass the messy, public, and expensive process called probate.
- Key Players:
- Grantor (or Settlor): The person who creates the trust and puts assets into it. That’s you.
- Trustee: The person or entity who manages the assets according to the trust’s rules. They follow your marching orders.
- Beneficiary: The person or people who eventually benefit from the trust’s assets. Your family, your kids, whoever you want to get your stuff.
It might sound complex, but trusts are powerful tools. They can save your family a world of pain, like avoiding probate court, keeping your financial affairs private, and ensuring your wishes are followed without unnecessary delay or family conflict.
I’m Paul E. Deloughery, founder of Sudden Wealth Protection Law. For over two decades, I’ve seen how crucial it is to understand trusts for dummies, and I’ve dedicated my career to helping families like yours steer these choppy waters.
Related content about trusts for dummies:
The Pain Point: Probate, Taxes, and Family Feuds
Nobody wants to think about what happens after they’re gone. I get it. But here’s the thing – avoiding that conversation is like leaving a ticking time bomb for your family. In my two decades of practice, I’ve seen what happens when good people put off estate planning. Probate costs eat up inheritances, estate taxes take unnecessary bites, and what should be a time of healing becomes a legal battlefield.
How Probate Eats Your Estate Alive
Picture this: everything you’ve worked for gets dragged through a public court process that moves at the speed of molasses. That’s probate in a nutshell. It’s the legal proceeding that validates your will and supervises how your assets get distributed.
The time drain alone is brutal. Probate typically takes 9 to 24 months to complete, sometimes longer if there are complications. That’s nearly two years your loved ones might wait for what’s rightfully theirs, often while they’re still grieving.
Then there’s the financial bleeding. Assets that go through probate can lose 3 to 7 percent of their total value in court fees, legal costs, and administrative expenses. On a $500,000 estate, that’s $15,000 to $35,000 gone – money that should be going to your family, not feeding the court system.
But here’s what really gets me: the complete loss of privacy. Once your will hits probate court, it becomes a public record. Anyone can walk into the courthouse and see what you owned, who got what, and how much it was all worth.
Why Trusts Stop the Bleeding
This isn’t just about avoiding paperwork hassles. It’s about protecting your loved ones from unnecessary pain, expense, and family discord. This is where trusts become your family’s best friend.
The biggest win? Probate avoidance. Assets held in a properly funded trust bypass probate court entirely. Your beneficiaries can receive their inheritance in weeks, not months or years. It’s faster, cheaper, and completely private.
But trusts offer so much more. They provide privacy protection – what’s in a trust stays out of public records. Incapacity planning is another huge benefit. If you become incapacitated, your chosen trustee can step in seamlessly to manage your affairs.
Think of a trust as a direct, private pipeline from your assets to your loved ones. It bypasses all the public, costly, and time-consuming detours that probate creates.
For a deeper dive into how trusts stack up against wills and the probate process, check out our detailed guide: Trust vs Will vs Probate.
Trusts for Dummies: Key Building Blocks
Think of a trust like building a house. You need a solid foundation, the right materials, and people who know what they’re doing. Every trust is built on the same fundamental pieces. Once you understand these building blocks, the whole trusts for dummies concept becomes a lot less intimidating.
The cast of characters is straightforward. You’ve got the grantor (that’s you, the person creating the trust), the trustee (the person who manages everything), and the beneficiaries (the folks who benefit from your planning). The corpus is just a fancy word for the stuff you put into the trust – your assets, your property, your investments.
Here’s what makes this whole system work: fiduciary duty. This isn’t just a nice-to-have. It’s a legal obligation that means your trustee has to act in the best interests of your beneficiaries, period.
Trusts for Dummies 101 – What Exactly Is a Trust?
Here’s the simplest way to think about it: a trust is like a legal bucket that holds your assets. You decide who gets to manage the bucket, who gets to drink from it, and when they get to drink. The key difference from just giving someone your stuff directly is something called separation of title.
When you put assets into a trust, the trustee gets legal title – they’re the ones who can sign the papers, make the investment decisions, and handle the day-to-day management. But the beneficiaries get what’s called equitable title – they’re the ones who actually benefit from the assets.
This arrangement gives you lifetime control over your assets, even after you’ve technically transferred them. You write the rules in the trust document, and the trustee has to follow them. Want your kids to get money for college but not for a sports car? You can set that up.
The beauty of this system is that you maintain control without actually owning the assets anymore. That’s what helps you avoid probate and gives you privacy protection.
Still confused about who does what? We break it down in detail here: Trustee versus Trustor
Principal vs. Income
The assets you originally put into the trust are called the principal or corpus. But those assets often make money. Your stocks pay dividends, your real estate generates rent, your bonds pay interest. All that generated money is called income.
Why does this matter? Because you can set different rules for how the principal and income get distributed. Maybe you want your spouse to receive all the income during their lifetime, but the principal only goes to your children after your spouse passes away.
This is where distribution timing becomes crucial. The trustee has to understand not just what to distribute, but when to distribute it. They also have serious accounting duties – they need to keep meticulous records of what’s principal, what’s income, and where every dollar goes.
Want to dive deeper into how trust management actually works? Check out our guide: Trust Administration for Dummies
Popular Trust Flavors—Revocable, Irrevocable, and Beyond
Just like ordering at your favorite restaurant, choosing a trust isn’t one-size-fits-all. You’ve got options, and each one serves a different purpose. The two main categories you’ll hear about are revocable and irrevocable trusts, but there’s a whole menu of specialized options beyond those.
Let’s start with the most popular choice: the revocable living trust. This is the vanilla ice cream of trusts for dummies – not because it’s boring, but because it’s the go-to for most families. “Revocable” means you can change it, tweak it, or even scrap it entirely while you’re alive. You typically serve as your own trustee, keeping full control over your assets. The main benefits? You avoid probate and have a solid plan if you become incapacitated. The downside? Your assets are still considered yours for tax purposes, and creditors can still come after them.
Now, irrevocable trusts are a different beast entirely. Once you sign on the dotted line, that’s it – no take-backs, no do-overs. Why would anyone want that? Because giving up control comes with serious perks. The assets you place into an irrevocable trust are no longer legally yours, which means they’re removed from your taxable estate and protected from creditors and lawsuits.
There’s also the testamentary trust, which is created through your will and only kicks in after you die. Unlike living trusts, these still go through probate, but they’re useful for managing assets for minor children or beneficiaries who need ongoing guidance.
Here’s how the two main types stack up:
| Feature | Revocable Living Trust | Irrevocable Trust |
|---|---|---|
| Control | You retain full control; can modify or revoke. | You relinquish control; generally cannot be changed. |
| Probate | Avoids probate. | Avoids probate. |
| Asset Protection | No creditor protection; assets are still yours. | Strong creditor protection; assets are no longer yours. |
| Estate Tax | Assets are included in your taxable estate. | Assets are removed from your taxable estate. |
| Flexibility | High. | Low. |
| Cost | Generally lower setup than complex irrevocable trusts. | Can be higher setup due to complexity and ongoing administration. |
Your choice depends entirely on what you’re trying to accomplish. Want maximum flexibility with probate avoidance? Go revocable. Need bulletproof asset protection and tax advantages? Irrevocable might be your answer.
For a deeper dive into these two workhorses, check out: Revocable Trust vs Irrevocable Trust
Specialty Trust Spotlights
Beyond the basic flavors, there’s a whole world of specialized trusts designed to solve very specific problems.
The special needs trust is a lifesaver for families with disabled loved ones. It allows you to leave assets for someone with disabilities without jeopardizing their eligibility for crucial government benefits like Medicaid or SSI.
Got a beneficiary who’s terrible with money? A spendthrift trust acts like a financial safety net. The trustee controls when and how much money gets distributed, protecting the assets from both the beneficiary’s poor decisions and their creditors.
For those with charitable hearts, a charitable remainder trust lets you have your cake and eat it too. You donate assets to charity but still receive income from those assets for a set period.
The irrevocable life insurance trust is a powerhouse for high-net-worth families. By having the trust own your life insurance policy, the death benefit stays out of your taxable estate.
Finally, there’s what we call the Asset Vault Trust (also known as a 541 Trust). This is our specialized approach to asset protection here in Arizona. It’s irrevocable, so you get the creditor protection benefits, but it includes a special power of appointment that gives you more flexibility than traditional irrevocable trusts.
And for those thinking about multi-generational wealth transfer, there are trusts designed to skip generations for tax purposes. Learn more about them here: Generation Skipping Trusts for Dummies
The key is matching the right trust to your specific situation. That’s where experienced counsel becomes invaluable – helping you steer these options and choose the one that best serves your family’s unique needs.
Building Your Own Trust Toolkit: Steps, Funding, and Arizona Nuances
Alright, you’re sold on the idea of a trust. But how do you actually get from “I need a trust” to “I have a functioning trust that protects my family”? Creating a trust that actually works requires careful planning, proper execution, and—this is crucial—making sure your assets actually end up in the thing.
Step-by-Step Setup
Before you even pick up the phone to call an attorney, you need purpose clarity. What are you trying to accomplish? Are you mainly worried about avoiding probate? Protecting assets from future creditors? Your goals will determine what type of trust you need and how it should be structured.
Once you’re clear on your objectives, it’s time to hire qualified counsel. I’ve seen enough disasters from do-it-yourself trust kits and online templates to know they’re often more trouble than they’re worth. A properly drafted trust document, customized to your situation and compliant with Arizona law, typically costs between $1,000 and $3,000.
Your attorney will draft the trust document, which becomes the legal blueprint for everything that follows. This document names you as the grantor, identifies your chosen trustee and successor trustees, specifies your beneficiaries, and lays out all the rules for how your assets should be managed and distributed.
The signing ceremony might feel anticlimactic, but it’s important. You’ll sign the trust document in front of a notary public, making it legally binding. In Arizona, proper notarization is essential—without it, you don’t have a valid trust.
Here’s where many people stumble: funding the trust. This means formally transferring ownership of your assets from your individual name to the trust’s name. Your house deed, bank accounts, investment accounts, business interests—they all need to be retitled. This isn’t automatic. If you forget to transfer an asset, it won’t be governed by the trust and will likely end up in probate anyway.
Even with a trust, you still need a pour-over will. This acts as a safety net, stating that any assets you accidentally left out of your trust should be “poured over” into it after your death. You’ll also need to update beneficiary designations on retirement accounts, life insurance policies, and other assets.
Funding Fumbles to Avoid
The forgotten 401(k) is probably the most common mistake. Retirement accounts have their own beneficiary designations that override your trust unless you specifically name the trust as the beneficiary. But be careful here—naming a trust as beneficiary for an IRA can trigger complex tax consequences.
Out-of-state property creates another layer of complexity. If you own real estate in multiple states, each property needs to be retitled according to that state’s specific requirements.
Don’t forget about digital assets either. Cryptocurrency, online accounts, social media profiles, and digital business interests all need to be addressed in your trust planning.
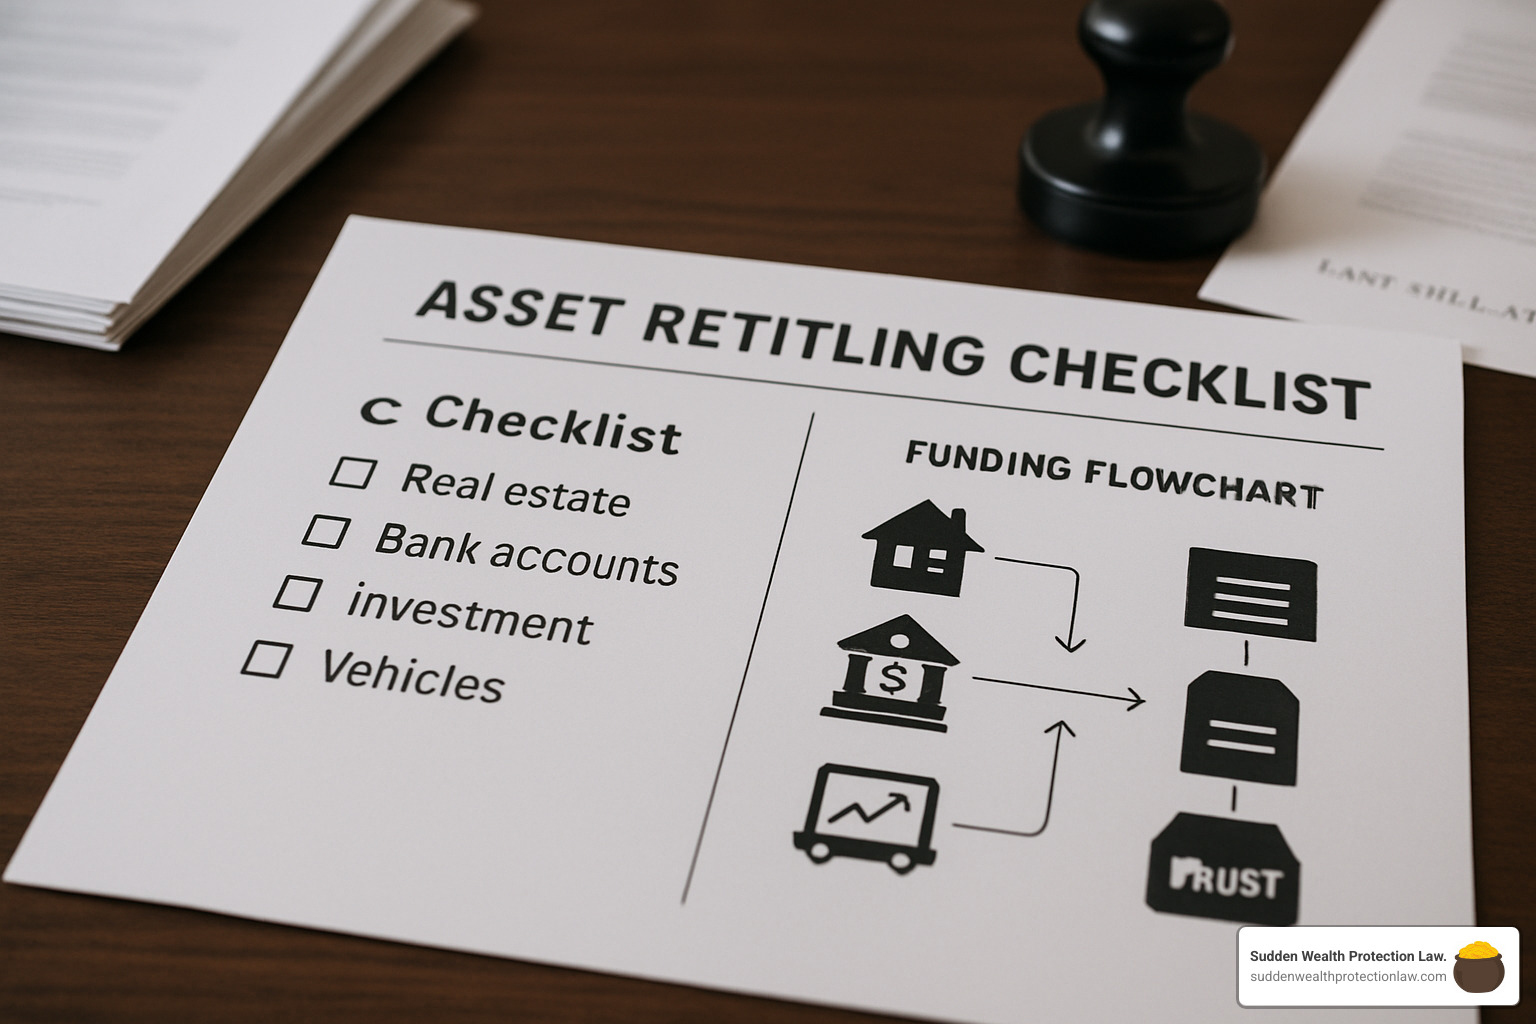
The bottom line? A trust is only as good as its funding. You can have the most sophisticated legal document in the world, but if your assets aren’t properly transferred into it, you’ve essentially bought an empty box.
For more insights on how proper funding affects your overall estate plan, including your Family Trust, the key is acting now, not “someday.”
The Trustee’s Playbook—Picking, Powers, and Pitfalls
Your trustee is the person who’ll carry out your wishes when you’re no longer around to do it yourself. They’re the ones who will manage your assets, make distributions, and deal with your beneficiaries. Get this choice wrong, and your carefully crafted trust can become a nightmare for your family.
How to Choose the Right Trustee
Choosing a trustee isn’t about picking your favorite person. It’s about finding someone who can handle the job. Your trustee needs to be financially savvy – they don’t need to be Warren Buffett, but they should understand basic finances, investments, and record-keeping.
Honesty and trustworthiness are non-negotiable. This person will have control over your assets. Look for someone with a track record of integrity, not just good intentions.
Your trustee also needs to be available and willing. Being a trustee is real work. It takes time, effort, and ongoing attention. Don’t pick someone who’s already stretched thin or sees this as just a honorary title.
Impartiality becomes crucial if you have multiple beneficiaries. Your trustee must be able to act without favoritism, even when family dynamics get messy.
Always have a successor plan. Name at least one, preferably two or three, successor trustees. What happens if your first choice dies, becomes incapacitated, or simply decides they don’t want the job anymore?
Many people automatically choose a trusted family member or friend, and that can work beautifully. But consider also naming a professional trustee – like a bank trust department or a professional fiduciary – as a co-trustee or successor.
Trustee Responsibilities Under the Microscope
Once someone accepts the role of trustee, they’re stepping into a legally binding relationship with serious responsibilities. The law doesn’t take trustee duties lightly, and neither should you.
The overarching principle is fiduciary duty. Your trustee must act solely in the best interests of the beneficiaries, not their own. This isn’t just a moral obligation – it’s a legal requirement that can result in personal liability if violated.
Asset protection and management means your trustee must hold and protect trust assets securely. This includes prudent investment management, often following the prudent investor rule, which requires them to invest wisely and diversify appropriately.
The accounting and record-keeping requirements are meticulous. Your trustee must keep detailed records of all income, expenses, and distributions. This includes preparing annual reports for beneficiaries, showing exactly what happened with the trust’s money during the year.
Tax filing is another crucial responsibility. Trusts are separate legal entities and often require their own federal identification number (EIN) and annual tax returns using Form 1041.
Making distributions to beneficiaries according to the trust terms sounds simple, but it can get complex quickly. Your trustee must follow your instructions precisely while also exercising discretion when the trust document allows it.
Beneficiary communication is often overlooked but legally required. Your trustee must keep beneficiaries reasonably informed about the trust’s administration.
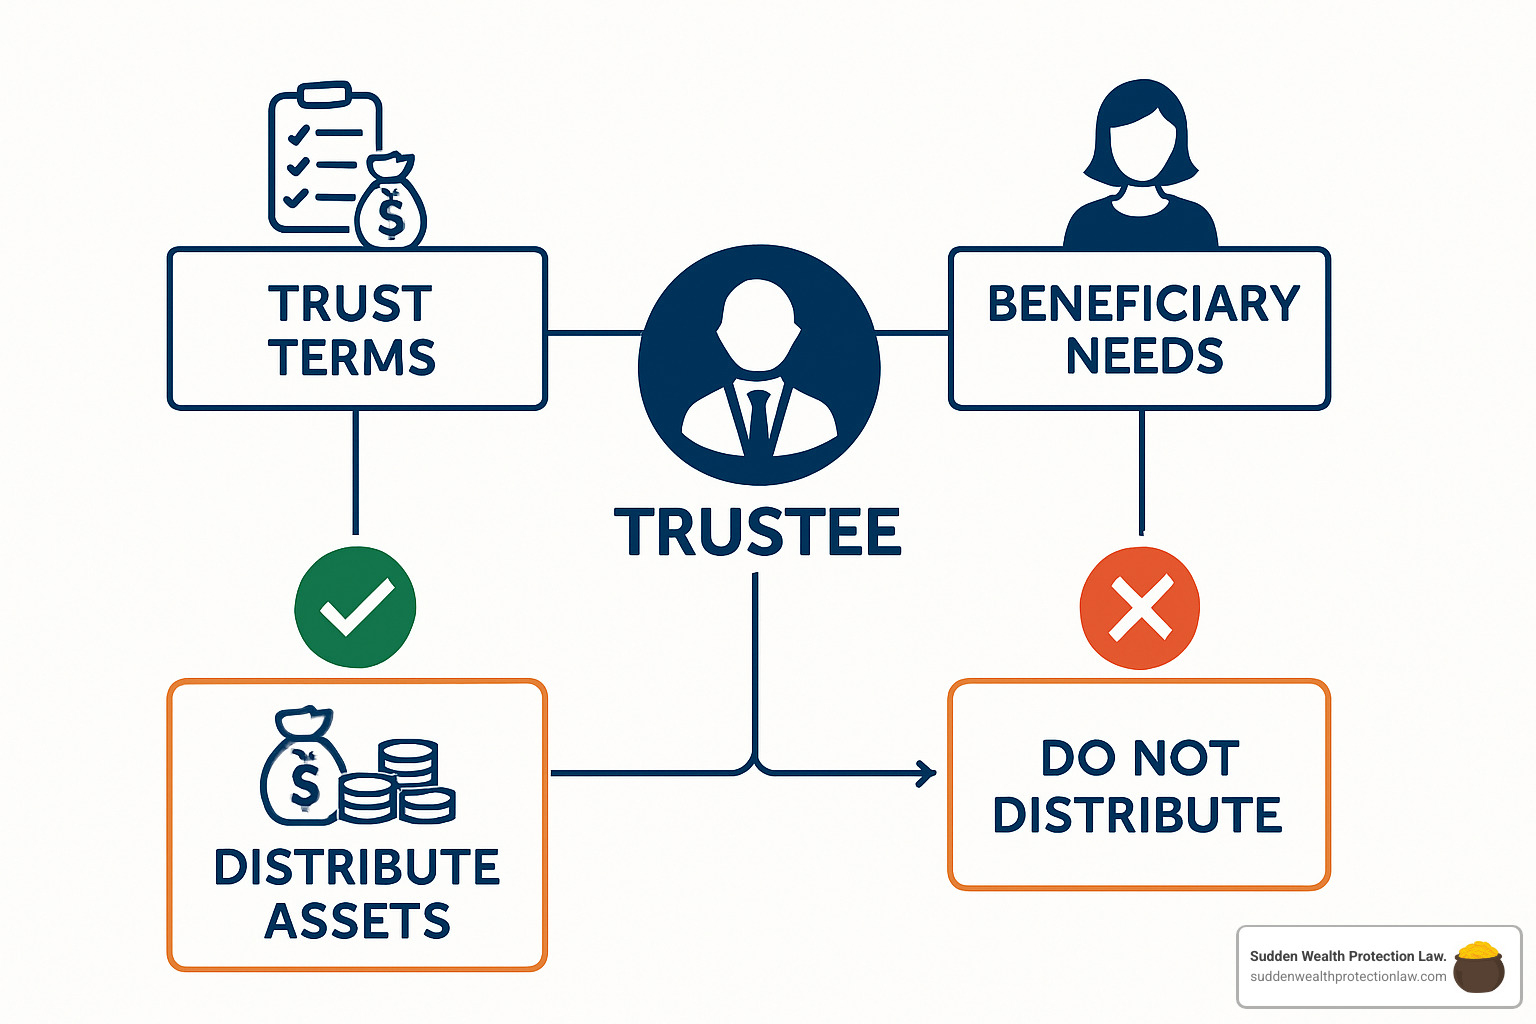
What happens when trustees go rogue? It’s not just a hypothetical – it happens more often than you’d think. When it does, it’s a mess that can tear families apart and drain trust assets through litigation. The law provides remedies, including removing trustees and holding them personally liable for losses, but prevention is always better than a cure.
That’s why clear trust language, careful trustee selection, and professional guidance are so important when setting up your trusts for dummies. Your trustee will be the guardian of your legacy – choose wisely.
Asset Protection the Arizona Way: When to Consider an Asset Vault Trust
Here’s where things get serious. If you’re a doctor worried about malpractice suits, a business owner with employees, or anyone who’s built real wealth and wants to keep it safe from future creditors, let’s talk about the Asset Vault Trust. This isn’t your typical trusts for dummies territory – it’s a specialized tool for people who understand that lawsuits happen, and they want their family’s legacy protected.
The Asset Vault Trust is an irrevocable trust, which means once you set it up, you generally can’t change your mind and take the assets back. But here’s the thing: this trust includes something called a special power of appointment, which gives you a surprising amount of flexibility even within that irrevocable framework.
Think of it this way: you’re moving your assets behind a creditor barrier. Once properly transferred into an Asset Vault Trust, those assets are legally owned by the trust, not by you personally. This creates a lawsuit shield that can protect your wealth from future creditors, business liabilities, and personal injury claims.
The beauty of this arrangement is that while you’ve technically given up ownership, you retain significant control through that special power of appointment. You can still influence who benefits from the trust assets, even though they’re no longer considered yours for creditor protection purposes.
Asset Vault Trust vs. Off-the-Shelf Hybrids
You might come across other asset protection trusts marketed elsewhere, but when it comes to protecting your wealth in Arizona, precision matters. Our Asset Vault Trust is specifically designed to work within Arizona statute §14-10505, which provides strong protections for properly structured irrevocable trusts.
Here’s what makes it different: Arizona law includes a three-year look-back period for creditor claims against trust assets. This means that if you transfer assets into an Asset Vault Trust and a creditor claim arises more than three years later, those assets are generally protected.
The control retention aspect is crucial too. While you’re giving up direct ownership, the special power of appointment allows you to redirect trust benefits among a defined class of beneficiaries. This irrevocable flexibility means you’re not locked into rigid distribution terms that might not make sense years down the road.
It’s not a decision to make lightly. The Asset Vault Trust requires careful planning, proper funding, and ongoing administration. But for those who need serious asset protection – whether from professional liability, business risks, or just the general lawsuit-happy culture we live in – it’s one of the most powerful tools available.
Want to dive deeper into how this works? Check out our detailed guide: Advantages of Asset Vault Trust

