

Why Living Trust Administration Is More Complex Than You Think
Living trust administration is the process of managing and distributing a deceased person’s trust assets according to their wishes. It involves gathering assets, paying debts, filing taxes, and distributing property to beneficiaries—all while avoiding the costly probate process.
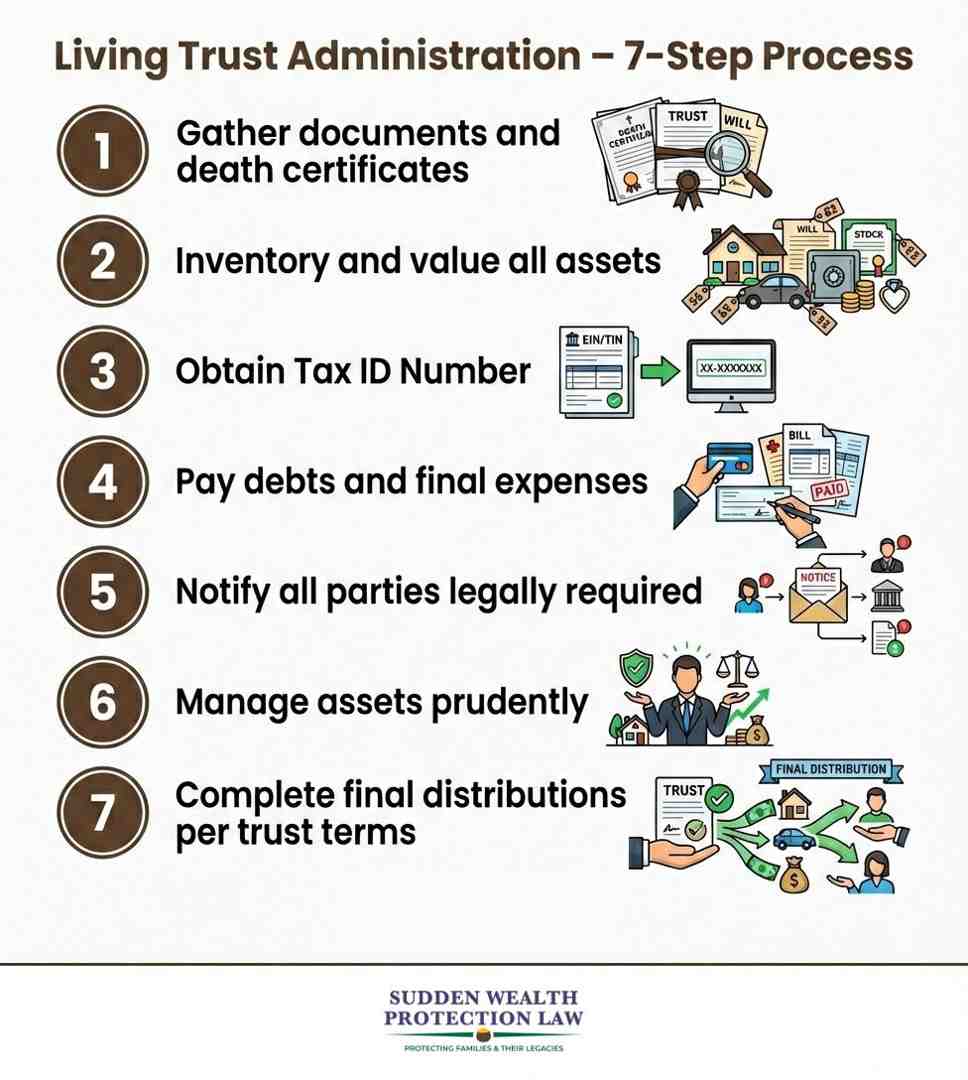
Key Steps in Living Trust Administration:
- Locate the trust document and obtain death certificates
- Inventory all trust assets and obtain appraisals
- Get a Tax ID Number (EIN) for the trust
- Pay final debts and taxes owed by the deceased
- Notify beneficiaries and creditors according to state law
- Manage trust property using the prudent investor rule
- Distribute assets according to trust terms
- File final tax returns and close the trust
Here’s the reality: being named successor trustee isn’t an honor—it’s a legal minefield. One client told me, “I thought this would take a few weeks. It’s been eight months, and I’m still finding assets I didn’t know existed.”
Most people think trust administration is just writing checks. Wrong. You’re the CEO of a company being liquidated, with personal liability hanging over every decision. The IRS is watching, creditors want their money, and beneficiaries are scrutinizing your every move.
As Paul E. Deloughery, founder of Sudden Wealth Protection Law, I’ve guided countless trustees through the complexities of living trust administration. I’ve seen how inherited wealth disappears without proper legal guidance. The difference between a smooth administration and a family-destroying disaster often comes down to understanding your fiduciary duties from day one.
Essential living trust administration terms:
First Things First: Taking the Helm as Successor Trustee
So, you’ve been named successor trustee. It sounds like an honor, but it feels like being handed a live grenade. Before you do anything, you need to understand your role and the legal battlefield you’ve just entered. Getting this wrong can lead to personal liability and family feuds that last for generations.
Your first mission is to find the original trust document. It’s your roadmap, spelling out who gets what, when, and what powers you have. Without it, you’re flying blind in living trust administration.
While you’re hunting for the trust, order at least five to ten certified copies of the death certificate. These are your golden tickets for dealing with banks, insurance companies, and government agencies. Photocopies won’t work.
Now for the legal heavy lifting. As a successor trustee, you have a fiduciary duty. What is a fiduciary? This means you must act with complete loyalty, putting the beneficiaries’ interests ahead of your own. This isn’t about being nice—it’s about avoiding lawsuits.
Your fiduciary duty means no self-dealing, no shortcuts, and no playing favorites. I’ve seen trustees use trust funds for personal expenses—a one-way ticket to personal liability. The beneficiaries are counting on you to follow the rules. This duty of loyalty is absolute. It means you cannot borrow from the trust, sell your own property to the trust, or purchase trust assets for yourself, even at what you believe is a fair price, without explicit authority in the trust or court approval. Every decision must be made with the sole purpose of benefiting the beneficiaries as outlined in the trust document. Meticulous record-keeping of every decision and transaction is not just good practice; it’s your primary defense against future claims of mismanagement.
Many new trustees miss this: formally accepting your role matters. A formal Trustee Acceptance document protects you legally, establishing when your responsibilities began and shielding you from claims about prior actions. This document, often filed with the court or sent to beneficiaries, creates a clear starting line for your duties and liabilities, preventing you from being held responsible for the actions of a prior trustee.
Understanding what does a trustee do is crucial. Read the entire trust document. If you don’t have a legal background, get help from a trust administration attorney. Don’t guess. The cost of guidance is far less than the cost of mistakes.
The trust document is your bible and your shield. It protects you when beneficiaries complain and relatives question your decisions. Stick to what it says, document everything, and you’ll survive this process with your sanity and assets intact.
The Core of Living Trust Administration: Marshalling and Managing Assets
This is where the real work begins. Your job is to act like a CEO of a company being liquidated. You must find every asset, get it under your control, and manage it wisely. The tax man is watching, creditors are waiting, and beneficiaries are scrutinizing your every move. This isn’t just writing checks; it’s a meticulous, legally-defensible process.
Your first mission is to identify and inventory all trust assets. This means everything: real estate, bank accounts, investments, jewelry, and even digital assets. I’ve seen trustees find forgotten Bitcoin wallets and old stock certificates. Create a detailed spreadsheet documenting each asset’s description, location, and date-of-death value. This list protects you from claims that you “lost” something and is your roadmap for the entire living trust administration.
For significant assets like real estate or business interests, professional appraisals are not optional. This is critical for tax purposes, as assets get a “stepped-up basis” at the date of death, which can save beneficiaries thousands in future capital gains taxes. Don’t guess at values; it can lead to breach of trust claims.
Next, you must get a Tax ID Number (EIN) for the trust immediately. After the grantor’s death, the trust becomes its own tax entity. You’ll need this EIN to open trust bank accounts and file tax returns. You can complete Form SS-4 on the IRS website; see their Information on Taxpayer Identification Numbers (TIN). Critical warning: never use your personal Social Security Number for trust accounts. Commingling funds is a fast track to personal liability. Commingling funds—mixing trust assets with your own personal assets—is one of the most serious breaches of fiduciary duty. It creates a bookkeeping nightmare and raises immediate suspicions of self-dealing. Even if your intentions are pure, such as temporarily covering a trust expense from your personal account, it can be misconstrued as mismanagement. You must maintain a pristine separation between the trust’s finances and your own. Open a dedicated trust checking account using the new EIN and run every single trust-related income and expense item through that account. This creates a clean, defensible paper trail.
Then, you must pay the decedent’s final debts and expenses. Verify every debt before paying. If you distribute assets to beneficiaries before paying legitimate creditors, you can be held personally liable. This means creditors can come after your personal assets.
Finally, managing trust property requires you to follow the prudent investor rule. You must manage and invest assets as a reasonable person would, preserving capital and avoiding unnecessary risk. You’re not trying to hit home runs in the stock market. If you’re not a financial expert, hire one. An Estate and Trust Administration Lawyer is invaluable here—they’ve seen the landmines you haven’t. Remember to keep meticulous records of every single transaction. Poor record-keeping is the most common reason trustees end up in court.
Dealing with People: Beneficiaries, Heirs, and Professionals
The hardest part of living trust administration isn’t the paperwork; it’s the people. You’ll have beneficiaries wanting their money yesterday and relatives questioning every decision. Your duty is to the trust document, not to making everyone happy. Clear, formal communication is your legal shield.
Proactive communication is key to managing expectations and minimizing conflict. At the outset, consider holding a meeting or sending a detailed letter to all beneficiaries explaining the trust administration process, your role as trustee, and a realistic (but non-binding) timeline. Explain that the process involves several mandatory steps, such as inventorying assets, paying creditors, and filing taxes, which must be completed before final distributions can be made. Setting these expectations early can prevent a barrage of ‘where’s my money?’ phone calls and build a foundation of trust and transparency.
Notifying beneficiaries and heirs is your first critical, non-negotiable step. While Arizona doesn’t have a strict 60-day notice rule like some states (see this example of strict state notification laws), you are still legally required to inform all beneficiaries and legal heirs of the trust’s existence. Your notice should include your contact information and inform them of their right to receive a copy of the trust. This starts the clock on any potential challenges.
The importance of formal notice cannot be overstated. Don’t use casual phone calls or texts. Send notices via certified mail with return receipt requested. This paper trail is your best friend if anyone later claims they weren’t informed.
Providing accountings is another cornerstone of protecting yourself. Even if the trust or state law doesn’t require it, providing regular, detailed accountings is smart. Show beneficiaries all assets, income, expenses, and distributions. This transparency builds trust and can limit the time beneficiaries have to challenge your actions.
Handling disputes and conflicts is inevitable. When beneficiaries question the trust or your decisions, address concerns head-on with clear explanations, and document everything. If someone is upset, your response should be: “Here’s what the trust document says, and here’s how I followed it.” If tensions escalate, consider mediation before litigation.
When to hire an attorney or CPA? The answer is simple: early and often. Unless you’re an expert yourself, you need professional guidance. A trust administration attorney helps you interpret the trust, steer legal requirements, and protect you from personal liability. A CPA handles tax filings. These professional fees are typically paid from trust assets, not your pocket. For comprehensive support, our team at Sudden Wealth Protection Law offers specialized guidance in Probate and Trust Administration to ensure you’re protected.
The Final Stretch: Distributing Assets and Closing the Trust
After the assets are gathered, the debts are paid, and the taxes are filed, you can finally move to the last step: distributing what’s left. But even this is a minefield. You must follow the trust’s instructions to the letter, whether it’s a simple lump-sum payout or a complex, multi-year distribution. One wrong move here, and all your hard work can be undone by a lawsuit.
Interpreting distribution terms is where many trustees stumble. Some trusts are beautifully straightforward: “Divide everything equally among my three children.” Others read like a legal puzzle, with staged distributions tied to birthdays, college graduation, or marriage milestones. Then there are the discretionary distributions that give you power to decide what a beneficiary “needs” for health, education, maintenance, and support.
Here’s the reality: if there’s even a hint of ambiguity in the trust language, stop and call your attorney. I’ve seen families torn apart because a trustee made their best guess about what “reasonable living expenses” meant, only to face a lawsuit from an angry beneficiary who disagreed.
Outright distributions are the simplest path forward. You cut the checks, transfer the property titles, and everyone walks away happy. The trust closes quickly, and your liability exposure ends. But staged distributions require you to keep the trust alive for years, sometimes decades. You’ll continue filing annual tax returns, managing investments, and dealing with beneficiaries who may grow increasingly impatient with each passing year.
Discretionary distributions put you in the hot seat as judge and jury of a beneficiary’s needs. The trust might say you can distribute funds for “education,” but does that include the beneficiary’s child’s private school tuition? What about that expensive graduate degree in art history? These decisions require careful documentation of your reasoning, because you’ll likely be asked to justify them later.
Preparing final trust tax returns using Form 1041 is non-negotiable. This federal income tax return for the trust must be filed annually throughout the trust’s life, with a final return marked “Final” when you close everything down. Don’t forget Arizona’s requirements – you may also need to file Arizona Form 141AZ for state income tax purposes.
The clock is ticking on these tax obligations. The trust becomes its own taxpaying entity after the grantor’s death, and the IRS doesn’t care if you’re overwhelmed or confused. Miss a filing deadline, and you’re looking at penalties and interest that come straight out of the beneficiaries’ inheritance.
Getting receipts and releases from beneficiaries is your final insurance policy. Before you hand over that inheritance check or transfer that real estate deed, have every beneficiary sign a document acknowledging what they received. More importantly, try to get them to release you from future liability for your actions as trustee.
I know this sounds harsh after months of living trust administration, but people’s attitudes toward money can change quickly. The grateful beneficiary who thanked you profusely in January might decide by December that you should have invested differently or sold that property for more money. A signed release is your shield against Monday morning quarterbacking.
Formally terminating the trust means crossing every ‘t’ and dotting every ‘i’. You can’t just distribute the last dollar and call it done. The trust remains a legal entity until you’ve satisfied every obligation, filed every final return, and properly dissolved the structure.
For those seeking more foundational information about trust structures, our Trusts for Dummies guide provides helpful context.
The Last Details of Living Trust Administration
The devil lives in these final details, and skipping any of them can come back to haunt you. Final accounting to beneficiaries should be comprehensive, showing every transaction from the day you took over as trustee until the final distribution. Even if you’ve been providing regular updates, this final accounting serves as your complete report card.
Calculating distributions requires mathematical precision that would make an accountant proud. Double-check every number, account for every prior distribution, and ensure each beneficiary receives exactly what the trust specifies. A $500 error might seem small, but it can trigger accusations of favoritism or incompetence that drag on for months.
Transferring titles of property involves a parade of paperwork. Real estate requires new deeds recorded at the county recorder’s office. Vehicles need title transfers through the motor vehicle department. Investment accounts require specific forms and signatures. Each transfer must clearly show the property moving from the trust to the individual beneficiary.
Closing trust bank accounts should happen only after every last expense is paid and every distribution is complete. Keep enough funds available for final professional fees, recording costs, and any last-minute expenses that pop up. Once you close these accounts, reopening them becomes a bureaucratic nightmare.
Filing the final Form 1041 marks the official end of the trust’s tax life. Mark this return clearly as “Final” so the IRS knows the trust is closing permanently. Any mistakes here can result in the IRS continuing to expect annual returns from a trust that no longer exists, creating headaches that can last for years.
The finish line of living trust administration isn’t when you think you’re done – it’s when every legal requirement is satisfied, every beneficiary has signed off, and every government agency has been properly notified. Only then can you finally exhale and know that your fiduciary duties are truly complete.
Frequently Asked Questions about Living Trust Administration
How is living trust administration different from probate?
Think of probate as having your family’s financial business conducted in a fishbowl. It’s a court-supervised process that’s public, often expensive, and can drag on for a year or more. Every asset, every debt, every family squabble gets aired in public records for anyone to see.
Living trust administration, on the other hand, is like handling family business around the kitchen table – it’s private. The trustee manages the process without mandatory court oversight. It’s generally faster and less costly, but here’s the catch: it places a huge burden of responsibility and liability squarely on the trustee’s shoulders.
The key difference is the lack of court involvement. You have more freedom, but with that freedom comes more responsibility. No judge is looking over your shoulder to approve every decision, which means you better know what you’re doing from day one.
What happens if the trust wasn’t funded properly?
An unfunded or partially funded trust is like having a beautiful sports car sitting in the driveway with no keys. It looks impressive, but it won’t get you where you need to go.
If assets were never formally transferred into the trust’s name, they don’t avoid probate. You may have to open a probate case just to get those assets into the trust via a “pour-over” will. This defeats one of the main purposes of creating the trust in the first place – avoiding probate entirely.
This is why proper funding is crucial when families are learning How to Create a Living Trust in Arizona. I’ve seen too many families think they’re all set with their estate plan, only to find that half their assets were never actually moved into the trust. It’s a costly mess that could have been easily avoided.
How long does trust administration take?
Anyone who tells you living trust administration is quick is either lying or incompetent. Let me be blunt: there’s no such thing as a “quick and easy” trust administration.
A simple, clean administration with cooperative beneficiaries and straightforward assets might take six to nine months. But that’s the best-case scenario. If you have a business to sell, real estate in multiple states to manage, or beneficiaries who are fighting over every decision, it can easily take a year or more.
Here’s the hard truth: rushing the process is the fastest way to get sued. Every shortcut you take today becomes a potential lawsuit tomorrow. Better to take your time and do it right than to spend years in court defending your mistakes.
What are common challenges that arise during trust administration?
Having guided countless families through this process, I’ve “seen the bloodshed” from these disputes. The most common challenges include beneficiary disagreements over asset valuations, distribution timelines, or even your competence as trustee. Money has a way of bringing out the worst in people.
Unclear trust language is another landmine. When the trust document is ambiguous, different beneficiaries will interpret it in ways that benefit them most. Unfunded assets complicate everything, as we discussed earlier. Unexpected creditor claims can surface months after you think you’ve identified all debts.
Tax complexities trip up many trustees. Incorrect tax filings can lead to penalties and personal liability. Finally, there’s trustee burnout – it’s exhausting work, and exhausted people make mistakes. The emotional toll of managing family dynamics while handling complex legal and financial matters can overwhelm even well-intentioned trustees.
When should a trustee seek professional legal or financial advice?
The short answer? Always. The longer answer? If you have any doubt, any question, or any inkling that you’re in over your head, pick up the phone.
Specifically, seek advice when the trust document is complex or unclear, when beneficiaries are disputing anything, or when there are significant tax implications. If you’re dealing with unusual assets like a family business or unique collections, professional guidance isn’t optional.
Don’t wait until you’re drowning. The cost of professional advice upfront is typically far less than the cost of fixing mistakes later. Most importantly, if you fear personal liability for any decision you’re making, that fear is your gut telling you to get help. Listen to it.
Your Job is Done, But Your Liability May Not Be
You’ve made it through the gauntlet. The assets are distributed, the final tax returns are filed, and the beneficiaries have their inheritances. Time to celebrate, right?
Not so fast.
Here’s what most trustees don’t realize: completing the living trust administration doesn’t automatically shield you from future liability. Your fiduciary duties may have ended, but claims against your actions as trustee can surface for years afterward. I’ve seen trustees who thought they were home free get hit with lawsuits three years later because a beneficiary finded an overlooked asset or questioned a distribution decision.
Think of it this way: you’ve successfully steerd through a minefield, but some of those mines have delayed fuses. Without proper documentation, formal releases, and professional guidance throughout the process, you could still step on one.
The statute of limitations for trustee liability varies, but in Arizona, beneficiaries generally have several years to challenge your actions. That’s several years of potential sleepless nights wondering if someone will come knocking with a lawsuit. The only way to truly protect yourself is to have handled every step of the administration process correctly from the beginning.
These delayed claims can take many forms: a beneficiary might argue you sold a property for too little, made imprudent investments, paid yourself excessive fees, or failed to distribute assets according to a complex clause in the trust. This is precisely why obtaining a signed receipt and release from every beneficiary upon final distribution is so critical. While not an impenetrable shield, a formal release where beneficiaries acknowledge receipt of their full share and release you from further liability significantly shortens the window for them to bring a claim and provides powerful evidence that you completed your duties to their satisfaction.
This is why living trust administration isn’t a DIY project, despite what some online guides might suggest. One missed creditor notice, one improperly valued asset, one distribution made without proper authority – any of these seemingly small mistakes can expose you to personal liability that far exceeds what you might have saved by going it alone.
The difference between a clean administration and a legal nightmare often comes down to having experienced counsel from day one. At Sudden Wealth Protection Law, we’ve guided countless trustees through this complex process, helping them avoid the pitfalls that can destroy families and drain trust assets. We’ve “seen the bloodshed” from trustees who tried to handle everything themselves, only to face years of litigation afterward.
Your role as trustee comes with serious legal responsibilities and real financial risks. Getting it right isn’t just about following the trust document – it’s about protecting yourself and preserving the legacy you’ve been entrusted to manage.
If you’re facing the daunting task of living trust administration, don’t steer this minefield alone. Professional legal guidance isn’t an expense – it’s insurance against personal liability and family destruction. To ensure you’re protected and the trust is administered properly, schedule a consultation on our Probate and Trust Administration page.

