

Why Blended Families Face Unique Estate Planning Challenges
Estate planning for blended families is one of the most complex areas of estate law – and the stakes couldn’t be higher. When families include children from previous marriages, current spouses, and sometimes new children together, traditional estate plans often fail spectacularly.
Key Estate Planning Essentials for Blended Families:
- Protect all beneficiaries – Both biological children and stepchildren need explicit protection
- Use trusts over simple wills – Control asset distribution and prevent accidental disinheritance
- Address the “spouse trap” – Leaving everything to your spouse can cut out your children permanently
- Plan for remarriage scenarios – Your surviving spouse may remarry and redirect your assets
- Choose neutral fiduciaries – Avoid conflicts between spouses and children from prior marriages
- Update beneficiary designations – These override your will and must align with your overall plan
The numbers tell the story: 40% of new marriages involve at least one spouse who’s been married before, and over 16% of children in the U.S. live in blended families. Yet most estate plans treat these families like traditional nuclear families – a recipe for disaster.
After 25 years in law, I’ve seen these plans go wrong in devastating ways: surviving spouses accidentally disinheriting stepchildren, children from a first marriage receiving nothing, and family battles that destroy relationships for generations.
The good news? With the right strategies – including specialized trusts, careful beneficiary planning, and clear communication – you can protect everyone you love while avoiding the courthouse drama.
I’m Paul E. Deloughery, founder of Sudden Wealth Protection Law in Phoenix. For over two decades, I’ve helped Arizona families steer these exact challenges. I’ve dedicated my practice to ensuring estate planning for blended families protects every family member according to your true wishes.
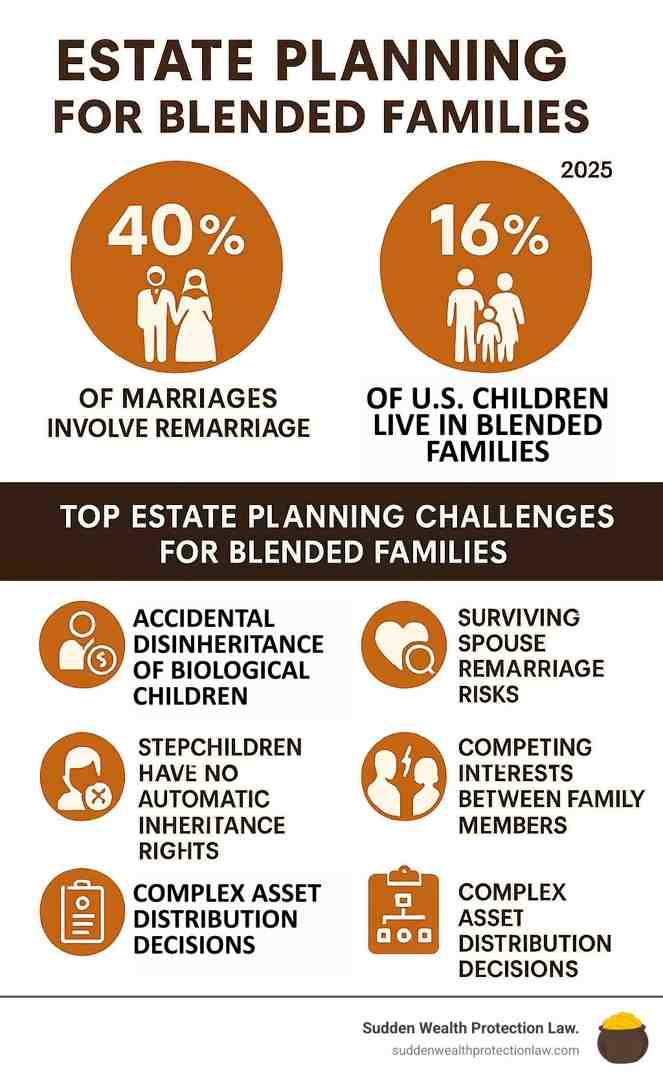
Key terms for estate planning for blended families:
A traditional estate plan—spouse gets everything, then the kids—is dangerously simplistic for a blended family. The dynamics are inherently more complex. Each spouse often brings their own children and assets into the marriage, creating a “yours, mine, and ours” scenario ripe with potential conflict and unintended consequences.
This isn’t a niche issue; it’s the new normal. Yet, estate planning laws and templates are often outdated, designed for traditional nuclear families. This creates competing interests between a surviving spouse and children from a previous marriage. Without a clear, ironclad plan, these questions are left to chance or a judge—a scenario that often shatters relationships and evaporates inheritances.
The “Leave it to Your Spouse” Trap and Accidental Disinheritance
A common, heartbreaking mistake is leaving everything outright to a current spouse, assuming they will provide for your children from a previous marriage. This is the “leave it to your spouse” trap, and it’s a gamble with your children’s inheritance.
Leaving assets directly to your surviving spouse gives them complete control. They can spend it, invest it poorly, or change their will. If they remarry, their new partner could become the beneficiary of your wealth, leaving your children from a previous marriage with nothing. This isn’t always malicious; it’s often accidental or due to new loyalties. The result, however, is the same: your children are disinherited, sparking devastating family feuds. The risk of this unintended outcome is incredibly high without proper safeguards.
The Legal Reality for Stepchildren and Outdated Plans in Arizona
In most jurisdictions, including Arizona, stepchildren have no automatic right to inherit from a stepparent. Unlike biological or adopted children, they have no legal standing under intestacy laws (the laws governing inheritance without a will). If you intend for your stepchildren to inherit, you must explicitly name them in your legal documents. Do not assume your wishes will be known or followed.
Relying on outdated plans is another major pitfall. Remarriage can automatically revoke a prior will in many states. If you haven’t updated your documents, your old plan may be invalid. Furthermore, beneficiary designations on accounts like IRAs, 401(k)s, and life insurance policies override your will. If an ex-spouse is still named on an old 401(k), they will receive those funds, regardless of your will’s instructions. This crucial detail is often overlooked in the complexity of blended families.
Beyond inheritance, think about planning for your children’s future, especially if they are minors. Who would care for them if something happened to both you and your spouse? Nominating guardians in your will is critical. This is tied into Guardianships and Conservatorships, ensuring your children are cared for by people you trust, not by the courts.
Key Strategies for Estate Planning for Blended Families
Now that we’ve outlined the risks, let’s focus on effective strategies. Successful estate planning for blended families isn’t about a single solution but a comprehensive strategy built on three core principles: controlling asset distribution, protecting all beneficiaries, and maintaining control over your legacy. This requires a custom plan that addresses your family’s unique relationships and assets, not a cookie-cutter template.
Wills vs. Prenups: Setting the Ground Rules
Establishing the ground rules while you’re both alive and thinking clearly is the first step. Wills and prenuptial agreements work together to create your family’s financial foundation.
Traditional mirror wills, where each spouse leaves everything to the other, are risky for blended families. After the first spouse dies, the survivor can change their will, potentially disinheriting the deceased’s children.
Mutual wills offer a solution. These are legally binding contracts that prevent the surviving spouse from changing the will after the first one dies. This “locks in” your plan to protect all designated beneficiaries, though it reduces flexibility for the survivor to adapt to new circumstances. (As a lawyer, I almost never see mutual wills. The better alternative is to rely on language in a trust to protect descendants from disinheritance.)
Prenuptial and postnuptial agreements are also vital. In blended families, these agreements aren’t just about divorce; they are crucial for defining separate property versus marital property, protecting pre-marital assets, and ensuring those assets pass to your intended heirs.
A well-crafted prenup can specify that each spouse waives their spousal share—the legal right to claim a percentage of the deceased’s estate. This protects assets like a family business, a prior inheritance, or college funds established for your children.
Think of these documents as your family’s constitution – they establish the fundamental rules that everything else builds upon.
Why Trusts are the Cornerstone of Estate Planning for Blended Families
Trusts are the powerhouse tools for estate planning for blended families. While a will simply distributes your assets, a trust provides ongoing control over how and when they are distributed. You create a detailed set of instructions that can adapt to future circumstances, protect beneficiaries from poor decisions, and ensure your wishes are precisely followed.
| Feature | Wills | Trusts |
|---|---|---|
| Control | Distributes assets outright; no control after death | Controls how and when assets are distributed, even over generations |
| Probate | Requires probate (court process); public record | Avoids probate; private process |
| Flexibility | Limited; can be challenged | Highly flexible; can adapt to changing circumstances |
| Protection | Assets vulnerable to creditors/lawsuits after distribution | Can offer asset protection for beneficiaries |
| Complexity | Simpler to set up initially | More complex to set up; ongoing administration |
For more detailed information, check out our comprehensive guide on Wills and Trusts.
The probate avoidance alone makes trusts worth considering. Probate is a public, time-consuming, and expensive court process. With a trust, your family’s financial business stays private, and your beneficiaries can access their inheritance much faster.
The key benefits are creditor protection and control over distributions. A trust can distribute funds for specific purposes, like education, preventing a beneficiary from squandering a lump sum. It can also provide for your spouse during their lifetime while guaranteeing the remainder passes to your biological children.
Let me walk you through some specific trust types that work beautifully for blended families:
Qualified Terminable Interest Property (QTIP) Trusts are a game-changer. You fund the trust, and your surviving spouse receives income from it for life. When they die, the remaining assets pass to beneficiaries you designated (e.g., your children from a prior marriage). This provides for your spouse while ensuring your children cannot be disinherited.
Bypass Trusts (or Credit Shelter Trusts) help minimize estate taxes for larger estates. When the first spouse dies, assets up to the federal exemption limit are placed in an irrevocable trust. This bypasses the surviving spouse’s estate, allowing the assets to pass tax-free to your chosen beneficiaries while still potentially providing income to the surviving spouse.
For robust protection from creditors or lawsuits, specialized tools like an Arizona Asset Protection Trust are available. Our Asset Vault Trust, for example, is a powerful irrevocable trust that offers maximum flexibility and asset protection, ensuring your family’s wealth is shielded from unforeseen financial challenges.
The Strategic Role of Life Insurance
Life insurance in blended family planning isn’t just about replacing your income – it’s about creating fairness and solving logistical problems that would otherwise tear families apart.
For example, if you leave the family home to your current spouse, a life insurance policy can equalize inheritances. It provides a direct, tax-free death benefit to your children from a first marriage, ensuring they receive a meaningful inheritance independent of the home or your spouse’s future decisions.
Life insurance also provides crucial liquidity. Many estates have illiquid assets like real estate or businesses. The immediate cash from a policy can pay estate taxes, debts, and other expenses without forcing the sale of these valuable assets.
Funding a trust with life insurance proceeds is another strategic use. This is ideal for providing for a stepchild or creating a long-term financial foundation without giving direct control over a large sum of money. The trust manages and distributes the funds according to your instructions.
Perhaps most importantly, life insurance bypasses probate entirely when you name direct beneficiaries. This means immediate access to funds for your family without the delays, costs, or public scrutiny of the court process.
Life insurance is a flexible, efficient tool that can bridge gaps between competing interests. It is often the key to achieving fairness in complex blended family situations.
Executing Your Plan: Fiduciaries, Communication, and Maintenance
You can craft the most brilliant estate planning for blended families document ever written, but if you don’t have the right people executing it and your family doesn’t understand it, you’re setting everyone up for failure. Think of it this way: a perfect blueprint doesn’t build a house – you need skilled contractors and clear communication with everyone involved.
After 25 years of watching family dynamics play out in courtrooms, I can tell you that the most neat trust can turn into a battlefield if you choose the wrong trustee or leave your family guessing about your intentions. The execution phase is where good plans either thrive or die a messy death.
Choosing Fiduciaries in Estate Planning for Blended Families
Choosing your executor and trustee is a critical, and potentially explosive, decision. These fiduciaries make real-time financial decisions that impact family relationships. In a blended family, these choices can make or break your legacy.
Naming your spouse as trustee is a common mistake. The reality is that your surviving spouse has their own interests, which may not align with those of your children from a previous marriage.
Imagine your spouse is trustee for a trust benefiting both them and your children. When making investment decisions, your spouse may prioritize their own retirement security (conservative bonds) while your children want to maximize their inheritance (growth stocks). This inherent conflict of interest creates tension and blame.
This is why a neutral professional fiduciary is often the best choice for blended families. While they charge a fee (typically 1-1.5% of trust assets annually), this cost is minimal compared to family litigation, which can consume over 10% of an estate and cause irreparable emotional damage.
A professional trustee impartially follows the trust document, avoiding favoritism between biological children and stepchildren or conflicts if your spouse remarries. Understanding the roles of a Trustee vs. Beneficiary and What Does a Trustee Do? is key to preventing family heartache.
If you choose a family member as trustee, be aware of potential conflicts. Consider building in safeguards, such as requiring unanimous beneficiary consent for major decisions or appointing a neutral tie-breaker.
Planning for Incapacity and Communicating Your Wishes
Estate planning for blended families must also address incapacity. This is another area where blended family dynamics can quickly become complicated and contentious.
Who makes your medical and financial decisions if you can’t? In a blended family, your current spouse and your children from a previous marriage may have conflicting ideas about your care.
A comprehensive Power of Attorney is crucial. It must clearly state who has authority for specific decisions and in what order. For example, your spouse could handle daily finances while major decisions require input from your adult children, or your eldest child could be your healthcare agent.
The key is being intentional about these choices and documenting them clearly. Don’t leave your family guessing or fighting over who has the right to make decisions for you.
The secret weapon for preventing disputes is the family meeting. While it may sound daunting, it is incredibly effective.
Gather your spouse, children, and stepchildren to explain your plan—not just the “what” but the “why.” Explain your reasoning for the trust structure, your choice of trustee, and the specific provisions for each family member.
This conversation prevents more disputes than any legal document. When family members understand your reasoning, they are less likely to feel slighted or suspicious. They may not love every decision, but they will understand it came from a place of love and careful thought.
This conversation may be awkward, but it’s far less so than your family finding your wishes for the first time after your death, when emotions are raw and questions cannot be answered.
Successful estate planning for blended families is an ongoing conversation, not a one-time transaction. The families who get it right regularly update their plans, communicate openly, and choose impartial fiduciaries who can steer complex family dynamics.
Conclusion: Building a Plan That Protects Everyone
As we’ve seen, estate planning for blended families is a minefield. Standard estate plans, designed for traditional families, often fail spectacularly when stepchildren, multiple marriages, and competing loyalties are involved.
Remember the key pitfalls: leaving everything to a spouse can disinherit your children, stepchildren have no automatic inheritance rights in Arizona, and outdated plans or beneficiary designations can render your wishes invalid.
The good news is that every one of these problems is preventable. The right tools—like QTIP trusts to protect all beneficiaries, life insurance to create fairness, and professional fiduciaries to ensure impartiality—can solve these challenges.
After 25 years of practice, my key insight is that there is no cookie-cutter solution. Every blended family’s financial situation, relationships, and needs are unique, creating a puzzle that requires a custom-designed plan.
Using a simple will for a complex family often leads to court battles, with heartbreaking emotional and financial costs. Conversely, families who invest in a proper plan from the start protect their relationships and legacy, ensuring fairness is built into the structure and love is protected by law.
At Sudden Wealth Protection Law, we specialize in these complex situations. We understand your “yours, mine, and ours” family deserves a unique estate plan. Our approach combines legal expertise with the clear communication needed to prevent future misunderstandings.
The bottom line? You can’t afford to leave this to chance. Your blended family has brought you joy and complexity in equal measure – your estate plan should honor both.
If you’re ready to build a plan that protects everyone you love, contact us to discuss your estate planning needs. Let’s make sure your legacy creates harmony, not headlines.

